

Form ET-30 at a glance
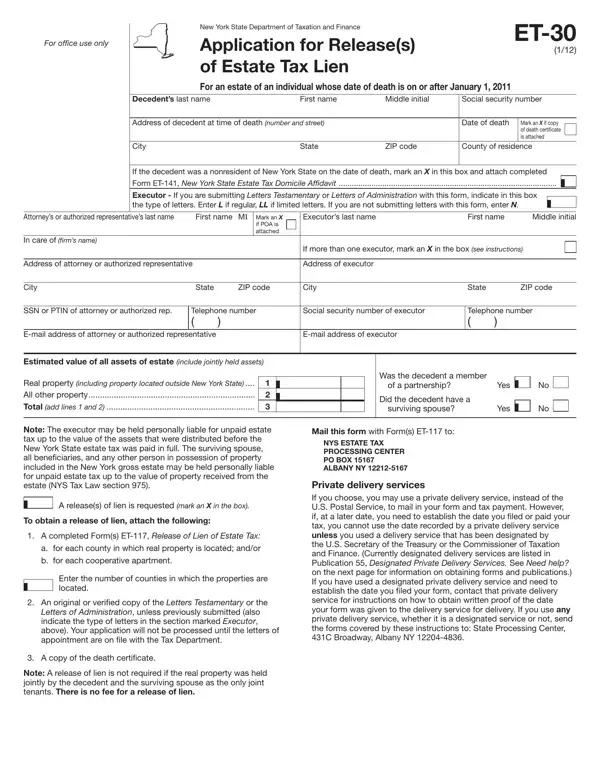
What it is: Form ET-30, the Application for Release(s) Of Estate Tax Lien, is for an estate of an individual whose date of death is on or after January 1, 2011.
Who signs: Signature of executor, Date, Signature of co-executor, Date.
A filled-in Form ET-30 example: an executor applies for a lien release
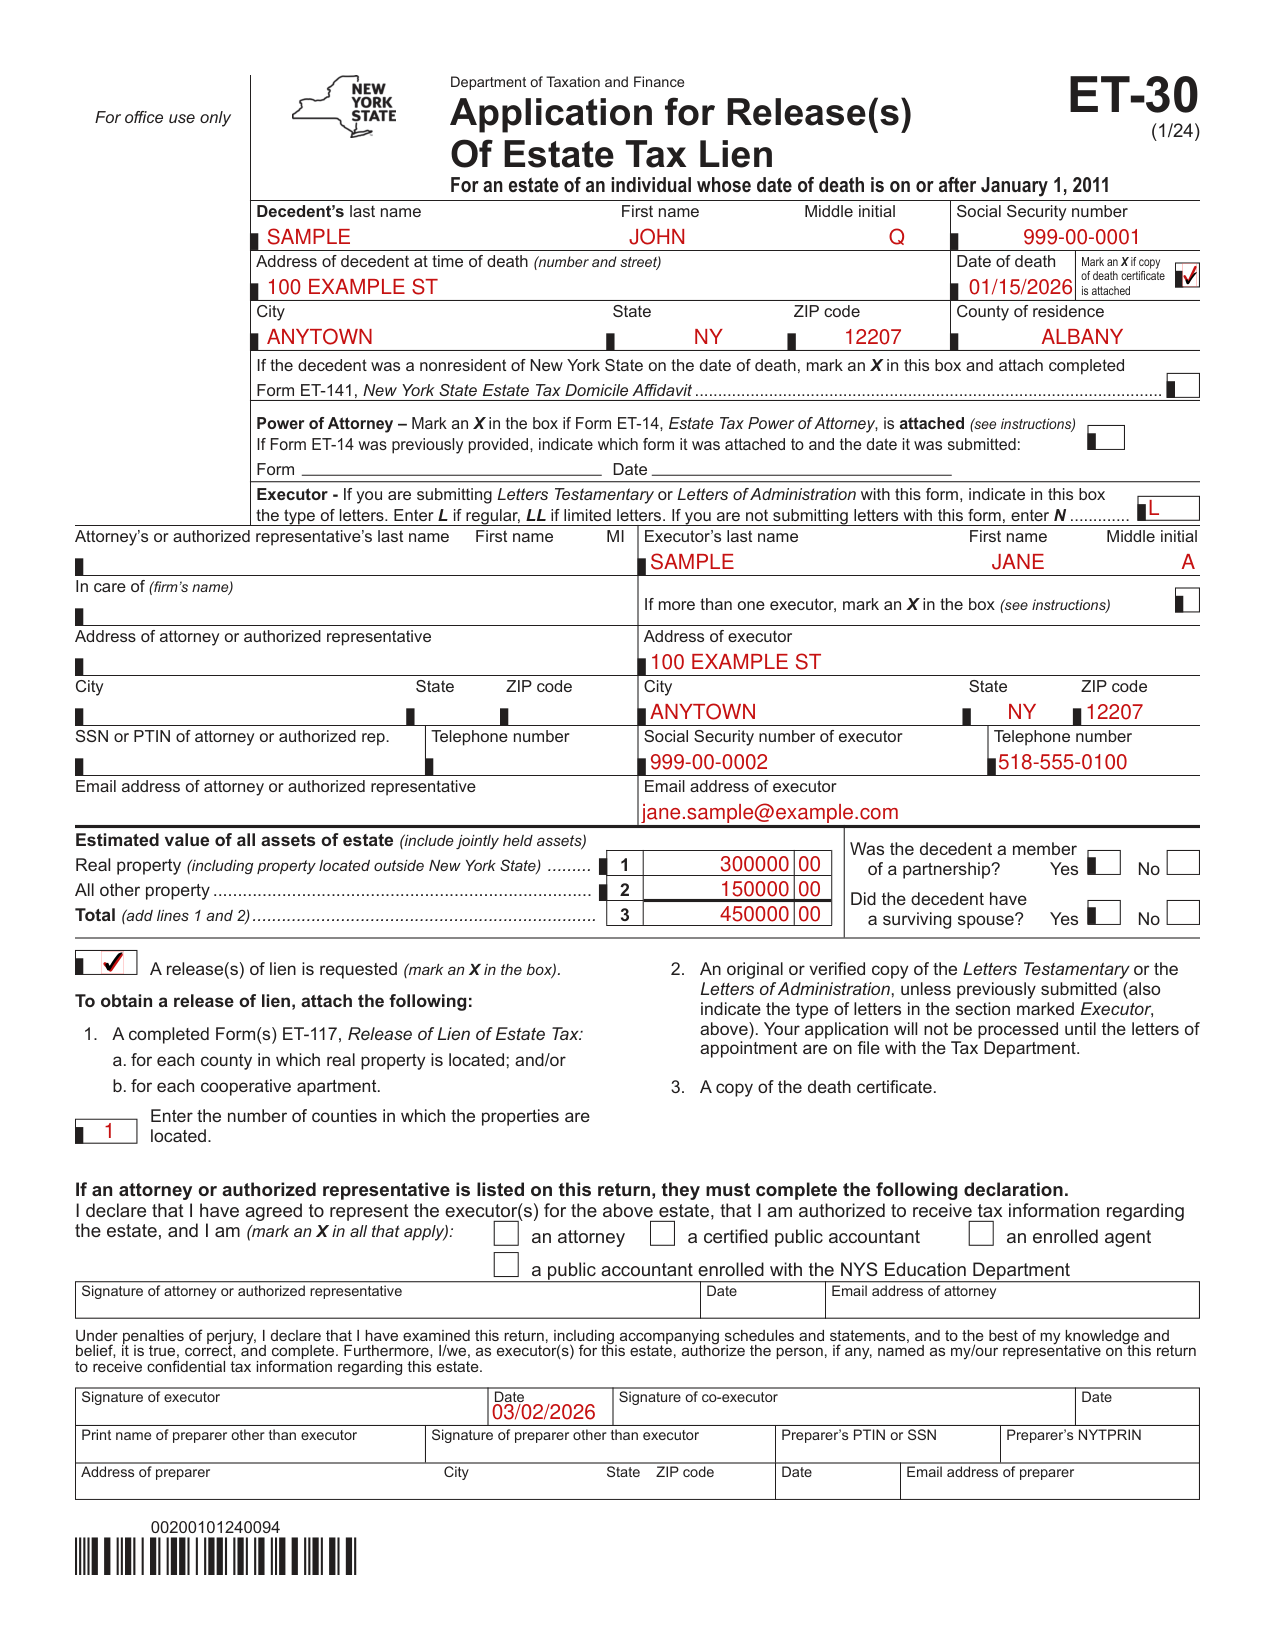
How to fill out Form ET-30, box by box
The decedent
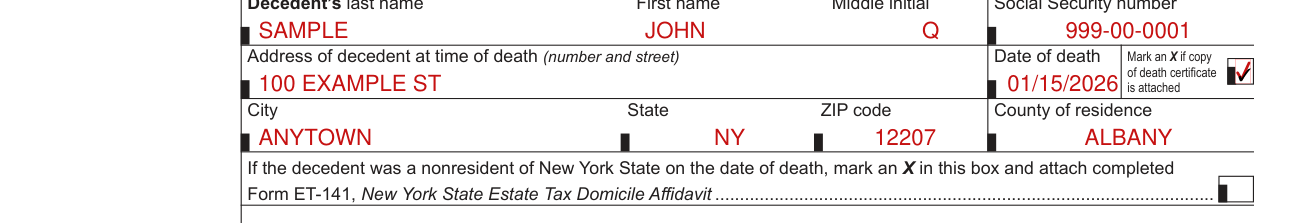
Complete the information requested about the decedent. Verify that the decedent's Social Security number is correctly entered on the application.
Submit a photocopy of the death certificate with the application, and mark an X if a copy of the death certificate is attached.
If the decedent was a nonresident of New York State on the date of death, mark an X in this box and attach completed Form ET-141, New York State Estate Tax Domicile Affidavit. For the estate of an individual who was not a resident of New York State at the time of their death, complete Form ET-141 and attach it to the return.
Power of Attorney
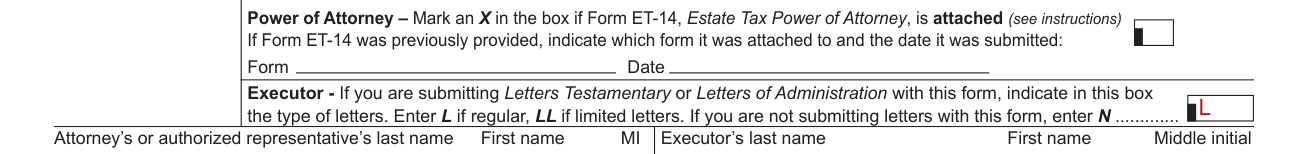
If the executor has signed Form ET-14, Estate Tax Power of Attorney, and it is being submitted with this application, attach it to the application and mark an X in the box.
Unless a change in representation or authority is being made, Form ET-14 should only be submitted to the department once. You do not have to send the ET-14 in with each estate tax form you file.
If Form ET-14 was previously provided, indicate which form it was attached to and the date it was submitted.
The executor and the letters
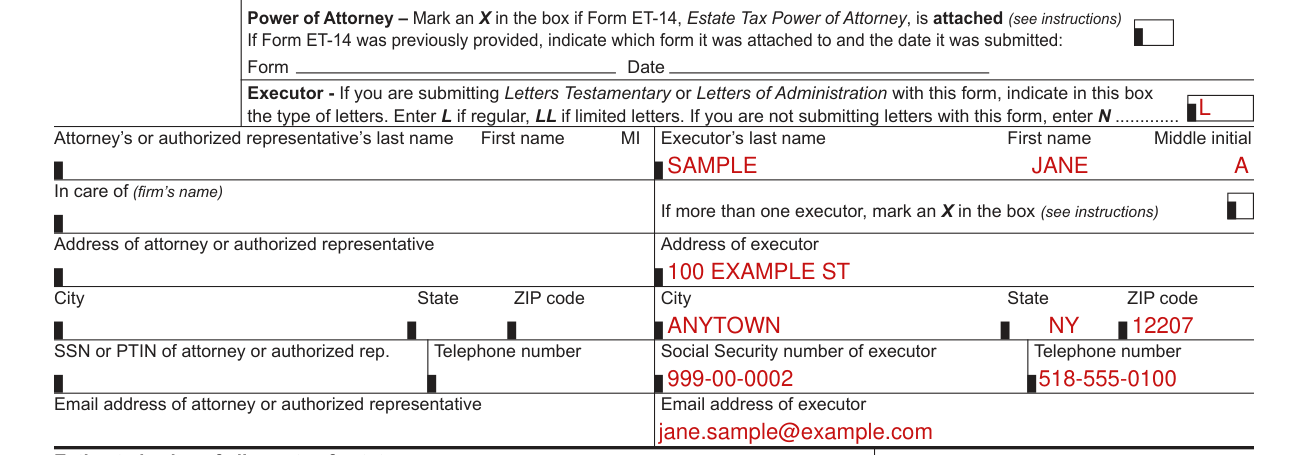
If you are submitting Letters Testamentary or Letters of Administration with this form, indicate in this box the type of letters. Enter L if regular, LL if limited letters. If you are not submitting letters with this form, enter N.
Submit either Letters Testamentary or Letters of Administration with the application as proof of your appointment, unless previously submitted. To be acceptable, the letters of appointment must be current and must not restrict the executor from receiving estate assets.
Letters of appointment issued by a court outside New York State are acceptable if the decedent was not a resident of New York State at the time of death, and the court has jurisdiction over the decedent's estate.
An original or verified copy of the Letters Testamentary or the Letters of Administration, unless previously submitted (also indicate the type of letters in the section marked Executor). Your application will not be processed until the letters of appointment are on file with the Tax Department.
Enter the executor's name, address, Social Security number, and telephone number in the area provided: Executor's last name, First name, Middle initial.
If the estate has more than one executor, enter the information for any executor (preferably one who is a New York State resident) in the area provided, mark an X in the box, and attach a list of the other executors with their addresses, telephone numbers, and Social Security numbers.
Attorney or authorized representative
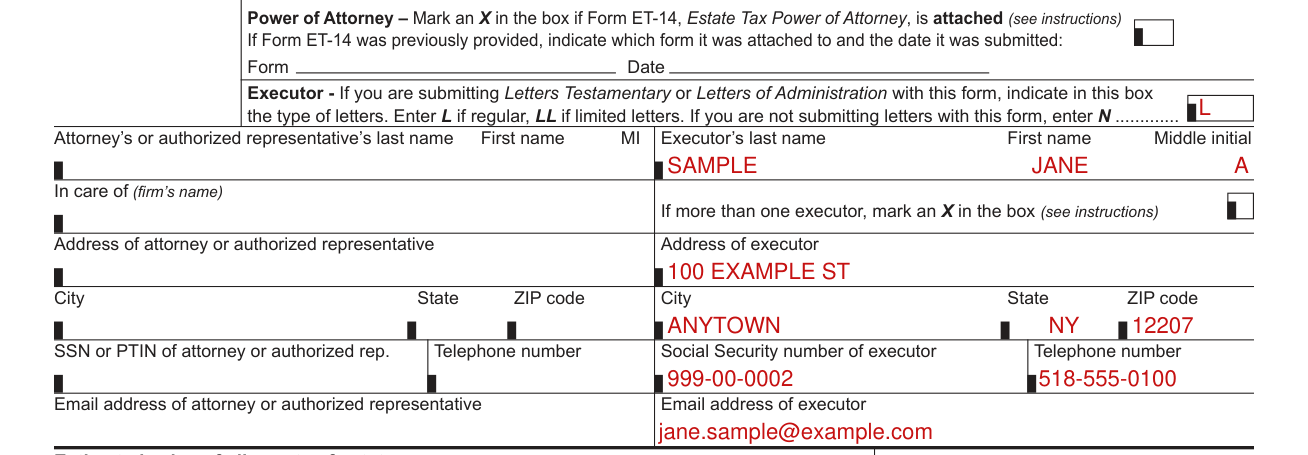
If a person is authorized to represent the executor regarding the estate, and the executor prefers the department contact that person, enter the name (last name first) of the attorney, accountant, or enrolled agent representing the executor. Also enter the firm's name, address, and telephone number in the areas provided.
Estimated value of all assets of the estate

Estimated value of all assets of estate (include jointly held assets) Real property (including property located outside New York State) 1; All other property 2; Total (add lines 1 and 2) 3.
Mark Yes or No. Was the decedent a member of a partnership? Did the decedent have a surviving spouse?
Release of lien and what to attach
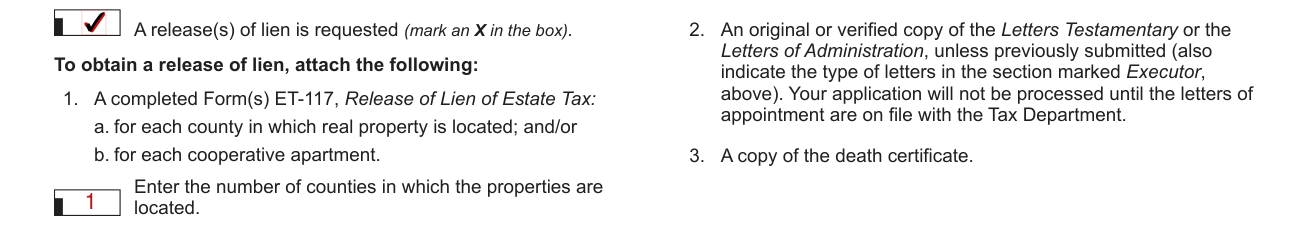
A release(s) of lien is requested (mark an X in the box).
Complete and attach Form ET-117, Release of Lien of Estate Tax, if a release of lien is needed for real property or a cooperative apartment.
Two parcels of real estate can be listed on one form. However, if the real property is located in different counties or a release of lien is needed for more than one cooperative apartment, a separate Form ET-117 must be completed for each county or apartment. The name and address of the executor, or authorized representative, should be entered at the top of Form ET-117 for mailing purposes.
Enter the number of counties in which the properties are located.
Signing, the declaration and the preparer
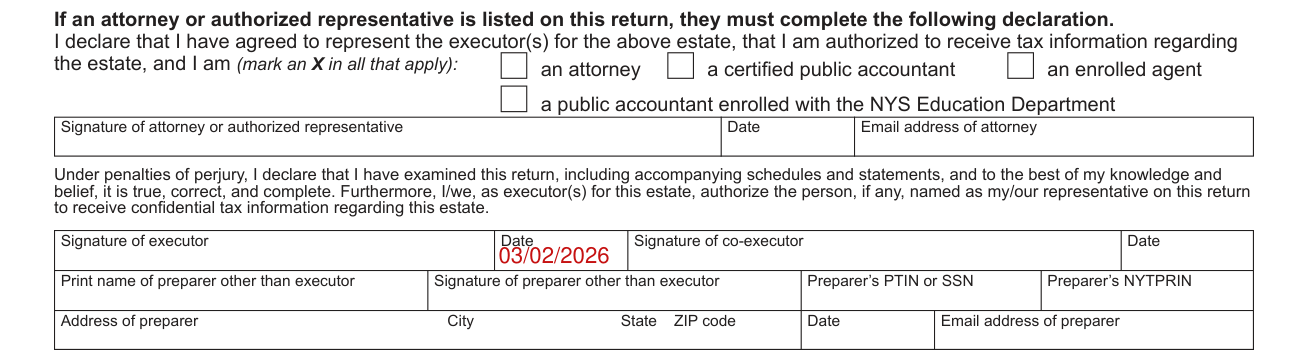
If an attorney or authorized representative is listed on this return, they must complete the following declaration. I declare that I have agreed to represent the executor(s) for the estate, that I am authorized to receive tax information regarding the estate, and I am (mark an X in all that apply): an attorney a certified public accountant an enrolled agent a public accountant enrolled with the NYS Education Department. Then the attorney or authorized representative enters the Signature of attorney or authorized representative, the Date and the Email address of attorney.
Under penalties of perjury, the executor(s) for this estate declare that they have examined this return, including accompanying schedules and statements, and to the best of their knowledge and belief, it is true, correct, and complete. The executor(s) for this estate authorize the person, if any, named as representative on this return to receive confidential tax information regarding this estate.
Signature of executor, Date, Signature of co-executor, Date.
Print name of preparer other than executor, Signature of preparer other than executor, Preparer's PTIN or SSN, Preparer's NYTPRIN; Address of preparer, City, State, ZIP code, Date, Email address of preparer.
More rules for Form ET-30
Decedent's last name, First name, Middle initial, Social Security number.
SSN or PTIN of attorney or authorized rep., Telephone number, Email address of attorney or authorized representative.
Social Security number of executor, Telephone number, Email address of executor.
Common questions about Form ET-30
Is there a deadline?
Use Form ET-30 to obtain release(s) of an estate tax lien if you are the appointed executor or administrator of the estate, or the duly authorized representative of the executor, and fewer than nine months have passed since the date of death.
Where do I file it?
Mail this form with Form(s) ET-117 to: NYS ESTATE TAX PROCESSING CENTER PO BOX 15167 ALBANY NY 12212-5167. Private delivery services - If not using U.S. Mail, see Publication 55, Designated Private Delivery Services.
Are there fees?
There is no fee for a release of lien.
When is this form not the right one?
A release of lien is not required if the real property was held jointly by the decedent and the surviving spouse as the only joint tenants. When to use forms other than Form ET-30: use Form ET-706, New York State Estate Tax Return, when the estate is required to file a New York State estate tax return. Either the estate has not obtained an extension of time to file the estate tax return, and more than nine months have passed since the date of death; or the estate obtained an extension of time to file the estate tax return, and more than 15 months have passed since the date of death (the extension has expired). Use Form ET-85, New York State Estate Tax Certification, when the estate is not required to file a New York State estate tax return, and either no executor or administrator has been appointed or more than nine months have passed since the date of death. Use it also when the estate is required to file a New York State estate tax return. Either fewer than nine months have passed since the date of death and an executor or administrator has not been appointed, or more than nine but less than 15 months have passed and an extension of time to file the estate tax return has been granted. If the estate is subject to tax, an estimated payment may be required when Form ET-85 is filed.
Sources
[1] Form ET-30 (1/24), Application for Release(s) Of Estate Tax Lien, New York State Department of Taxation and Finance (the Official source link on this page).