

Financial Planning Worksheet for Career Transition at a glance
What it is: Financial Planning Worksheet for Career Transition has a Statement of Net Worth, Monthly Income, Monthly Savings And Living Expenses, Indebtedness and an Action Plan.
A filled-in Financial Planning Worksheet for Career Transition example: a service member fills in the net worth page
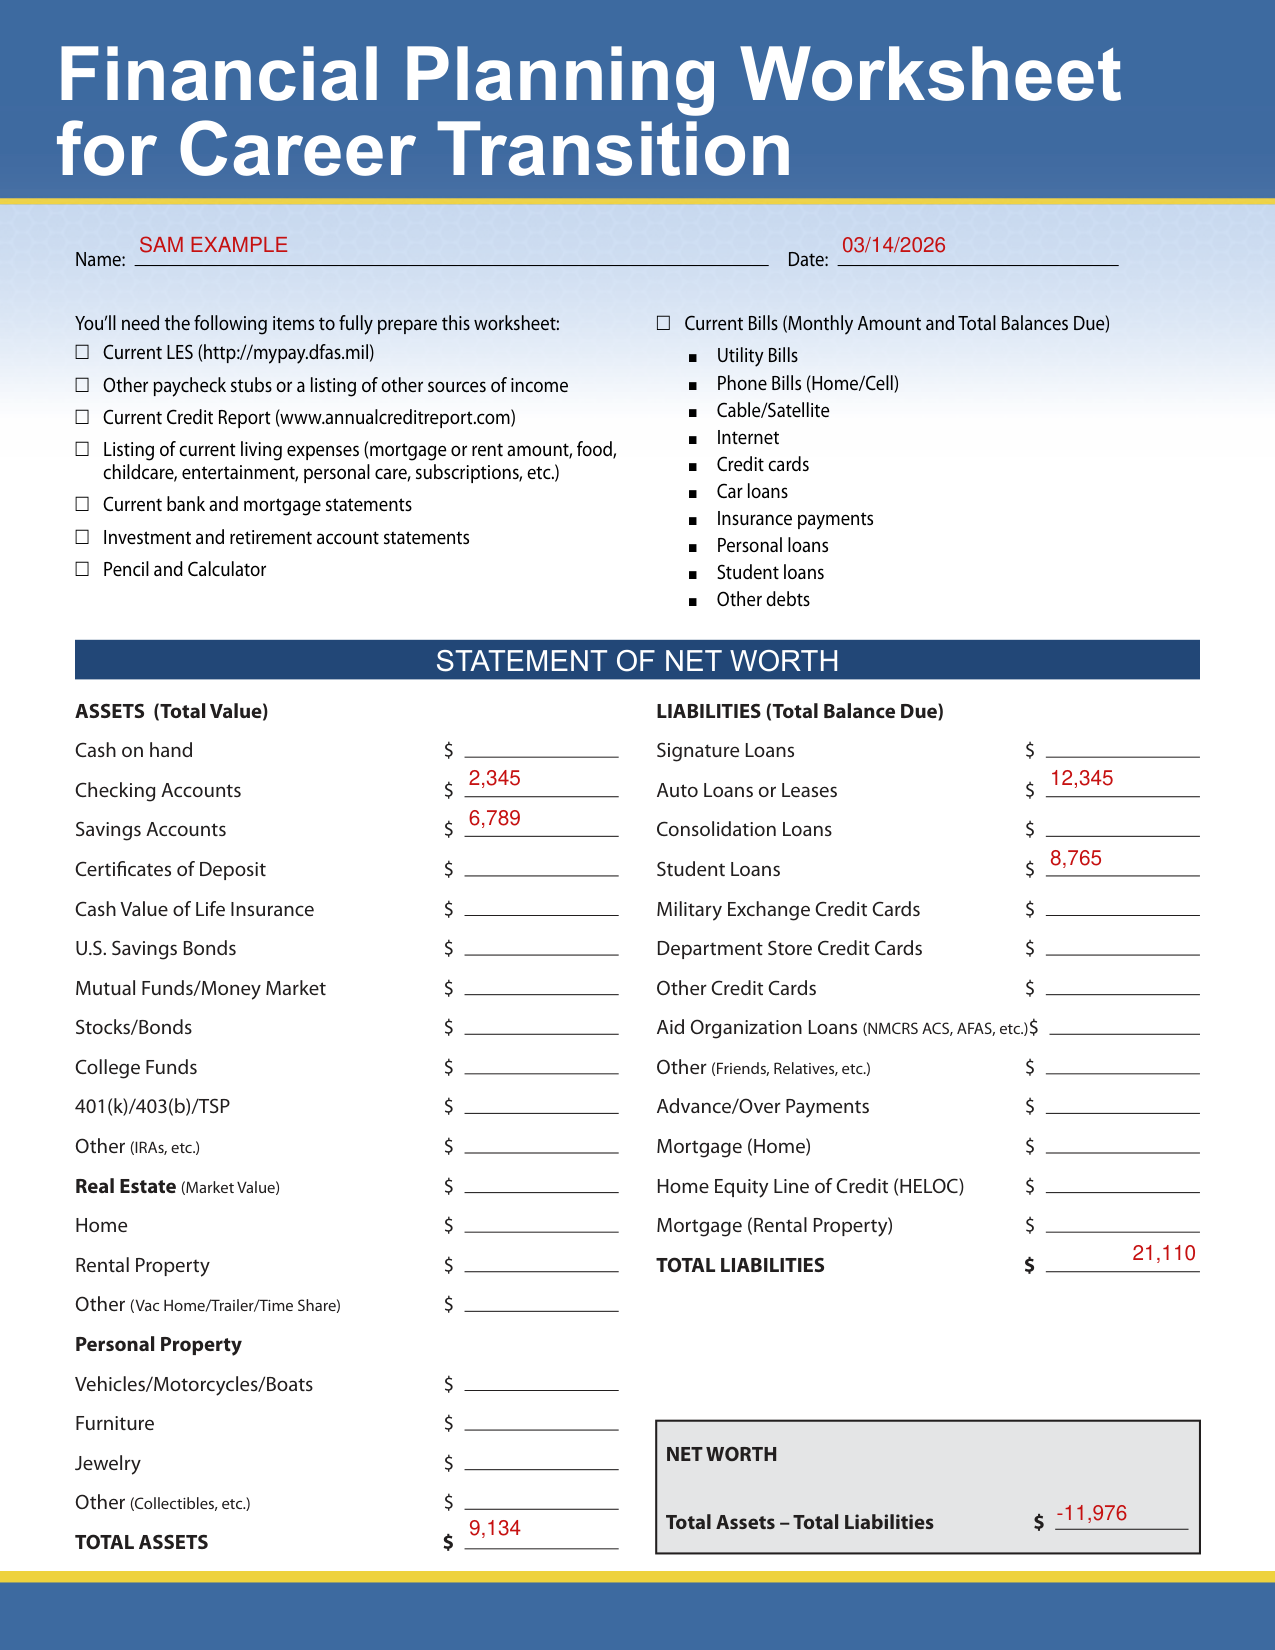
How to fill out Financial Planning Worksheet for Career Transition, box by box
Statement of net worth
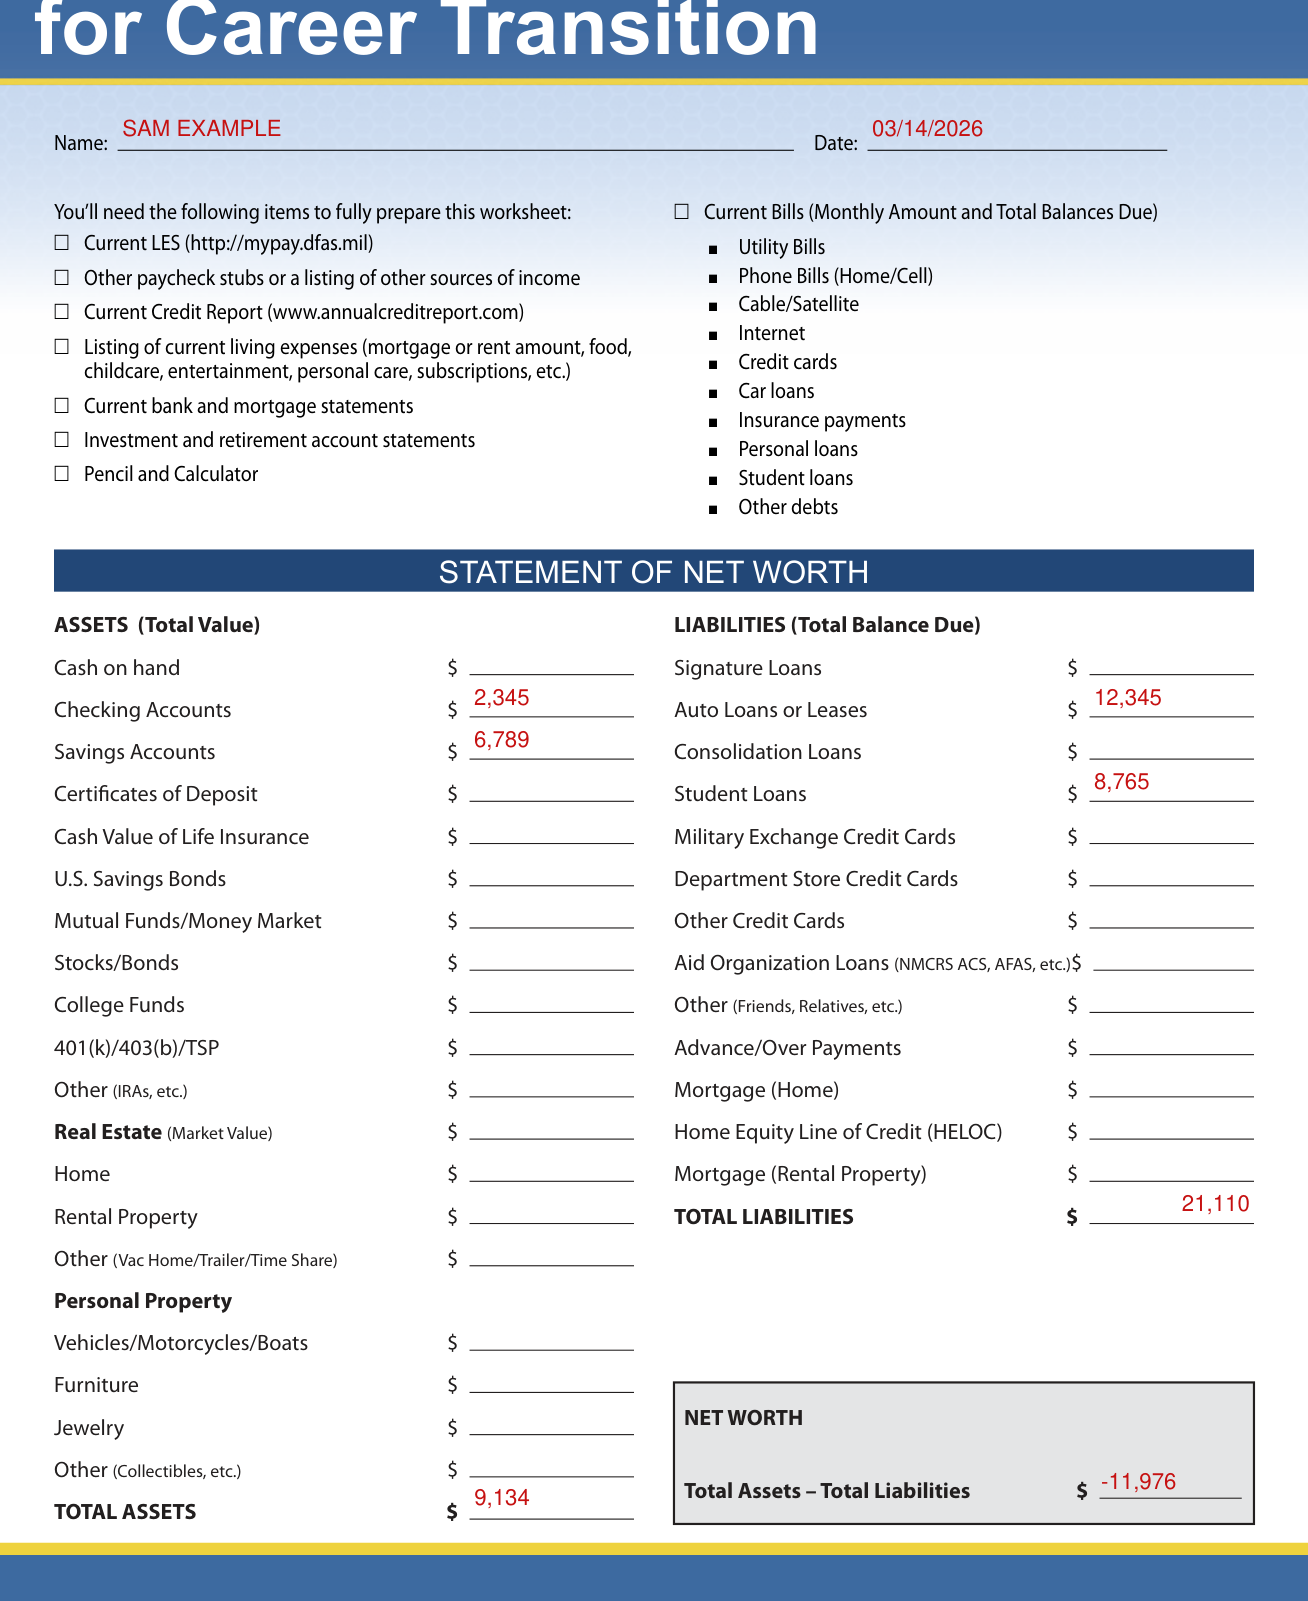
Under STATEMENT OF NET WORTH, enter ASSETS (Total Value) and LIABILITIES (Total Balance Due).
ASSETS lists Cash on hand, Checking Accounts, Savings Accounts, Certificates of Deposit, Cash Value of Life Insurance, U.S. Savings Bonds, Mutual Funds/Money Market, Stocks/Bonds, College Funds, 401(k)/403(b)/TSP and Other (IRAs, etc.) and TOTAL ASSETS.
Under Real Estate (Market Value), enter Home, Rental Property and Other (Vac Home/Trailer/Time Share).
Under Personal Property, enter Vehicles/Motorcycles/Boats, Furniture, Jewelry and Other (Collectibles, etc.).
LIABILITIES lists Signature Loans, Auto Loans or Leases, Consolidation Loans, Student Loans, Military Exchange Credit Cards, Department Store Credit Cards, Other Credit Cards, Aid Organization Loans (NMCRS ACS, AFAS, etc.), Other (Friends, Relatives, etc.), Advance/Over Payments, Mortgage (Home), Home Equity Line of Credit (HELOC) and Mortgage (Rental Property) and TOTAL LIABILITIES.
NET WORTH is Total Assets - Total Liabilities.
More rules for Financial Planning Worksheet for Career Transition
You'll need the following items to fully prepare this worksheet: Current Bills (Monthly Amount and Total Balances Due), Current LES (http://mypay.dfas.mil), other paycheck stubs or a listing of other sources of income and Current Credit Report (www.annualcreditreport.com).
Also, a listing of current living expenses (mortgage or rent amount, food, childcare, entertainment, personal care, subscriptions, etc.), current bank and mortgage statements, investment and retirement account statements, and a pencil and calculator.
The bills are Utility Bills, Phone Bills (Home/Cell), Cable/Satellite, Internet, Credit cards, Car loans, Insurance payments, Personal loans, Student loans and Other debts.
MONTHLY INCOME has ACTUAL, PROJECTED 1 and PROJECTED 2 for ENTITLEMENTS.
ENTITLEMENTS lists Base Pay, Basic Allowance for Housing, Overseas Housing Allowance, Basic Allowance for Subsistence (BAS), Family Separation Allowance (FSA), Special Pay, Other Taxable Pay and Other Non-taxable Pay (allowance) and TOTAL MILITARY COMPENSATION (A).
Note: Pay Entitlements are taxable. Allowance Entitlements are non-taxable.
DEDUCTIONS has ACTUAL, PROJECTED 1 and PROJECTED 2 for ALLOTMENT, Family SGLI (For Spouses), Servicemembers' Group Life Insurance (SGLI), Uniform Services TSP, MGIB, FITW Filing Status Actual, FICA (Social Security), FICA (Medicare), State Income Tax, AFRH (Armed Forces Retirement Home), TRICARE Dental Plan (TDP), Advance Payments and Overpayments and TOTAL DEDUCTIONS (B).
CALCULATE NET INCOME lists Service Member's Take Home Pay (A-B), Service Member's Other Earnings (less taxes), Spouse's Earnings (less taxes), Child Support/Alimony (Received/Income) and Other Income (e.g., SSI, Rental Income) and MONTHLY NET INCOME.
SAVINGS has ACTUAL, PROJECTED 1 and PROJECTED 2 for Emergency Fund (1-3 months), Reserve Fund, "Goal-Getter" Fund and Investments/IRAs/TSP/etc. and TOTAL SAVINGS AND INVESTMENTS.
Living Expenses has Actual, Projected 1 and Projected 2 for Housing, Food, Utilities, Child Care, Automobile, Clothing, Insurance, Healthcare, Education, Contributions, Leisure, Personal, Gifts, Pet Care and Miscellaneous and Total Monthly Living Expenses.
Under CLOTHING, the Living Expenses list has Purchases ($50 monthly per person) (checked November 11, 2026).
INDEBTEDNESS has CREDITOR, PURPOSE, BALANCE (From Page One), APR %, CURRENT MONTHLY PAYMENT, PROJECTED 1, PROJECTED 2 and TOTAL.
SUMMARY has ACTUAL, PROJECTED 1 and PROJECTED 2: NET INCOME (Bottom of Page 2), SAVINGS & INVESTMENTS (Page 3) -, LIVING EXPENSES (Page 3) -, AMOUNT LEFT TO PAY DEBTS =, TOTAL MONTHLY DEBT PAYMENTS (Page 4) - and SURPLUS OR DEFICIT =.
DEBT-TO-INCOME RATIO: (Total Monthly Debt Payments ÷ Net Income x 100 = Debt-to-Income Ratio).
The Action Plan has Increase Income, Decrease Living Expenses, Decrease Indebtedness and Additional Information Needed.
Under TRANSITION GOALS, enter the GOAL, COST, DATE WANTED and MONTHLY SAVINGS TO REACH GOAL.
Sources
[1] Financial Planning Worksheet for Career Transition (served file; no issuer file found) (the Official source link on this page).
