
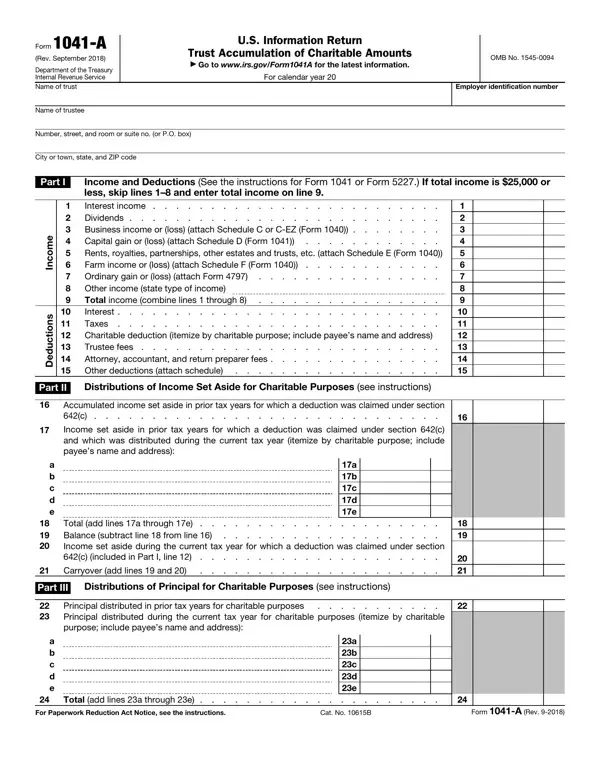

Form 1041-A at a glance
What it is: Form 1041-A, the U.S. Information Return Trust Accumulation of Charitable Amounts, reports the charitable information required by section 6034 and the related regulations.
Who signs: Form 1041-A must be signed by the trustee or by an authorized representative.
The trustee must file Form 1041-A for a trust that claims a charitable or other deduction under section 642(c) unless an exception applies.
A filled-in Form 1041-A example: a small charitable trust files for 2025
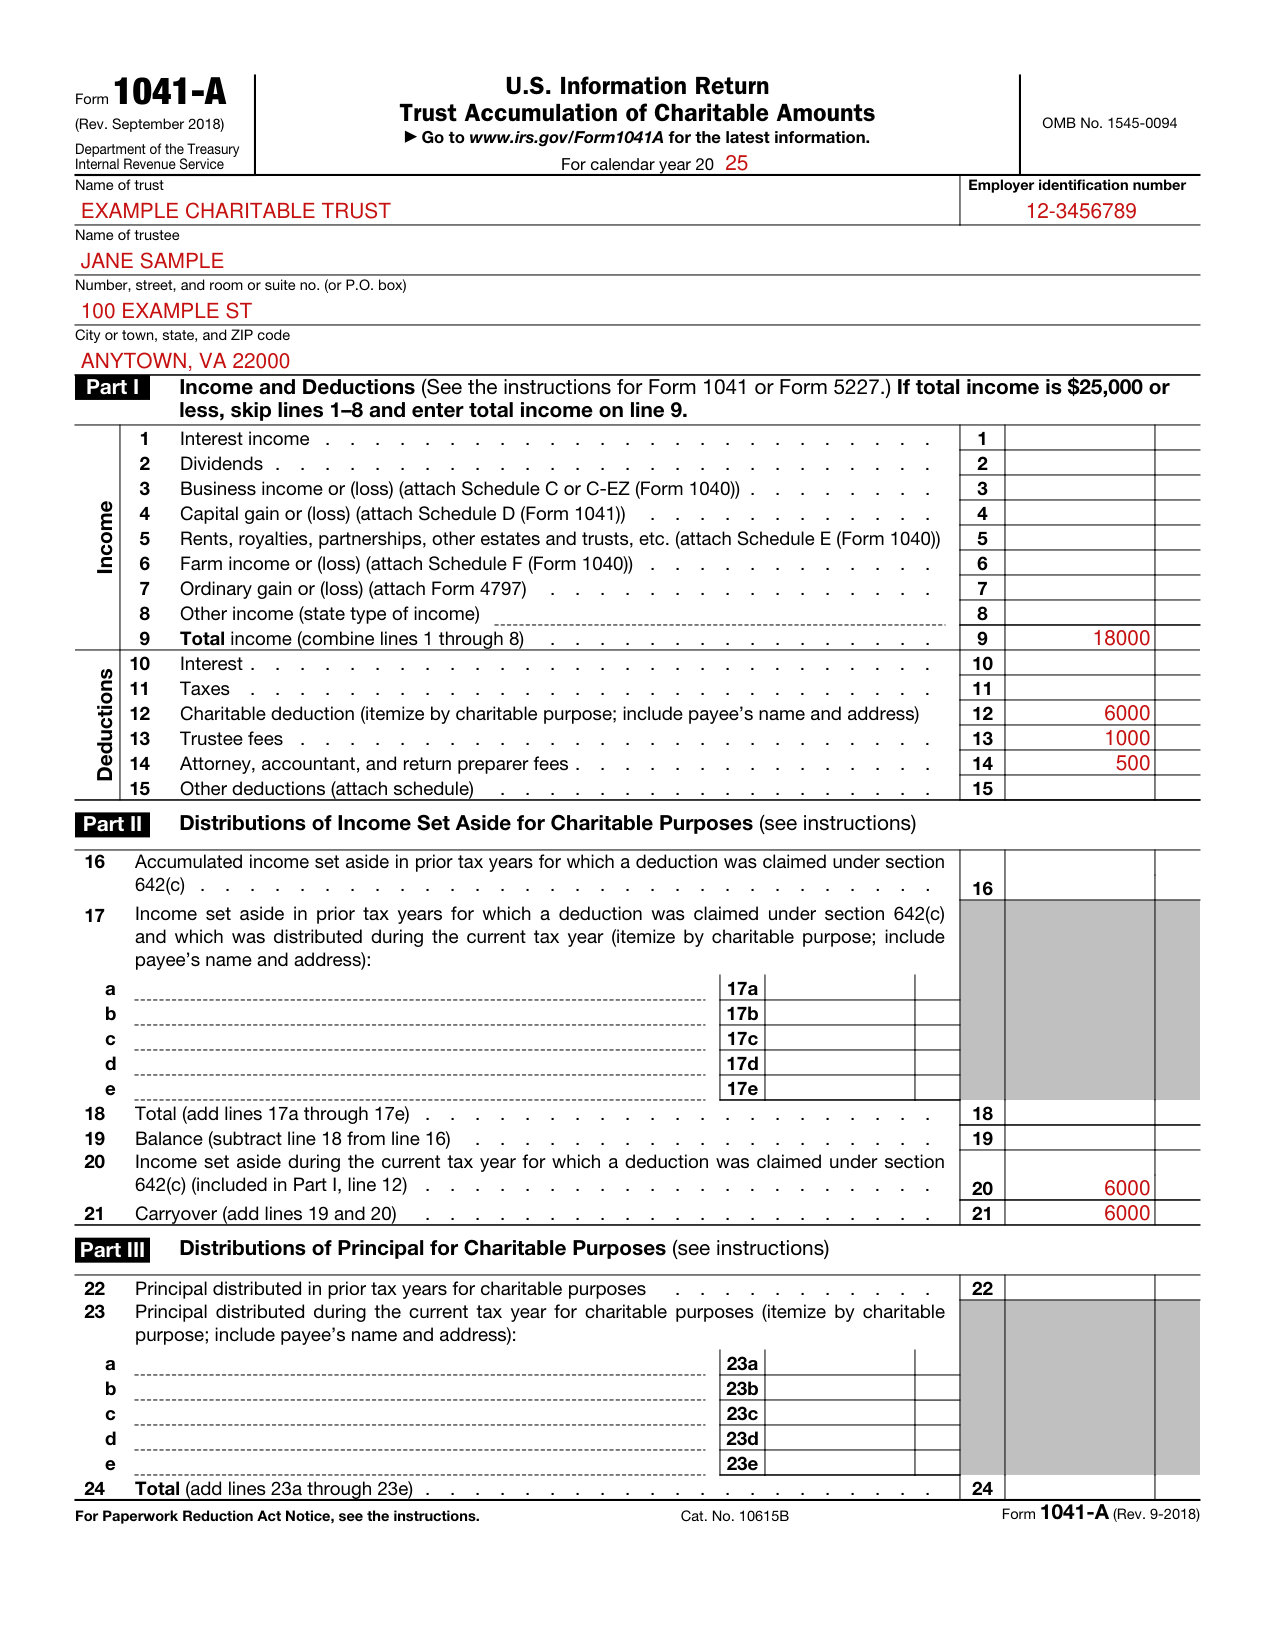
How to fill out Form 1041-A, box by box
Trust, trustee and calendar year
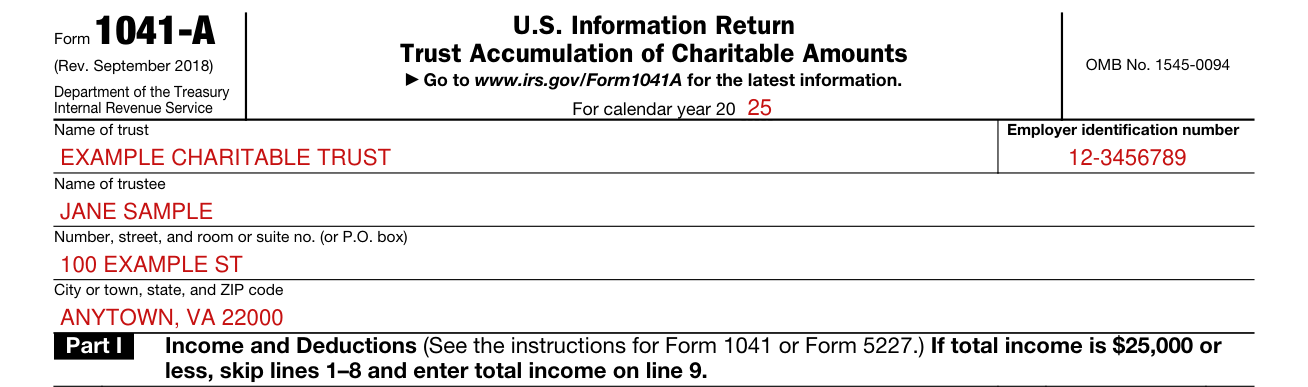
Enter the calendar year after 20, the Name of trust, the Employer identification number, the Name of trustee, the Number, street, and room or suite no. (or P.O. box), and the City or town, state, and ZIP code.
Part I Income and Deductions
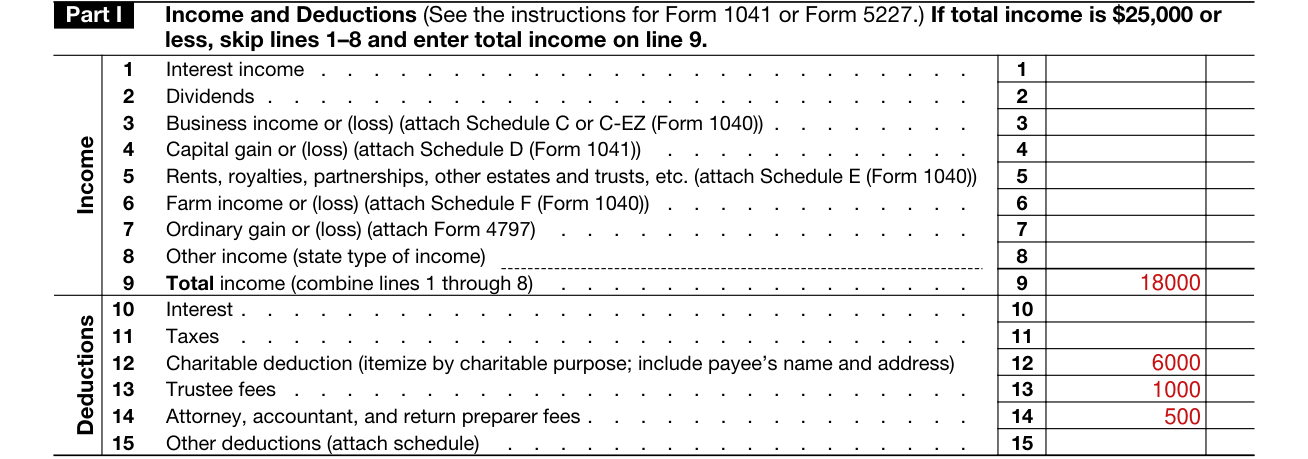
If total income is $25,000 or less, skip lines 1-8 and enter total income on line 9 (checked November 9, 2026).
On line 8, state the type of other income. On line 9, combine lines 1 through 8 for total income.
On line 12, itemize the charitable deduction by charitable purpose and include the payee's name and address. On line 15, attach a schedule for other deductions.
Part II Distributions of Income Set Aside for Charitable Purposes
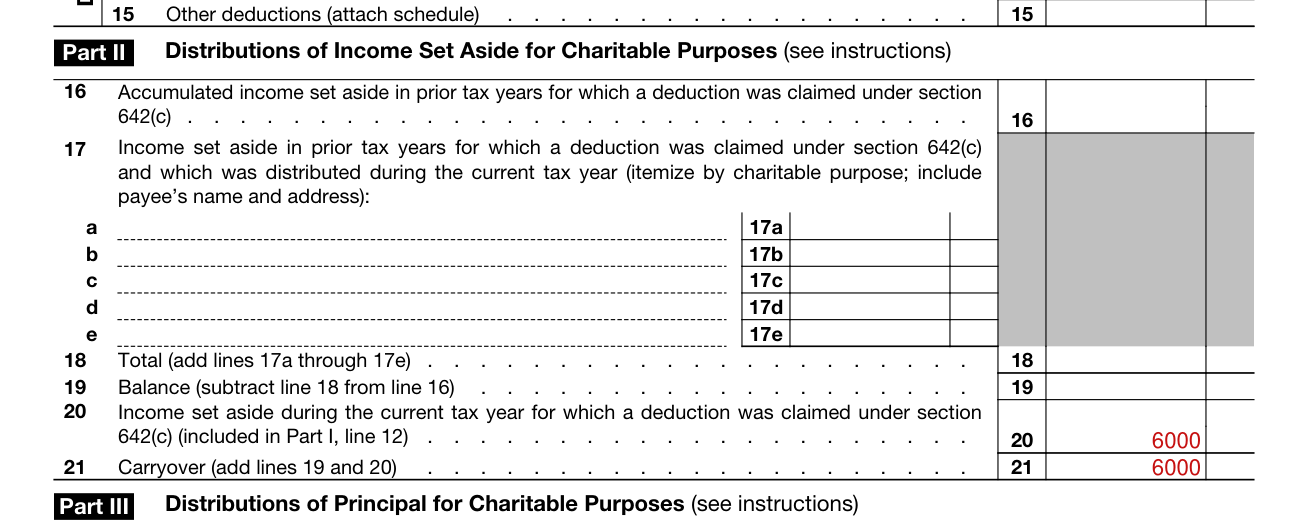
On line 16, enter accumulated income set aside in prior tax years for which a deduction was claimed under section 642(c). On lines 17a to 17e, itemize by charitable purpose, with the payee's name and address, the income set aside in prior tax years for which a deduction was claimed under section 642(c) and which was distributed during the current tax year.
On lines 17a to 17e, provide a listing in sufficient detail for each class of activity for which a disbursement was made, and a charitable deduction under section 642(c) was taken. Do not merely enter the category (that is, religious, charitable, scientific, literary, or educational), but also enter the purpose of the deduction.
On line 18, add lines 17a through 17e. On line 19, subtract line 18 from line 16. On line 20, enter income set aside during the current tax year for which a deduction was claimed under section 642(c) (included in Part I, line 12). On line 21, add lines 19 and 20.
Part III Distributions of Principal for Charitable Purposes
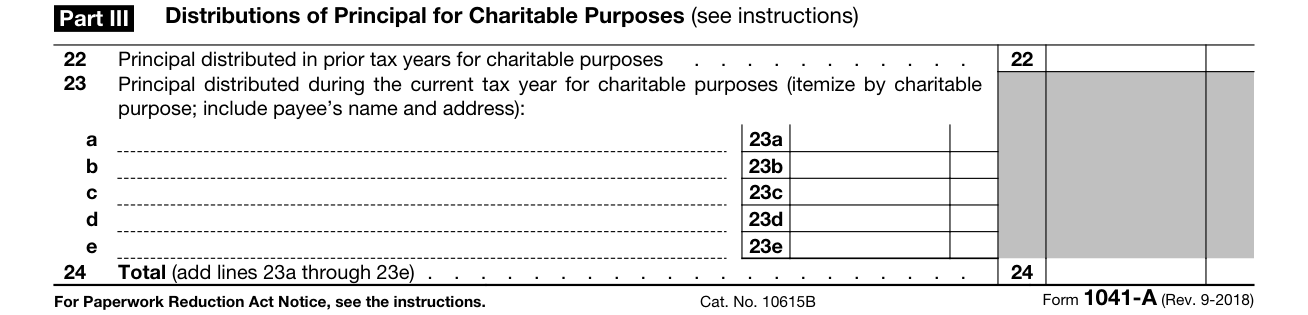
On line 22, enter principal distributed in prior tax years for charitable purposes. On lines 23a to 23e, itemize by charitable purpose, with the payee's name and address, the principal distributed during the current tax year for charitable purposes. On line 24, add lines 23a through 23e.
Part IV Balance Sheets
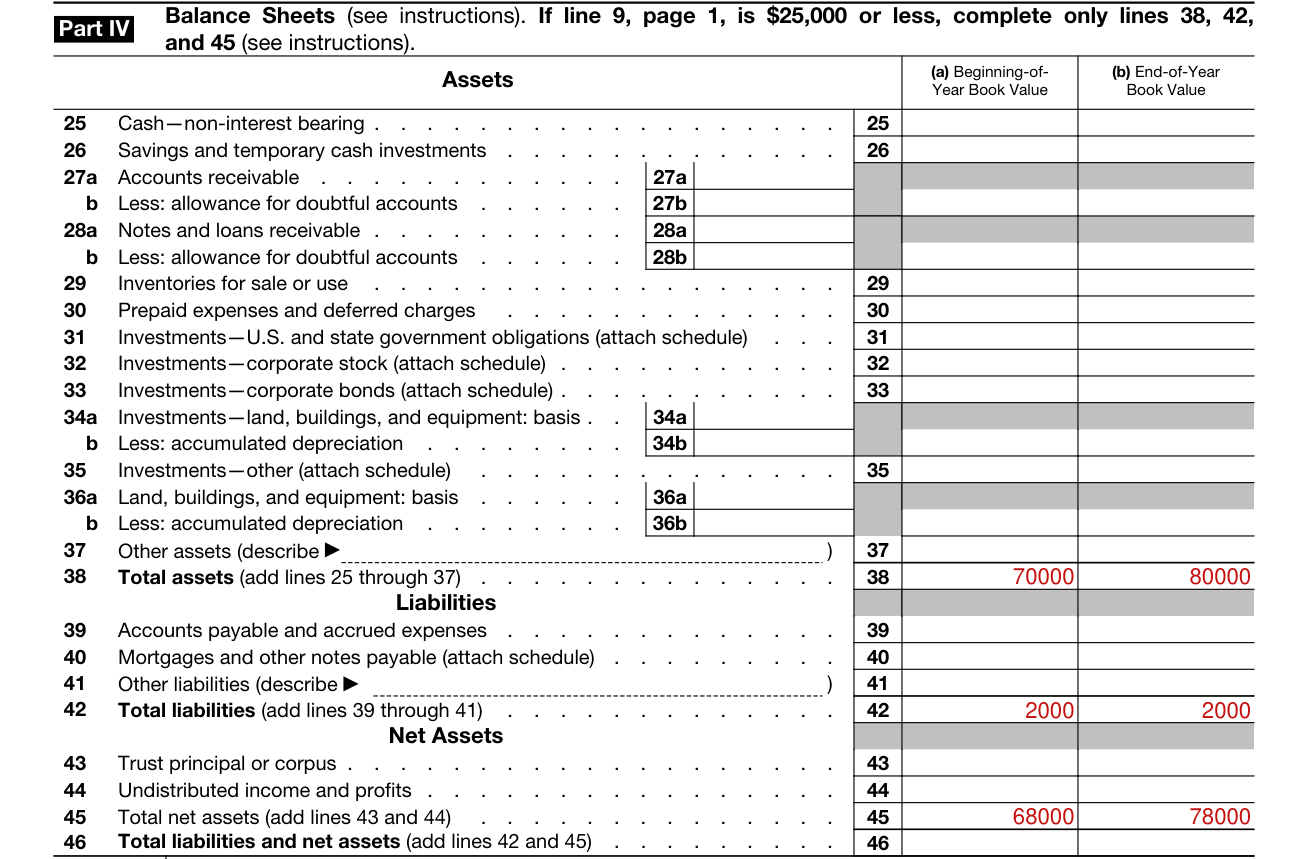
If line 9, page 1, is $25,000 or less, complete only lines 38, 42, and 45 (checked November 9, 2026).
Complete the balance sheets using the accounting method the trust uses in keeping its books and records. All filers must complete columns (a) and (b).
On line 38, add lines 25 through 37 for total assets. On line 42, add lines 39 through 41 for total liabilities. On line 45, add lines 43 and 44 for total net assets.
Signing the return
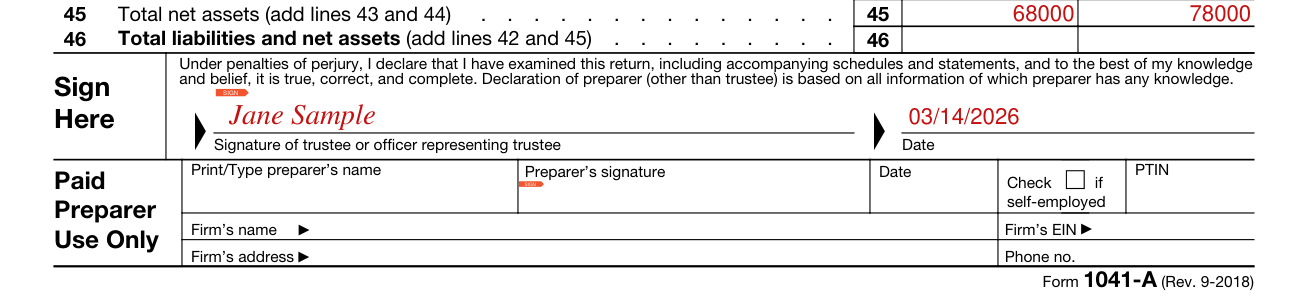
Sign in the Signature of trustee or officer representing trustee box and enter the Date.
Under penalties of perjury, I declare that I have examined this return, including accompanying schedules and statements, and to the best of my knowledge and belief, it is true, correct, and complete. Declaration of preparer (other than trustee) is based on all information of which preparer has any knowledge.
If you, as trustee (or an employee or officer of the trust), fill in Form 1041-A, the Paid Preparer space should be left blank. If someone prepares this return without charge, that person shouldn't sign the return. Generally, anyone who is paid to prepare a tax return must sign the return and fill in the other blanks in the Paid Preparer Use Only area of the return.
More rules for Form 1041-A
You may show the money items on the return and accompanying schedules as whole-dollar amounts. To do so, drop amounts less than 50 cents and increase any amounts from 50 to 99 cents to the next dollar.
If your situation is different
The trust is one of the exceptions to filing
The trustee doesn't file Form 1041-A for a trust that is required to distribute currently to the beneficiaries all the income for the tax year determined under section 643(b) and related regulations.
The trustee doesn't file Form 1041-A for: a charitable trust described in section 4947(a)(1); or electing small business trusts (ESBTs) described in section 641(c).
Split-interest trusts as described in section 4947(a)(2) don't file Form 1041-A, for tax years beginning after 2006. These types of trusts file Form 5227, Split-Interest Trust Information Return, which meets the section 6034 filing requirements.
You are filing an amended return
If you are filing an amended Form 1041-A, you must complete the entire return, not just the new or corrected information. Enter “Amended Return” across the top of the amended Form 1041-A. The trustee may file an amended return at any time to change or add to the information reported on a previously filed return for the same period.
You need more space
If you need more space, attach separate sheets showing the same information in the same order as on the printed forms. Show the totals on the printed forms. Enter the trust's employer identification number (EIN) on each sheet.
Where To File and Penalties
File Form 1041-A with the Department of the Treasury, Internal Revenue Service Center, Ogden, UT 84201-0027. Section 6652(c)(2) provides for separate penalties of $10 a day, up to a maximum of $5,000, against both the trust and the trustee for not filing Form 1041-A on time, unless there is reasonable cause (checked November 9, 2026). The law also provides penalties for filing a false or fraudulent return.
Extension of Time To File
The trustee may obtain an automatic extension of time to file Form 1041-A by filing Form 8868, Application for Automatic Extension of Time To File an Exempt Organization Return, on or before the original due date of Form 1041-A.
Common questions about Form 1041-A
Is there a deadline?
File Form 1041-A by April 15 following the close of the calendar year. If the due date falls on a Saturday, Sunday, or legal holiday, file on the next business day.
Sources
[1] Form 1041-A (Rev. September 2018), U.S. Information Return Trust Accumulation of Charitable Amounts, Department of the Treasury, Internal Revenue Service (the Official source link on this page).