File Form 1138 after the start of the tax year of the expected NOL but before the tax of the preceding tax year is required to be paid.
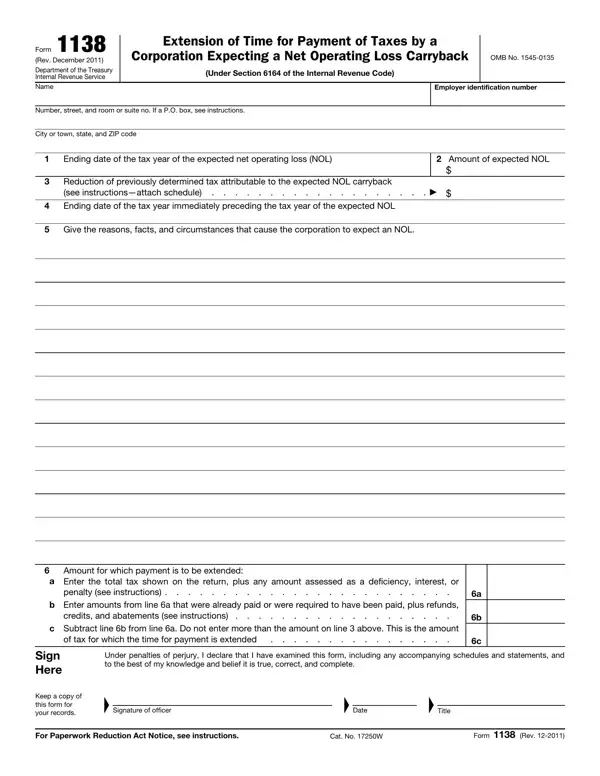
Who files: a corporation that expects to incur an NOL in the current tax year that can be carried back to its preceding tax year can file Form 1138.
Postponed tax: the payment of tax that can be postponed cannot exceed the expected overpayment from the carryback of the NOL.
Where to file: generally, file Form 1138 with the Internal Revenue Service Center where the corporation files its income tax return.
When not to file: do not file this form if all the required payments have been paid or were required to have been paid.
Interest: interest is charged on postponed amounts from the dates that the payments would normally be due.
| Question | Answer |
|---|---|
| Form Name | Form 1138 |
| Form Length | 2 pages |
| Fillable? | Yes |
| Fillable fields | 36 |
| Avg. time to fill out | 6 min |
| Edition | Rev. November 2018 |
| Issuing agency | Internal Revenue Service |
| Matches the agency's file | Yes, checked October 4, 2026 |
| Other names | 1138, Form 1138, IRS 1138, Extension of Time for Payment of Taxes by a Corporation Expecting a Net Operating Loss Carryback |
| Official source | Form 1138 (Rev 11-2018), Internal Revenue Service |
Form 1138 isn’t the one you’re looking for?