

Form FTB 3805V at a glance
What it is: Form 3805V is the 2025 Net Operating Loss (NOL) Computation and NOL and Disaster Loss Limitations for Individuals, Estates, and Trusts; Part I is the Computation of Current Year NOL.
Where and when to file: Attach to your California tax return.
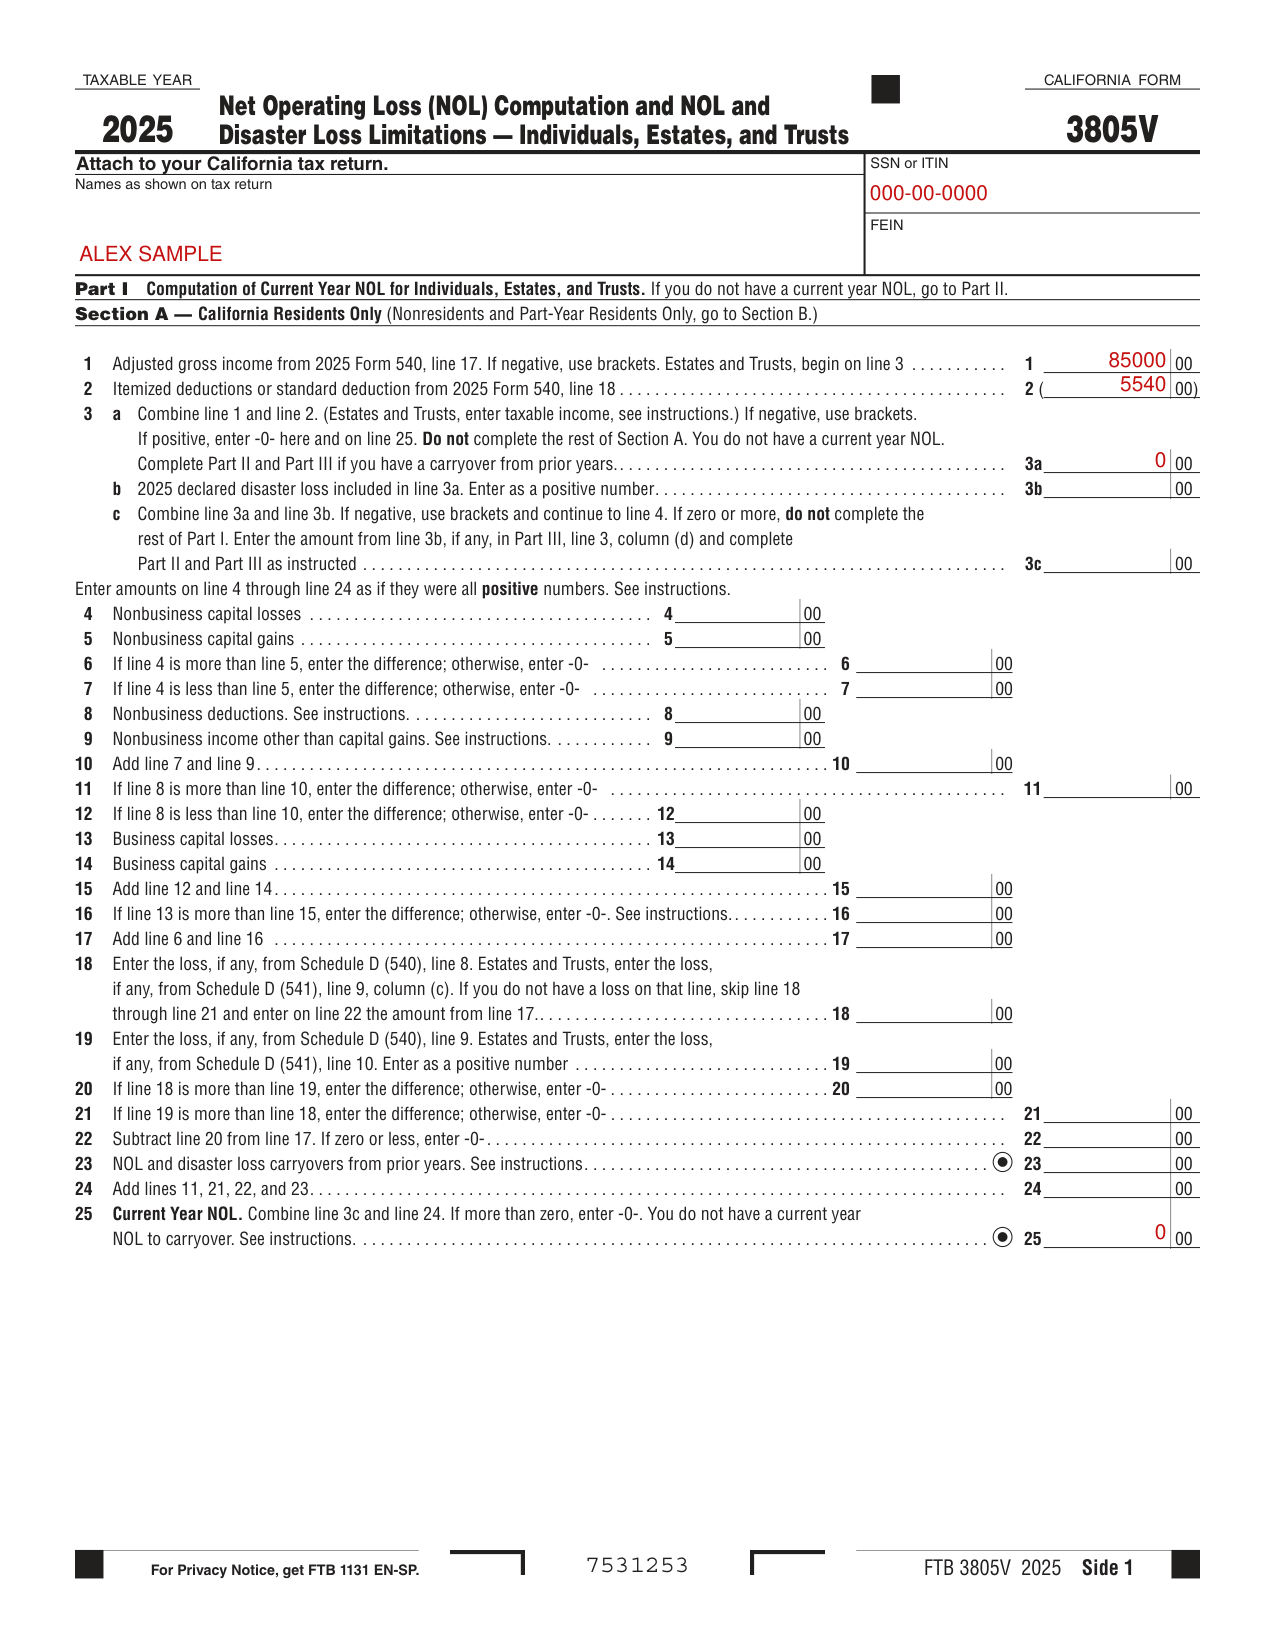
A filled-in Form FTB 3805V example: a California resident whose line 3a is positive
How to fill out Form FTB 3805V, box by box
Names as shown on tax return

Write the names as shown on tax return.
SSN or ITIN

Enter your SSN or ITIN.
FEIN

Enter the FEIN.
Section A, California Residents Only, line 1 to line 3a and line 25
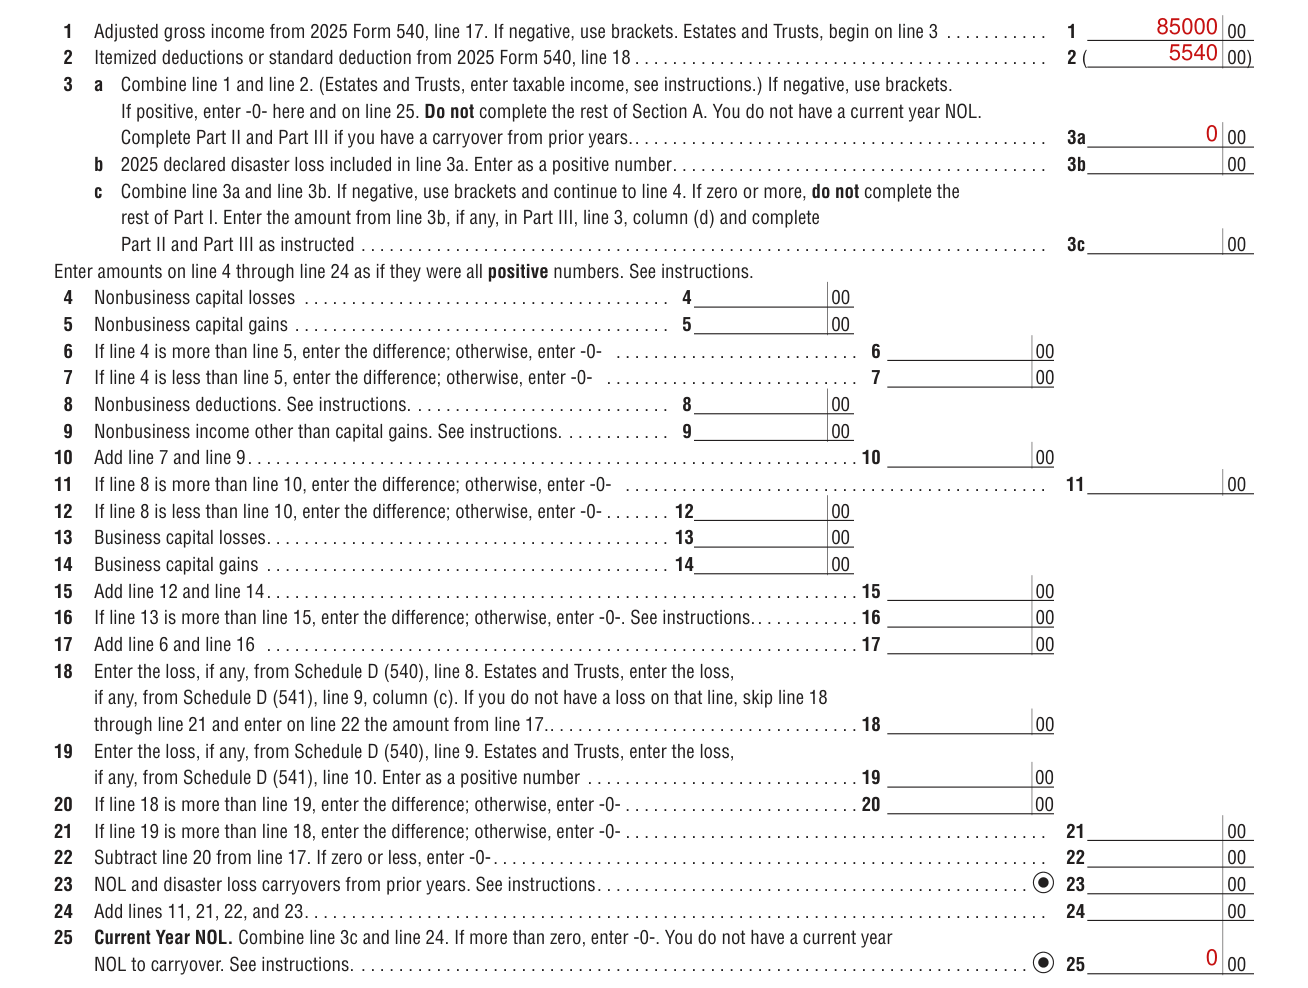
Section A is for California Residents Only; Nonresidents and Part-Year Residents Only, go to Section B.
If you do not have a current year NOL, go to Part II.
On line 1, enter the Adjusted gross income from 2025 Form 540, line 17. If negative, use brackets. Estates and Trusts, begin on line 3.
On line 2, enter the Itemized deductions or standard deduction from 2025 Form 540, line 18.
On line 3a, combine line 1 and line 2 (Estates and Trusts, enter taxable income, see instructions); if negative, use brackets; if positive, enter 0 here on line 3a and on line 25, do not complete the rest of Section A, and you do not have a current year NOL. Complete Part II and Part III if you have a carryover from prior years.
On line 25, combine line 3c and line 24. If more than zero, enter 0. You do not have a current year NOL to carryover. See instructions.
Section A, line 3b through line 24
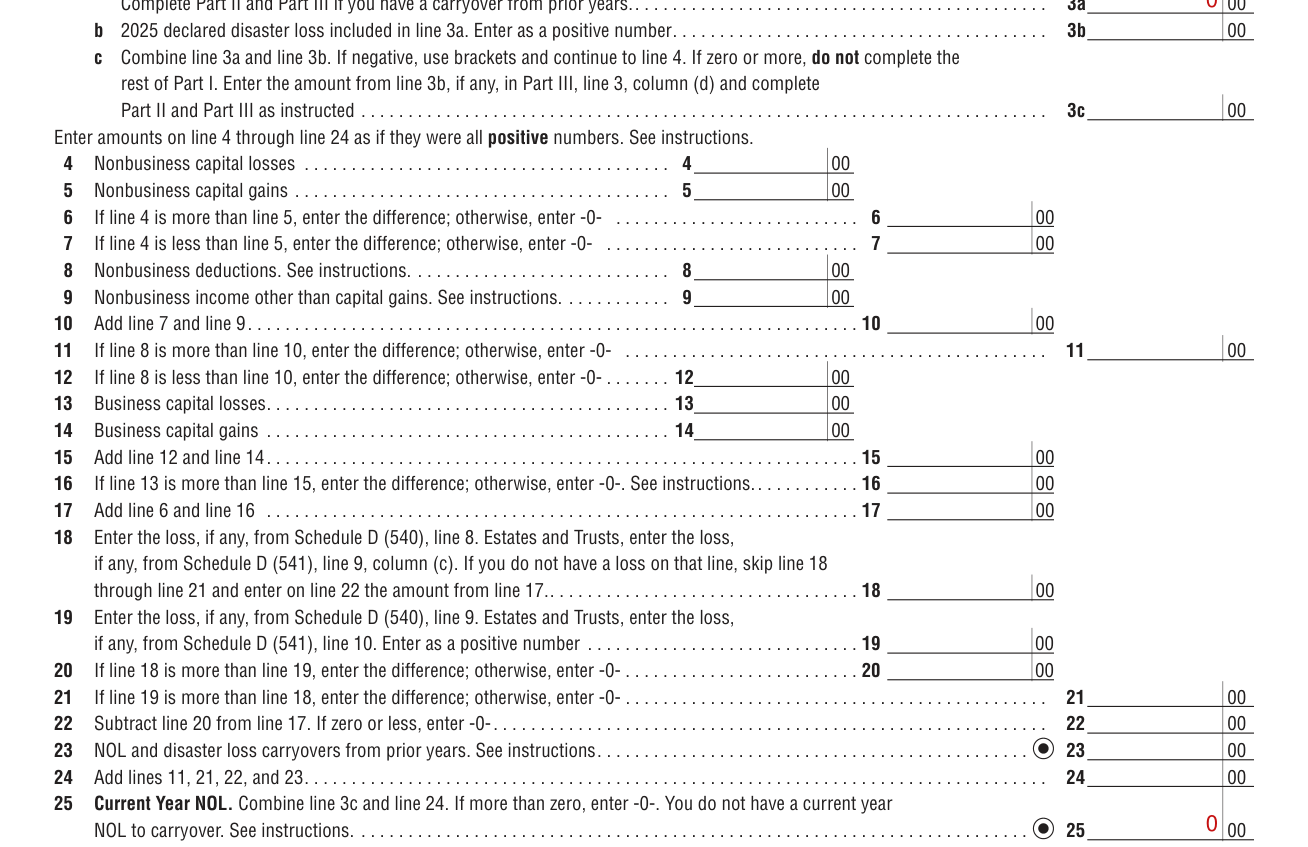
On line 3b, enter the 2025 declared disaster loss included in line 3a. Enter as a positive number.
On line 3c, combine line 3a and line 3b. If negative, use brackets and continue to line 4.
If line 3c is zero or more, do not complete the rest of Part I. Enter the amount from line 3b, if any, in Part III, line 3, column (d) and complete Part II and Part III as instructed.
Enter amounts on line 4 through line 24 as if they were all positive numbers. See instructions.
Line 4 is Nonbusiness capital losses and line 5 is Nonbusiness capital gains.
On line 6, if line 4 is more than line 5, enter the difference; otherwise, enter 0.
On line 7, if line 4 is less than line 5, enter the difference; otherwise, enter 0.
Line 8 is Nonbusiness deductions and line 9 is Nonbusiness income other than capital gains. See instructions.
On line 10, add line 7 and line 9.
On line 11, if line 8 is more than line 10, enter the difference; otherwise, enter 0.
On line 12, if line 8 is less than line 10, enter the difference; otherwise, enter 0.
Line 13 is Business capital losses and line 14 is Business capital gains.
On line 15, add line 12 and line 14.
On line 16, if line 13 is more than line 15, enter the difference; otherwise, enter 0. See instructions.
On line 17, add line 6 and line 16.
On line 18, enter the loss, if any, from Schedule D (540), line 8. Estates and Trusts, enter the loss, if any, from Schedule D (541), line 9, column (c). If you do not have a loss on that line, skip line 18 through line 21 and enter on line 22 the amount from line 17.
On line 19, enter the loss, if any, from Schedule D (540), line 9. Estates and Trusts, enter the loss, if any, from Schedule D (541), line 10. Enter as a positive number.
On line 20, if line 18 is more than line 19, enter the difference; otherwise, enter 0.
On line 21, if line 19 is more than line 18, enter the difference; otherwise, enter 0.
On line 22, subtract line 20 from line 17. If zero or less, enter 0.
On line 23, enter NOL and disaster loss carryovers from prior years. See instructions.
On line 24, add lines 11, 21, 22, and 23.
Section B, Nonresidents and Part-Year Residents Only
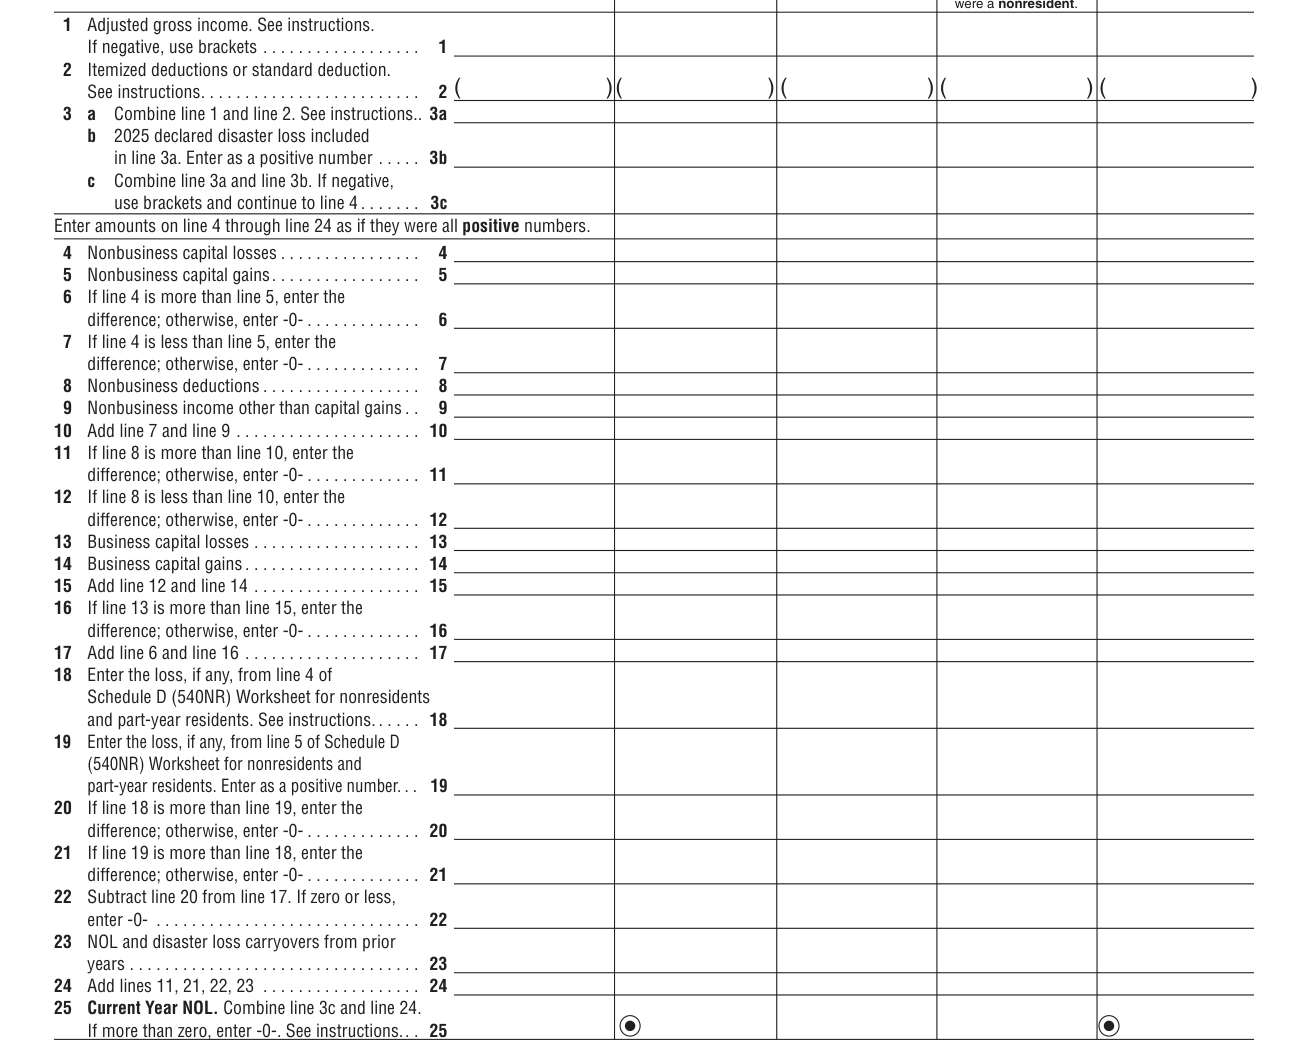
Section B is for Nonresidents and Part-Year Residents Only: Computation of Current Year California NOL.
In (a), enter total amounts as if you were a CA resident for entire year.
In (b), enter amounts earned or received from CA sources as if you were a nonresident for the entire year.
In (c), enter amounts earned or received during the portion of the year you were a CA resident.
In (d), enter amounts earned or received from CA sources during the portion of the year you were a nonresident.
Combine columns (c) and (d) for the Total in (e).
Part II, Determine 2025 Modified Taxable Income (MTI)
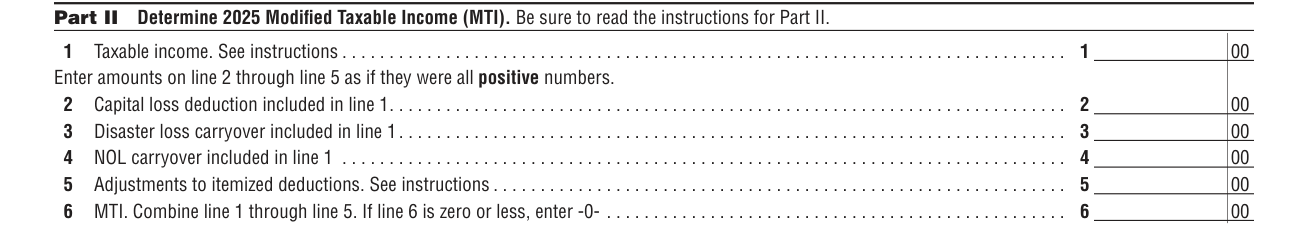
Determine 2025 Modified Taxable Income (MTI). Be sure to read the instructions for Part II.
On line 1, enter the taxable income. See instructions. Enter amounts on line 2 through line 5 as if they were all positive numbers.
On line 2, enter the capital loss deduction included in line 1, on line 3 the disaster loss carryover included in line 1, on line 4 the NOL carryover included in line 1 and on line 5 the adjustments to itemized deductions. See instructions.
On line 6, enter the MTI: combine line 1 through line 5. If line 6 is zero or less, enter 0.
Part III, NOL Carryover and Disaster Loss Carryover Limitations
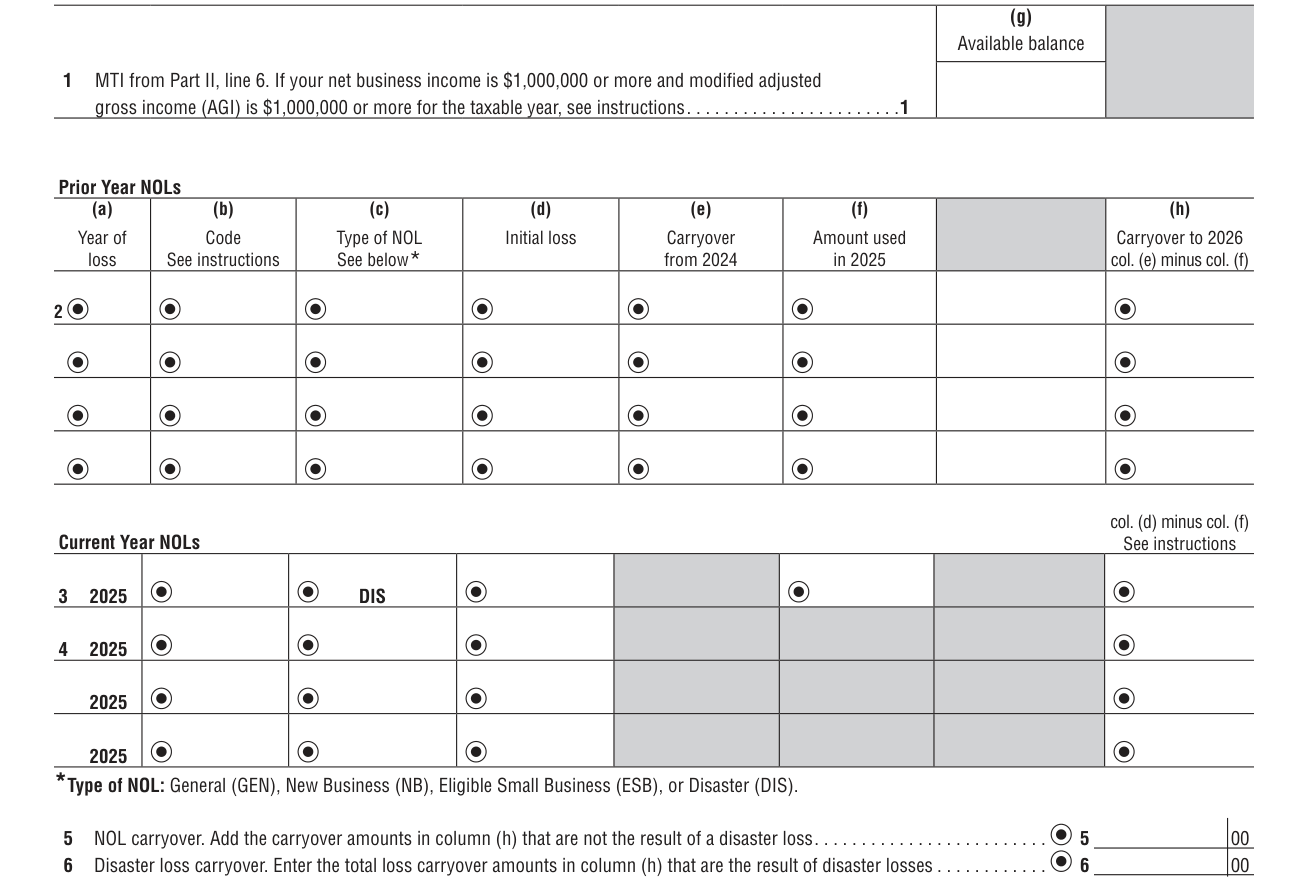
Part III is for NOL Carryover and Disaster Loss Carryover Limitations. See instructions.
On line 1, enter the MTI from Part II, line 6. If your net business income is $1,000,000 or more and modified adjusted gross income (AGI) is $1,000,000 or more for the taxable year, see instructions (checked November 8, 2026).
Under Prior Year NOLs, on line 2, enter the (a) Year of loss, (b) Code See instructions, (c) Type of NOL See below, (d) Initial loss, (e) Carryover from 2024, (f) Amount used in 2025, (g) Available balance and (h) Carryover to 2026 col. (e) minus col. (f).
*Type of NOL: General (GEN), New Business (NB), Eligible Small Business (ESB), or Disaster (DIS).
Under Current Year NOLs, line 3 is 2025 DIS and line 4 is 2025; on line 4, enter the (c) Type of NOL See below; enter col. (d) minus col. (f) See instructions.
On line 5, enter the NOL carryover: add the carryover amounts in column (h) that are not the result of a disaster loss. On line 6, enter the Disaster loss carryover: the total loss carryover amounts in column (h) that are the result of disaster losses.
Common questions about Form FTB 3805V
Where do I file it?
Attach to your California tax return.
Sources
[1] Form FTB 3805V (2025), Net Operating Loss (NOL) Computation and NOL and Disaster Loss Limitations, Individuals, Estates, and Trusts, California Franchise Tax Board (the Official source link on this page).