

Form 500-NOL at a glance
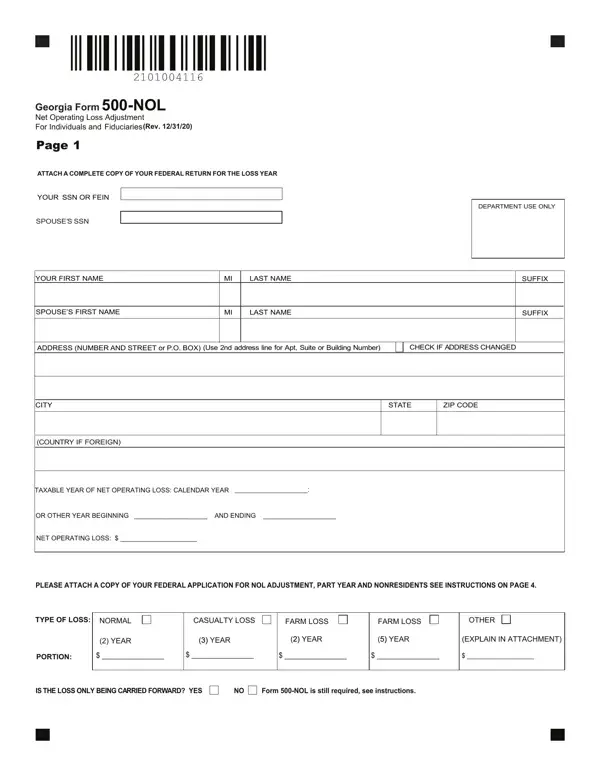
What it is: Form 500-NOL (Rev. 12/31/20), Net Operating Loss Adjustment For Individuals and Fiduciaries, is filed by an individual or fiduciary taxpayer that desires a refund of taxes afforded by carryback of a net operating loss.
Who signs: Sign on Taxpayer's Signature and, for a spouse, Taxpayer's Spouse Signature, and add the Date for each.
A filled-in Form 500-NOL example: a single filer reports a loss year
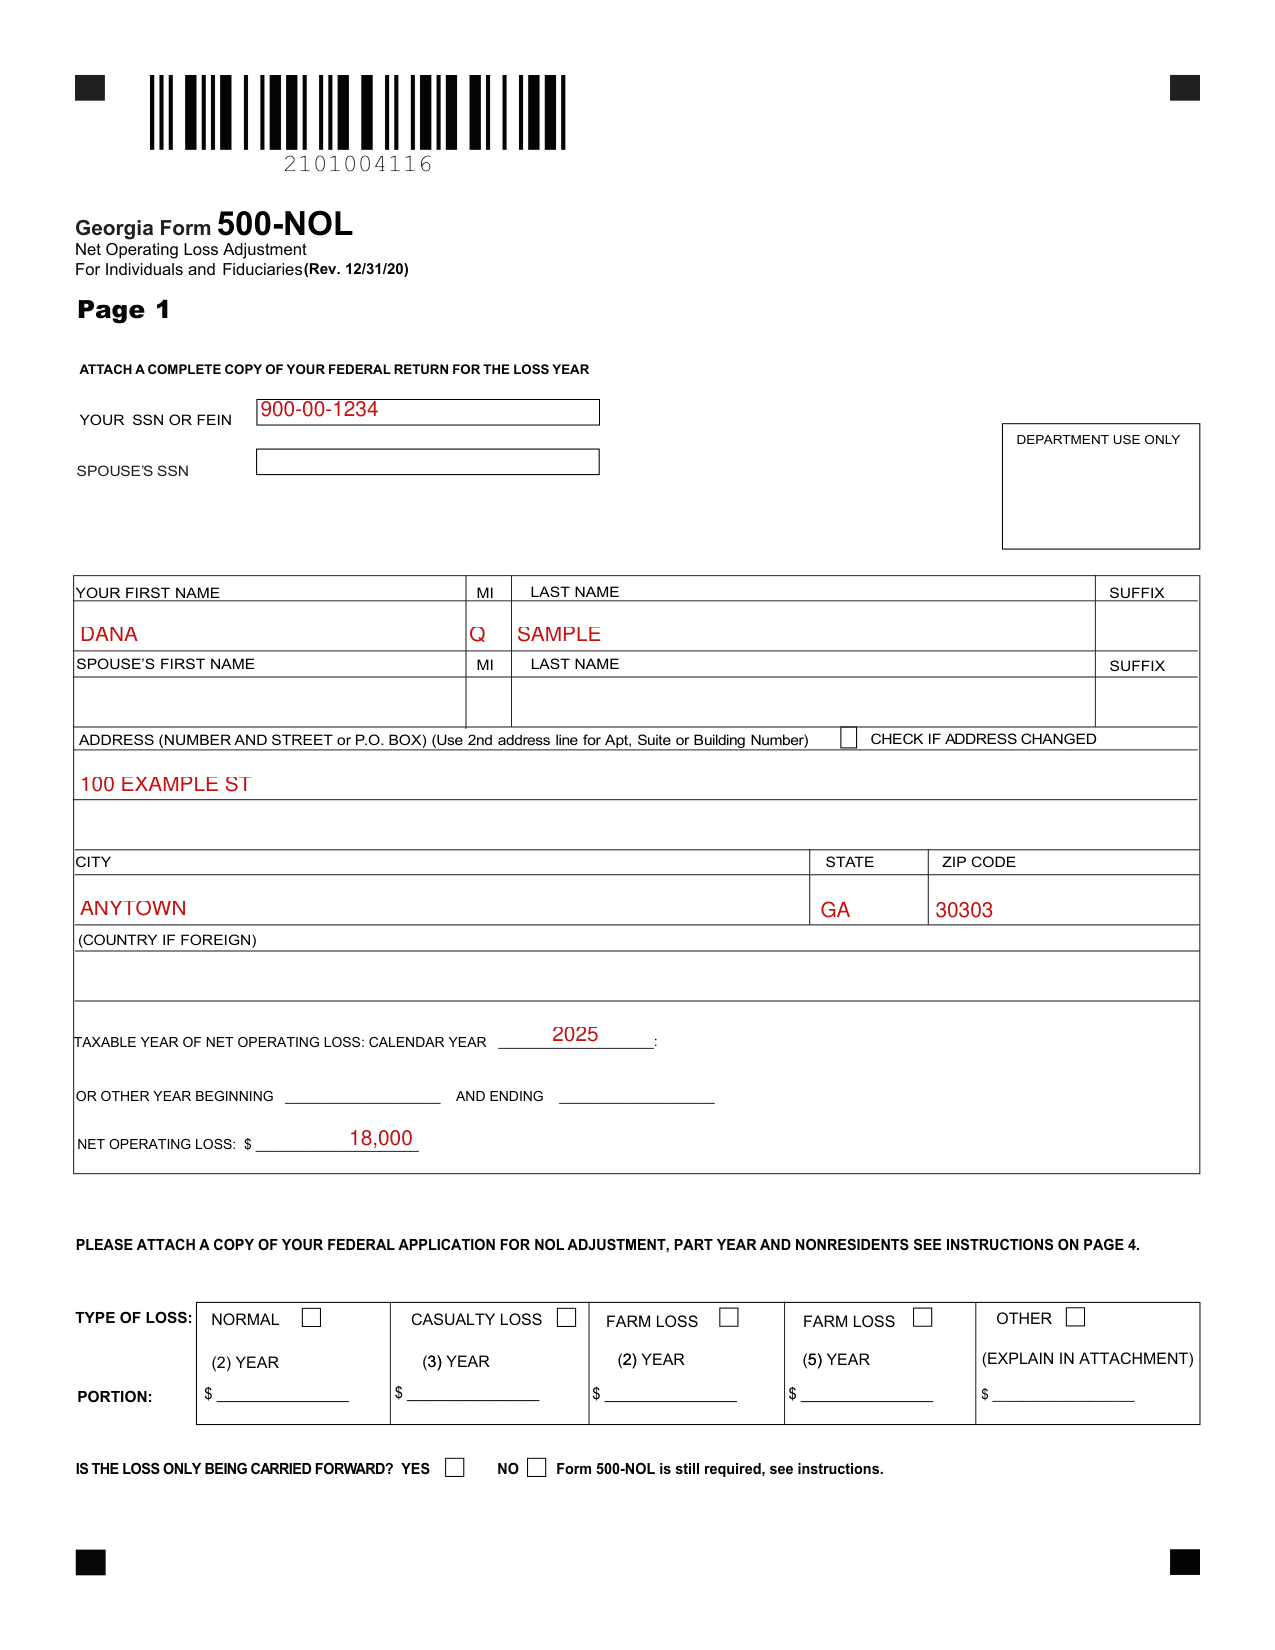
How to fill out Form 500-NOL, box by box
Your SSN or FEIN, name and address
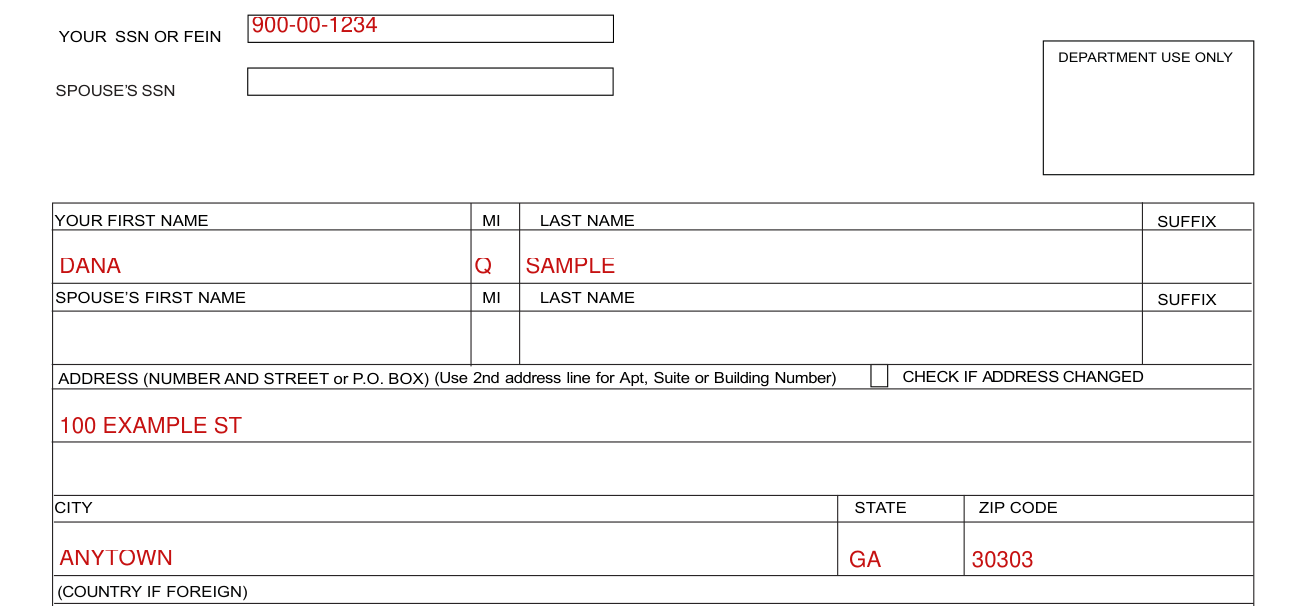
Enter YOUR SSN OR FEIN, then YOUR FIRST NAME, MI, LAST NAME and SUFFIX, then the ADDRESS (NUMBER AND STREET or P.O. BOX), and use the 2nd address line for Apt, Suite or Building Number. Also enter SPOUSE'S SSN and SPOUSE'S FIRST NAME, MI, LAST NAME and SUFFIX. Mark CHECK IF ADDRESS CHANGED if it applies.
Taxable year of net operating loss
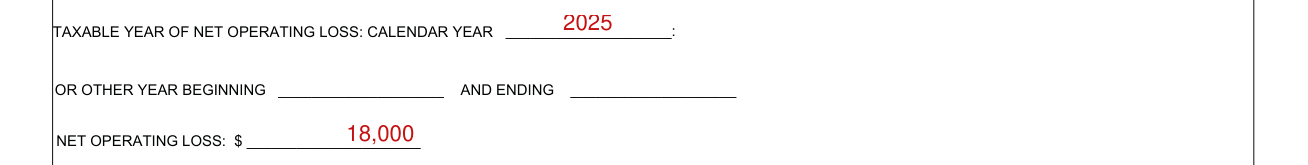
Enter the Taxable Year of Net Operating Loss, as a calendar year or as an other year beginning and ending, and the Net Operating Loss.
For losses incurred in taxable years beginning on or after January 1, 2018, the net operating loss cannot offset more than 80% of Georgia taxable net income.
Under penalty of perjury
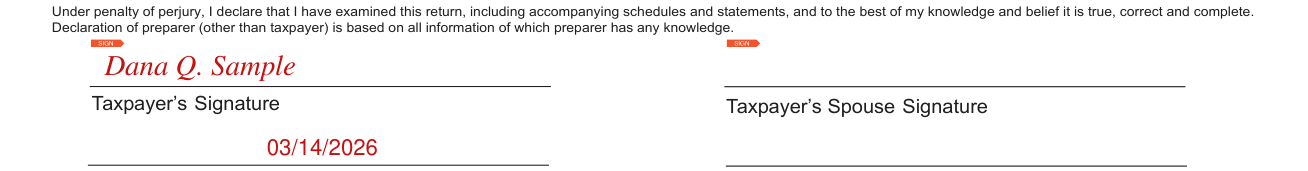
Under penalty of perjury, I declare that I have examined this return, including accompanying schedules and statements, and to the best of my knowledge and belief it is true, correct and complete.
More rules for Form 500-NOL
Attach a complete copy of your federal return for the loss year.
Please attach a copy of your federal application for NOL adjustment. Part year and nonresidents see instructions on page 4.
Be sure to attach all required forms and complete all lines of the Form 500-NOL that apply. Otherwise your application may be disallowed.
Form 500X should not be used to carryback a NOL. When the taxpayer only carries the loss forward, Form 500-NOL must also be filed by the due date (including extensions) of the loss year return, so the NOL can be established in the Department's system. The Page 2 carryback schedule should be left blank.
Line 41, Loss amount: Combine Lines 5 and 40. If the result is less than zero, enter it here. If the result is zero or more, you do not have a normal net operating loss. If the loss is being carried back to a part year or nonresident return, see instructions on Page 4.
Line 43, Total Net Operating Loss: Combine Lines 41 (if Line 41 is a negative) and Line 42. Enter on Page 1.
On 500-NOL Page 2, Lines 1 through 7 should not be completed for any years for which a part year or nonresident return was filed. Instead the part year and nonresident schedule on Page 4 should be completed.
Within 90 days from the last day of the month in which this form is filed, the Commissioner of Revenue shall make a limited examination of the form and disallow without further action any form containing errors of computation not correctable within such 90-day period or having material omissions.
A decrease of tax determined for prior year tax will first be credited against any unpaid tax and any remaining balance will be refunded to the taxpayer without interest within the 90-day period.
Common questions about Form 500-NOL
Is there a deadline?
This form must be filed no later than 3 years from the due date of the loss year income tax return, including any extensions which have been granted. When the taxpayer only carries the loss forward (Form 500X is not used to carryback a NOL), Form 500-NOL must be filed by the due date (including extensions) of the loss year return.
Where do I file it?
Mail it to the Georgia Department of Revenue Processing Center, PO Box 740318, Atlanta, GA. 30374-0318.
Sources
[1] Georgia Form 500-NOL (Rev. 12/31/20), Net Operating Loss Adjustment For Individuals and Fiduciaries, Georgia Department of Revenue (the Official source link on this page).