
Form CDTFA-447 at a glance
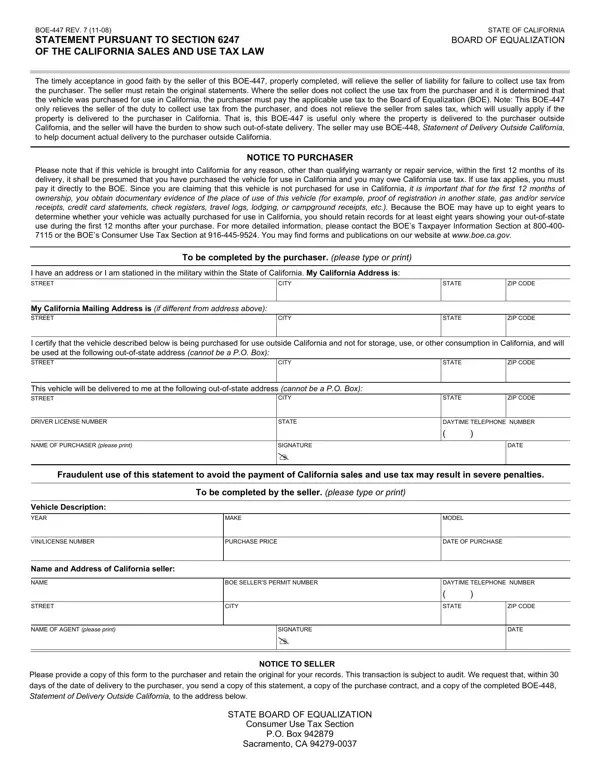
What it is: CDTFA-447 is the statement pursuant to Section 6247 of the California Sales and Use Tax Law of the California Department of Tax and Fee Administration.
Who signs: The Purchaser, Authorized Representative, or Member prints the name; business names will not be accepted. Under Name and Address of California Seller, print the Name of Agent, then add the Signature and the Date.
The purchaser completes the purchaser's section and the seller completes the seller's section; the seller retains the original. The timely acceptance in good faith by the seller of this CDTFA-447, properly completed, will relieve the seller of liability for failure to collect use tax from the purchaser.
A filled-in Form CDTFA-447 example: a California resident buys a truck delivered in Oregon
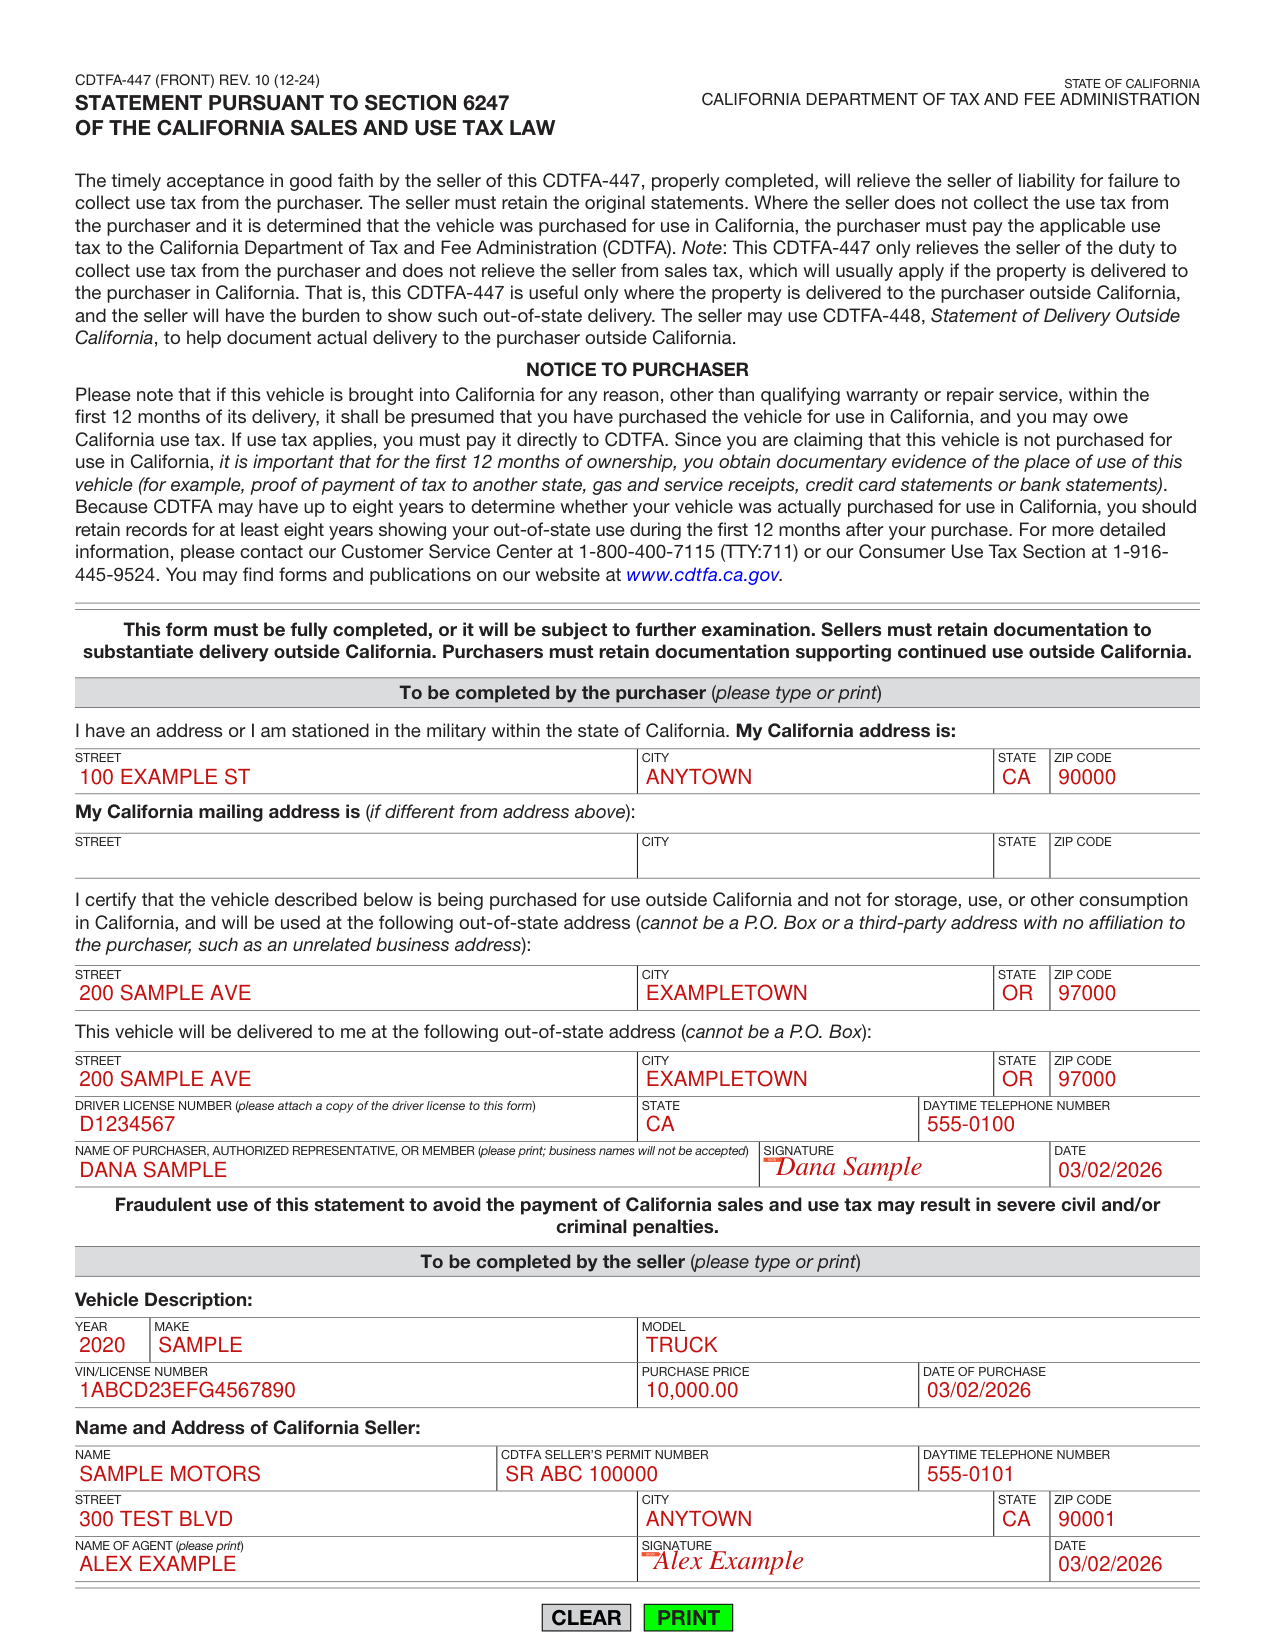
How to fill out Form CDTFA-447, box by box
The California address and the California mailing address
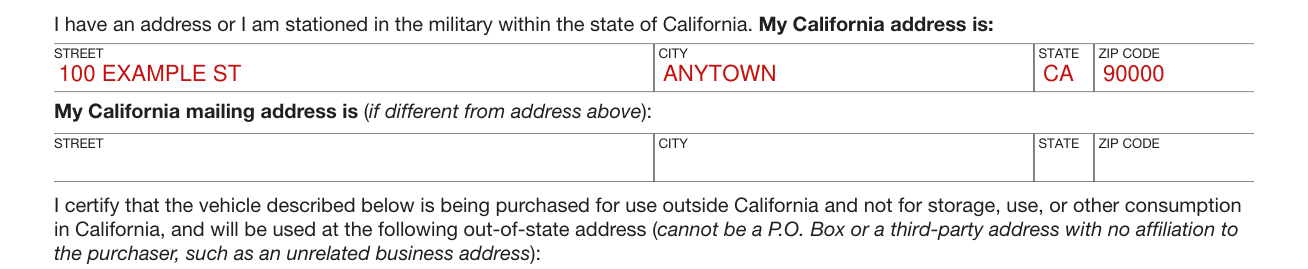
The purchaser's section is to be completed by the purchaser (please type or print).
Under "I have an address or I am stationed in the military within the state of California. My California address is:", enter the Street, City, State and Zip Code.
Under "My California mailing address is (if different from address above):", enter the Street, City, State and Zip Code.
The out-of-state use address and the delivery address
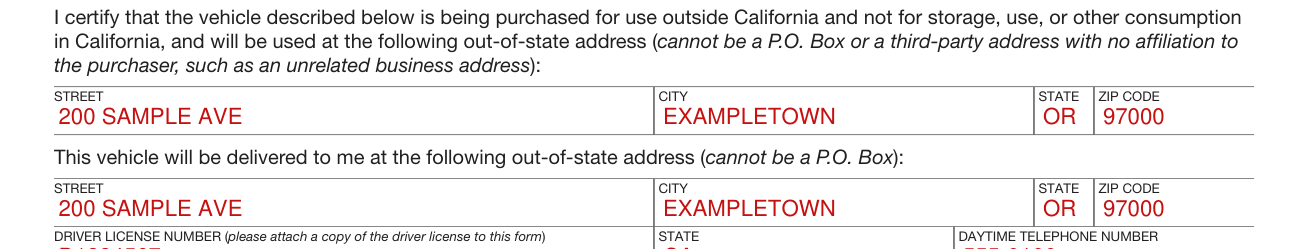
Enter the Street, City, State and Zip Code of the out-of-state address where the vehicle, purchased for use outside California and not for storage, use, or other consumption in California, will be used. The address cannot be a P.O. Box or a third-party address with no affiliation to the purchaser, such as an unrelated business address.
Enter the Street, City, State and Zip Code of the out-of-state address where this vehicle will be delivered to you; the address cannot be a P.O. Box.
Driver license number, state and daytime telephone number

Enter the Driver License Number, the State and the Daytime Telephone Number, and attach a copy of the driver license to this form.
Signature and date

Add the Signature and the Date.
Fraudulent use of this statement to avoid the payment of California sales and use tax may result in severe civil and/or criminal penalties.
The vehicle description
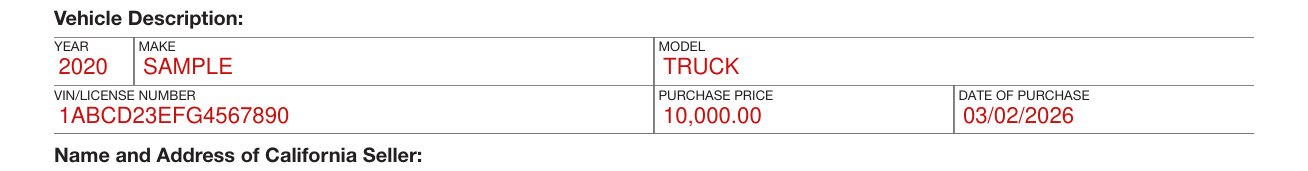
The seller's section is to be completed by the seller (please type or print).
Under Vehicle Description, enter the Year, Make, Model, VIN/License Number, Purchase Price and Date of Purchase.
Name and address of California seller
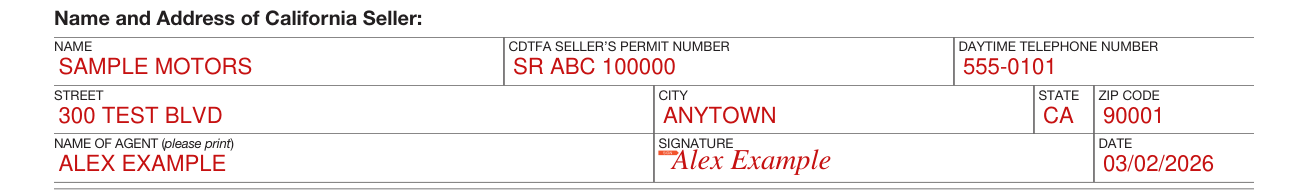
Under Name and Address of California Seller, enter the Name, CDTFA Seller's Permit Number, Daytime Telephone Number, and the Street, City, State and Zip Code.
Print the Name of Agent (please print), then add the Signature and the Date.
More rules for Form CDTFA-447
The seller must retain the original statements.
Where the seller does not collect the use tax from the purchaser and it is determined that the vehicle was purchased for use in California, the purchaser must pay the applicable use tax to the California Department of Tax and Fee Administration (CDTFA).
The seller may use CDTFA-448, Statement of Delivery Outside California, to help document actual delivery to the purchaser outside California.
Notice to purchaser: if this vehicle is brought into California for any reason, other than qualifying warranty or repair service, within the first 12 months of its delivery, it shall be presumed that you have purchased the vehicle for use in California, and you may owe California use tax.
If use tax applies, you must pay it directly to CDTFA.
Since you are claiming that this vehicle is not purchased for use in California, it is important that for the first 12 months of ownership, you obtain documentary evidence of the place of use of this vehicle (for example, proof of payment of tax to another state, gas and service receipts, credit card statements or bank statements).
Because CDTFA may have up to eight years to determine whether your vehicle was actually purchased for use in California, you should retain records for at least eight years showing your out-of-state use during the first 12 months after your purchase.
For more detailed information, contact the Customer Service Center at 1-800-400-7115 (TTY:711) or the Consumer Use Tax Section at 1-916- 445-9524.
You may find forms and publications on the website at www.cdtfa.ca.gov.
This form must be fully completed, or it will be subject to further examination. Sellers must retain documentation to substantiate delivery outside California. Purchasers must retain documentation supporting continued use outside California.
Notice to seller: Please provide a copy of this form to the purchaser and retain the original for your records.
This transaction is subject to audit.
Common questions about Form CDTFA-447
Is there a deadline?
Notice to seller: the seller is requested to send a copy of this form and attach a copy of the purchaser's driver license, a copy of the purchase contract, and a copy of the completed CDTFA-448, Statement of Delivery Outside California, and relevant shipping documentation within 30 days of the date of delivery to the purchaser.
Where do I file it?
Notice to seller: the seller is requested to send a copy of this form, CDTFA-447, to the California Department of Tax and Fee Administration, Consumer Use Tax Section, PO Box 942879, Sacramento, CA 94279-0037. The seller is also requested to attach a copy of the purchaser's driver license, a copy of the purchase contract, and a copy of the completed CDTFA-448, Statement of Delivery Outside California, and relevant shipping documentation.
When is this form not the right one?
This CDTFA-447 only relieves the seller of the duty to collect use tax from the purchaser and does not relieve the seller from sales tax, which will usually apply if the property is delivered to the purchaser in California. That is, this CDTFA-447 is useful only where the property is delivered to the purchaser outside California, and the seller will have the burden to show such out-of-state delivery.
Sources
[1] Form CDTFA-447 (12-24), Statement Pursuant to Section 6247 of the California Sales and Use Tax Law, California Department of Tax and Fee Administration (the Official source link on this page).