
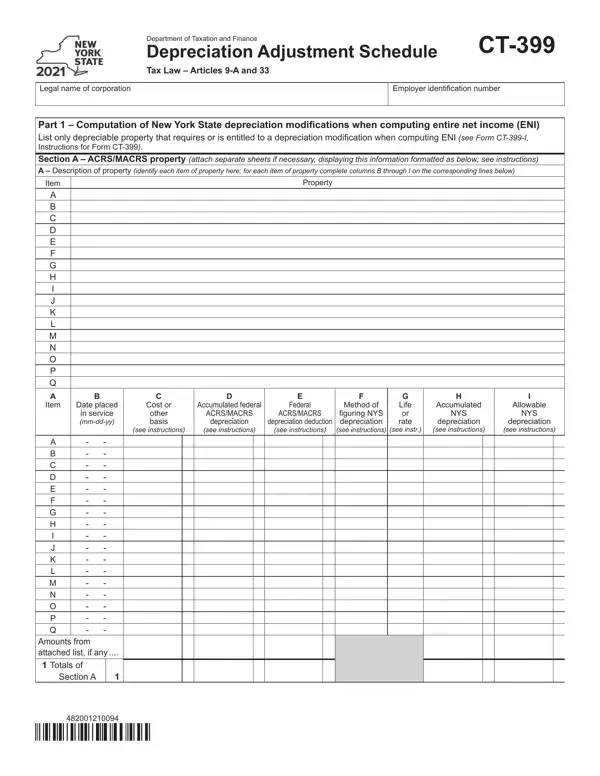
Part 1 is the computation of New York State depreciation modifications when computing New York State taxable income.
Part 1: list only depreciable property that requires or is entitled to a depreciation modification when computing New York State taxable income.
Sections: Section A is ACRS/MACRS property. Section B is property qualified under IRC section 168(k)(2) for federal special depreciation.
Disposed property: if you have disposed of any property listed on this form in a prior year, complete Parts 2 and 3.
Part 3: summary of adjustments to New York State taxable income.
Investment tax credit: In this tax period, did you dispose of property for which the investment tax credit was previously claimed?
| Question | Answer |
|---|---|
| Form Name | CT-399 |
| Form Length | 3 pages |
| Fillable? | No |
| Fillable fields | 0 |
| Avg. time to fill out | 9 min |
| Edition | 2025 |
| Issuing agency | Department of Taxation and Finance |
| Matches the agency's file | Yes, checked October 2, 2026 |
| Other names | CT-399, CT399, CT 399, Form CT-399, Depreciation Adjustment Schedule |
| Official source | CT-399 (Rev 2025), Department of Taxation and Finance |
Form Ct 399 isn’t the one you’re looking for?