

Form ET-706 at a glance
What it is: New York State Estate Tax Return, Form ET-706, for an estate of an individual who died on or after January 1, 2025.
Who signs: Executor, attorney, and preparer, be sure to sign this return on page 6.
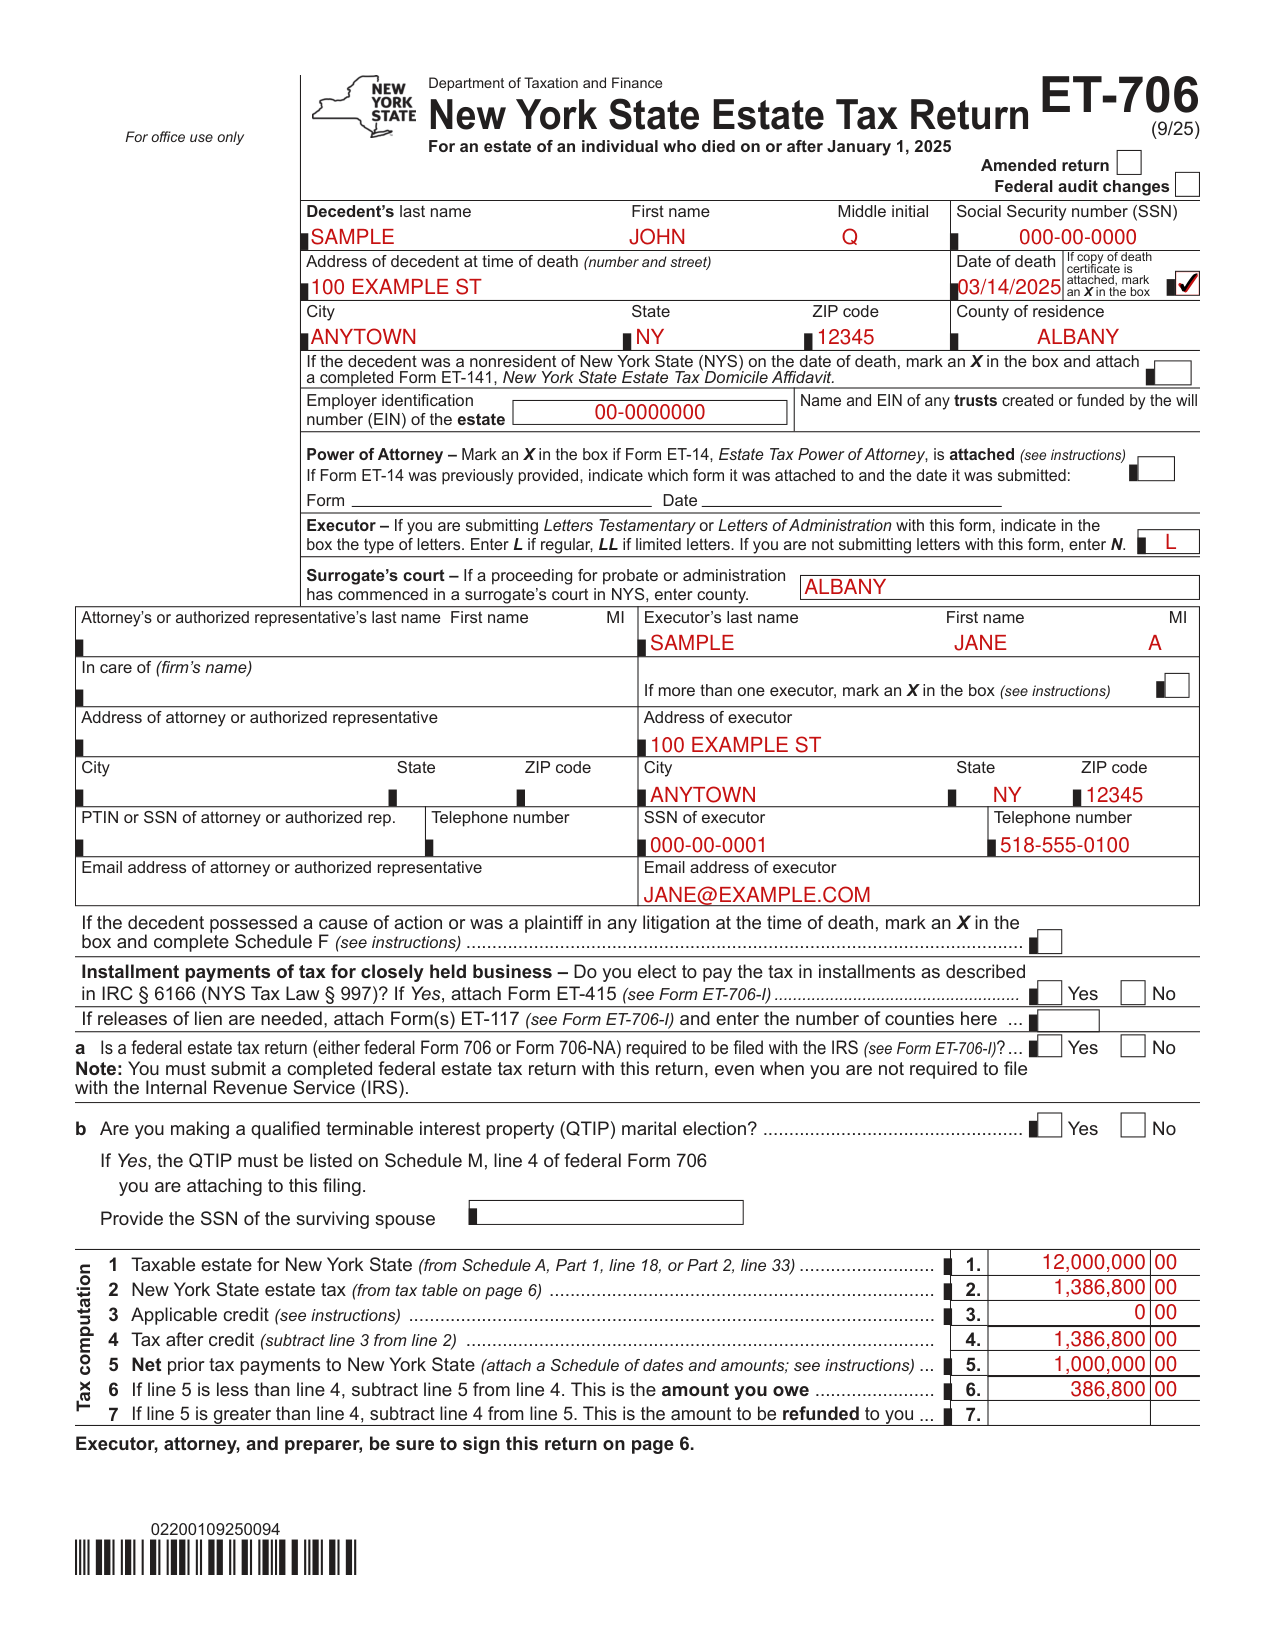
A filled-in Form ET-706 example: an executor files for a New York resident's estate
How to fill out Form ET-706, box by box
Decedent, date of death and county of residence
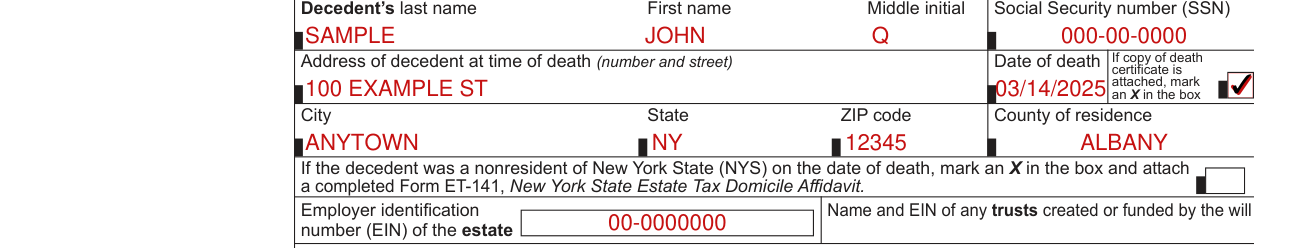
Enter the decedent's last name, first name and middle initial.
Enter the decedent's Social Security number (SSN).
Enter the address of the decedent at the time of death (number and street), then the City, State and ZIP code.
Enter the Date of death and the County of residence.
If a copy of the death certificate is attached, mark an X in the box.
Nonresident decedent

If the decedent was a nonresident of New York State (NYS) on the date of death, mark an X in the box and attach a completed Form ET-141, New York State Estate Tax Domicile Affidavit.
Estate EIN, trusts, letters and surrogate's court
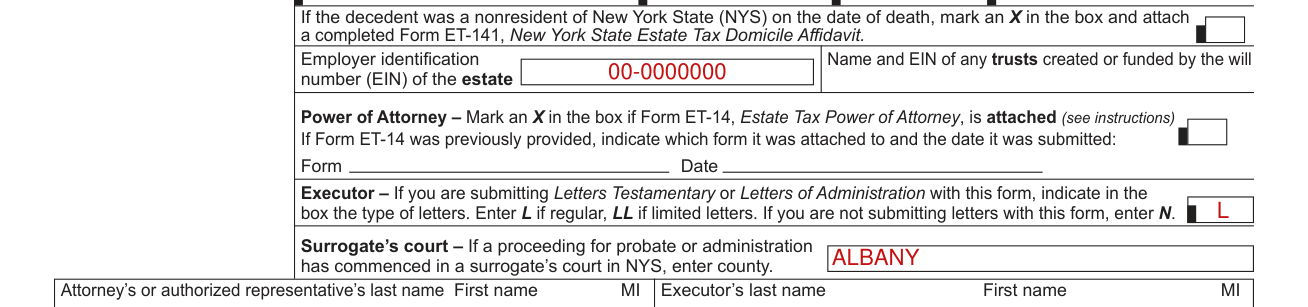
Enter the Employer identification number (EIN) of the estate.
Enter the Name and EIN of any trusts created or funded by the will.
Executor - If you are submitting Letters Testamentary or Letters of Administration with this form, indicate in the box the type of letters. Enter L if regular, LL if limited letters. If you are not submitting letters with this form, enter N.
Surrogate's court - If a proceeding for probate or administration has commenced in a surrogate's court in NYS, enter county.
Executor
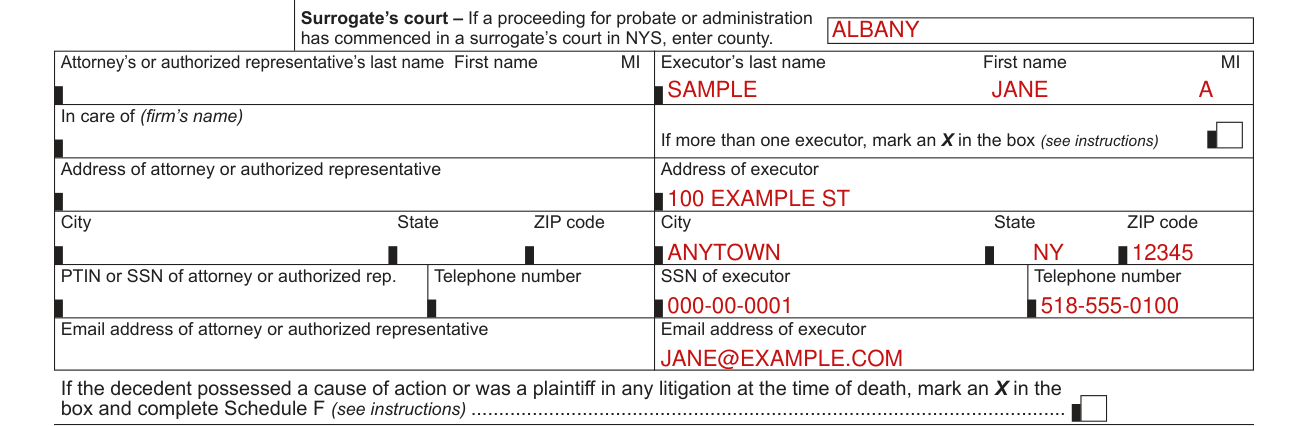
Enter the executor's last name, first name and MI.
If more than one executor, mark an X in the box (see instructions).
Enter the address of the executor, then the City, State and ZIP code.
Enter the SSN of the executor, the Telephone number and the Email address of the executor.
Tax computation
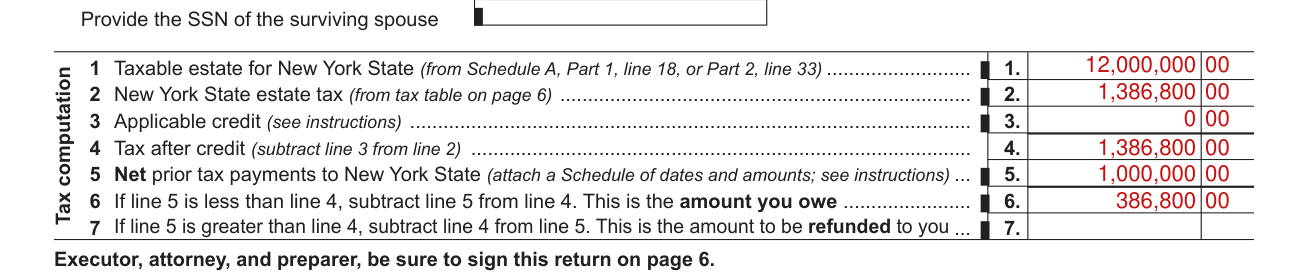
On line 1, enter the Taxable estate for New York State (from Schedule A, Part 1, line 18, or Part 2, line 33).
On line 2, enter the New York State estate tax (from tax table on page 6).
On line 3, enter the Applicable credit (see instructions).
On line 4, enter the Tax after credit (subtract line 3 from line 2).
On line 5, enter the Net prior tax payments to New York State (attach a Schedule of dates and amounts; see instructions).
If line 5 is less than line 4, subtract line 5 from line 4 on line 6. This is the amount you owe. If line 5 is greater than line 4, subtract line 4 from line 5 on line 7. This is the amount to be refunded to you.
If there is an amount due on line 6, make check payable in U.S. funds to Commissioner of Taxation and Finance.
Schedule A, Part 1 - Resident
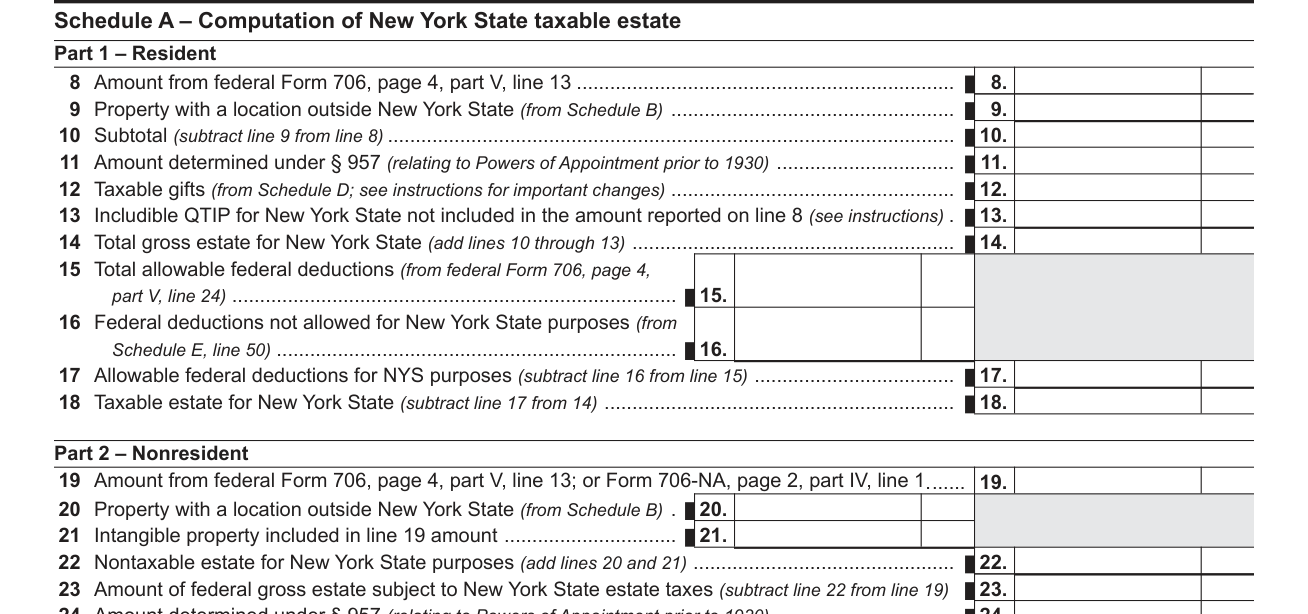
Under Schedule A, Part 1 - Resident, enter on line 8 the Amount from federal Form 706, page 4, part V, line 13.
On line 9, enter the Property with a location outside New York State (from Schedule B).
On line 18, enter the Taxable estate for New York State (subtract line 17 from 14).
On line 50, enter the Federal deductions not allowed for New York State purposes (add lines 48 and 49; also enter on Schedule A, Part 1, line 16).
Schedule B - Property located outside New York State
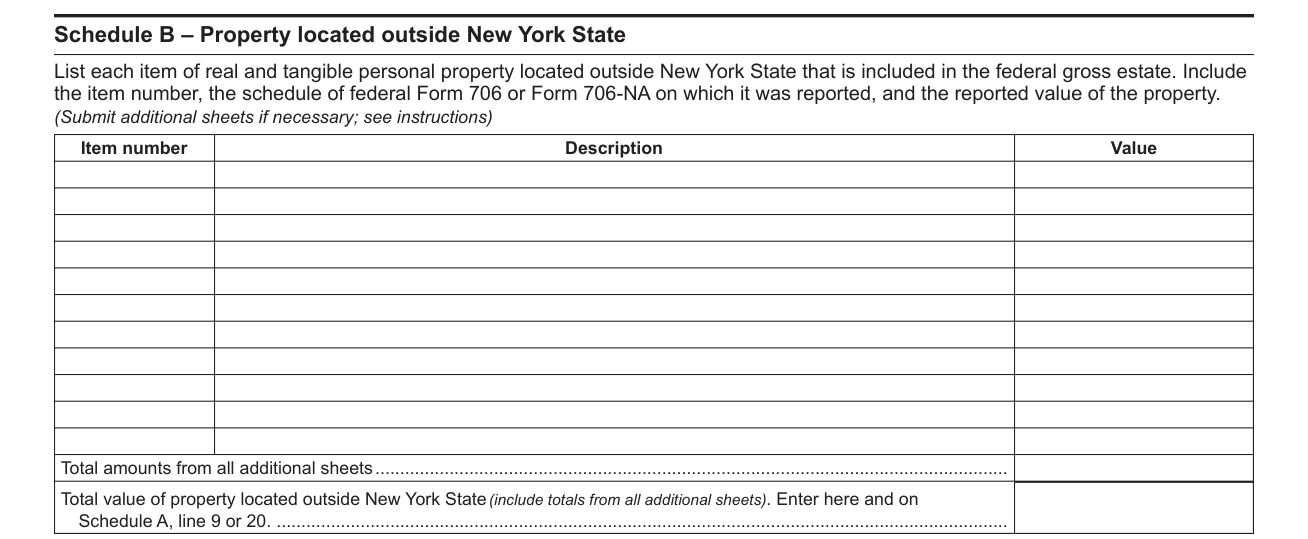
Under Schedule B - Property located outside New York State, list each item of real and tangible personal property located outside New York State that is included in the federal gross estate. Include the item number, the schedule of federal Form 706 or Form 706-NA on which it was reported, and the reported value of the property.
Enter the Total value of property located outside New York State (include totals from all additional sheets). Enter here and on Schedule A, line 9 or 20.
Schedule D - Taxable gifts
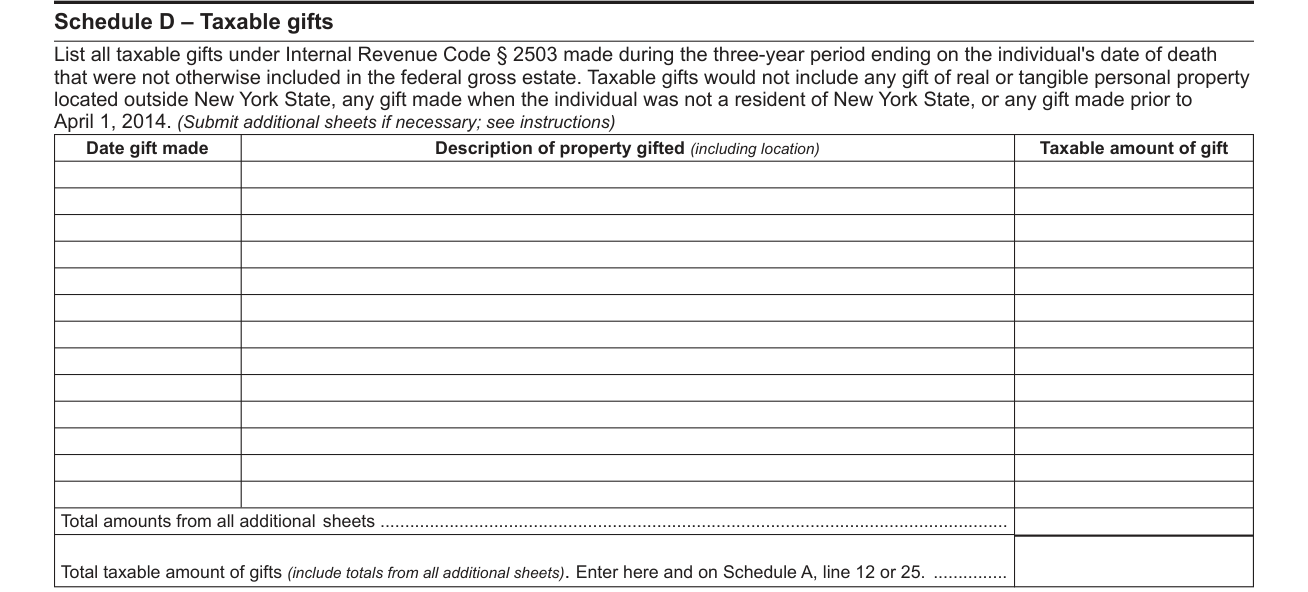
Under Schedule D - Taxable gifts, list all taxable gifts under Internal Revenue Code § 2503 made during the three-year period ending on the individual's date of death that were not otherwise included in the federal gross estate. Taxable gifts would not include any gift of real or tangible personal property located outside New York State, any gift made when the individual was not a resident of New York State, or any gift made prior to April 1, 2014.
Enter the Total taxable amount of gifts (include totals from all additional sheets). Enter here and on Schedule A, line 12 or 25.
Signing the return
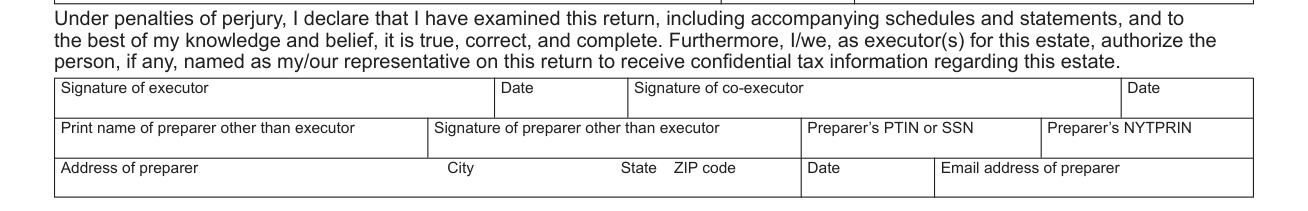
Declare, under penalties of perjury, that you have examined this return, including accompanying schedules and statements, and to the best of your knowledge and belief, it is true, correct, and complete.
Sign with the Signature of executor and the Date, and with the Signature of co-executor and the Date.
Enter the Print name of preparer other than executor, Preparer's PTIN or SSN and Preparer's NYTPRIN; sign Signature of preparer other than executor; then enter the Address of preparer, City, State, ZIP code, Date and Email address of preparer.
More rules for Form ET-706
If not using U.S. Mail, see Publication 55, Designated Private Delivery Services.
Attach a completed copy of the federal estate tax return along with any accompanying schedules and supplementary information.
If an attorney or authorized representative is listed on this return, they must complete the following declaration.
If the decedent possessed a cause of action or was a plaintiff in any litigation at the time of death, mark an X in the box and complete Schedule F (see instructions).
Is a federal estate tax return (either federal Form 706 or Form 706-NA) required to be filed with the IRS (see Form ET-706-I)? Yes or No. Note: You must submit a completed federal estate tax return with this return, even when you are not required to file with the Internal Revenue Service (IRS).
Are you making a qualified terminable interest property (QTIP) marital election? Yes or No. If Yes, the QTIP must be listed on Schedule M, line 4 of federal Form 706 you are attaching to this filing. Provide the SSN of the surviving spouse.
Common questions about Form ET-706
Is there a deadline?
This return must be filed within nine months after the date of death unless an extension of time to file the return has been granted.
Where do I file it?
Mail your return and payment (if any) to: NYS ESTATE TAX PROCESSING CENTER, PO BOX 15167, ALBANY NY 12212-5167.
Sources
[1] Form ET-706 (9/25), New York State Estate Tax Return, New York State Department of Taxation and Finance (the Official source link on this page).