
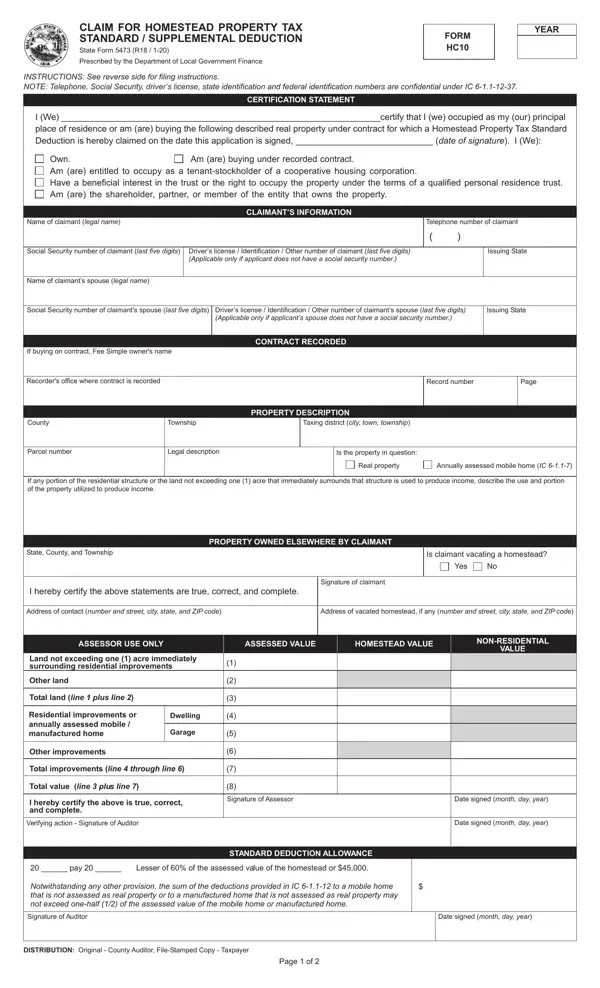

Form HC10 at a glance
What it is: HC10, State Form 5473, is the Claim for Homestead Property Tax Standard / Supplemental Deduction, prescribed by the Department of Local Government Finance.
Where and when to file: Forms must be filed at the county auditor's office in the county where the homestead is located.
Notice of Homestead Standard Deduction, Indiana Code § 6-1.1-12-37: The homestead standard deduction has been enacted to allow a property tax deduction for each qualified homestead.
An individual may qualify who owns a homestead, is buying a homestead under a recorded contract that requires the individual to pay the property taxes and that obligates the seller to convey title to the individual upon completion of all of the individual's contract obligations, or is entitled to occupy the homestead as a tenant-stockholder of a cooperative housing corporation.
A filled-in Form HC10 example: a married couple claims the deduction on a home they own
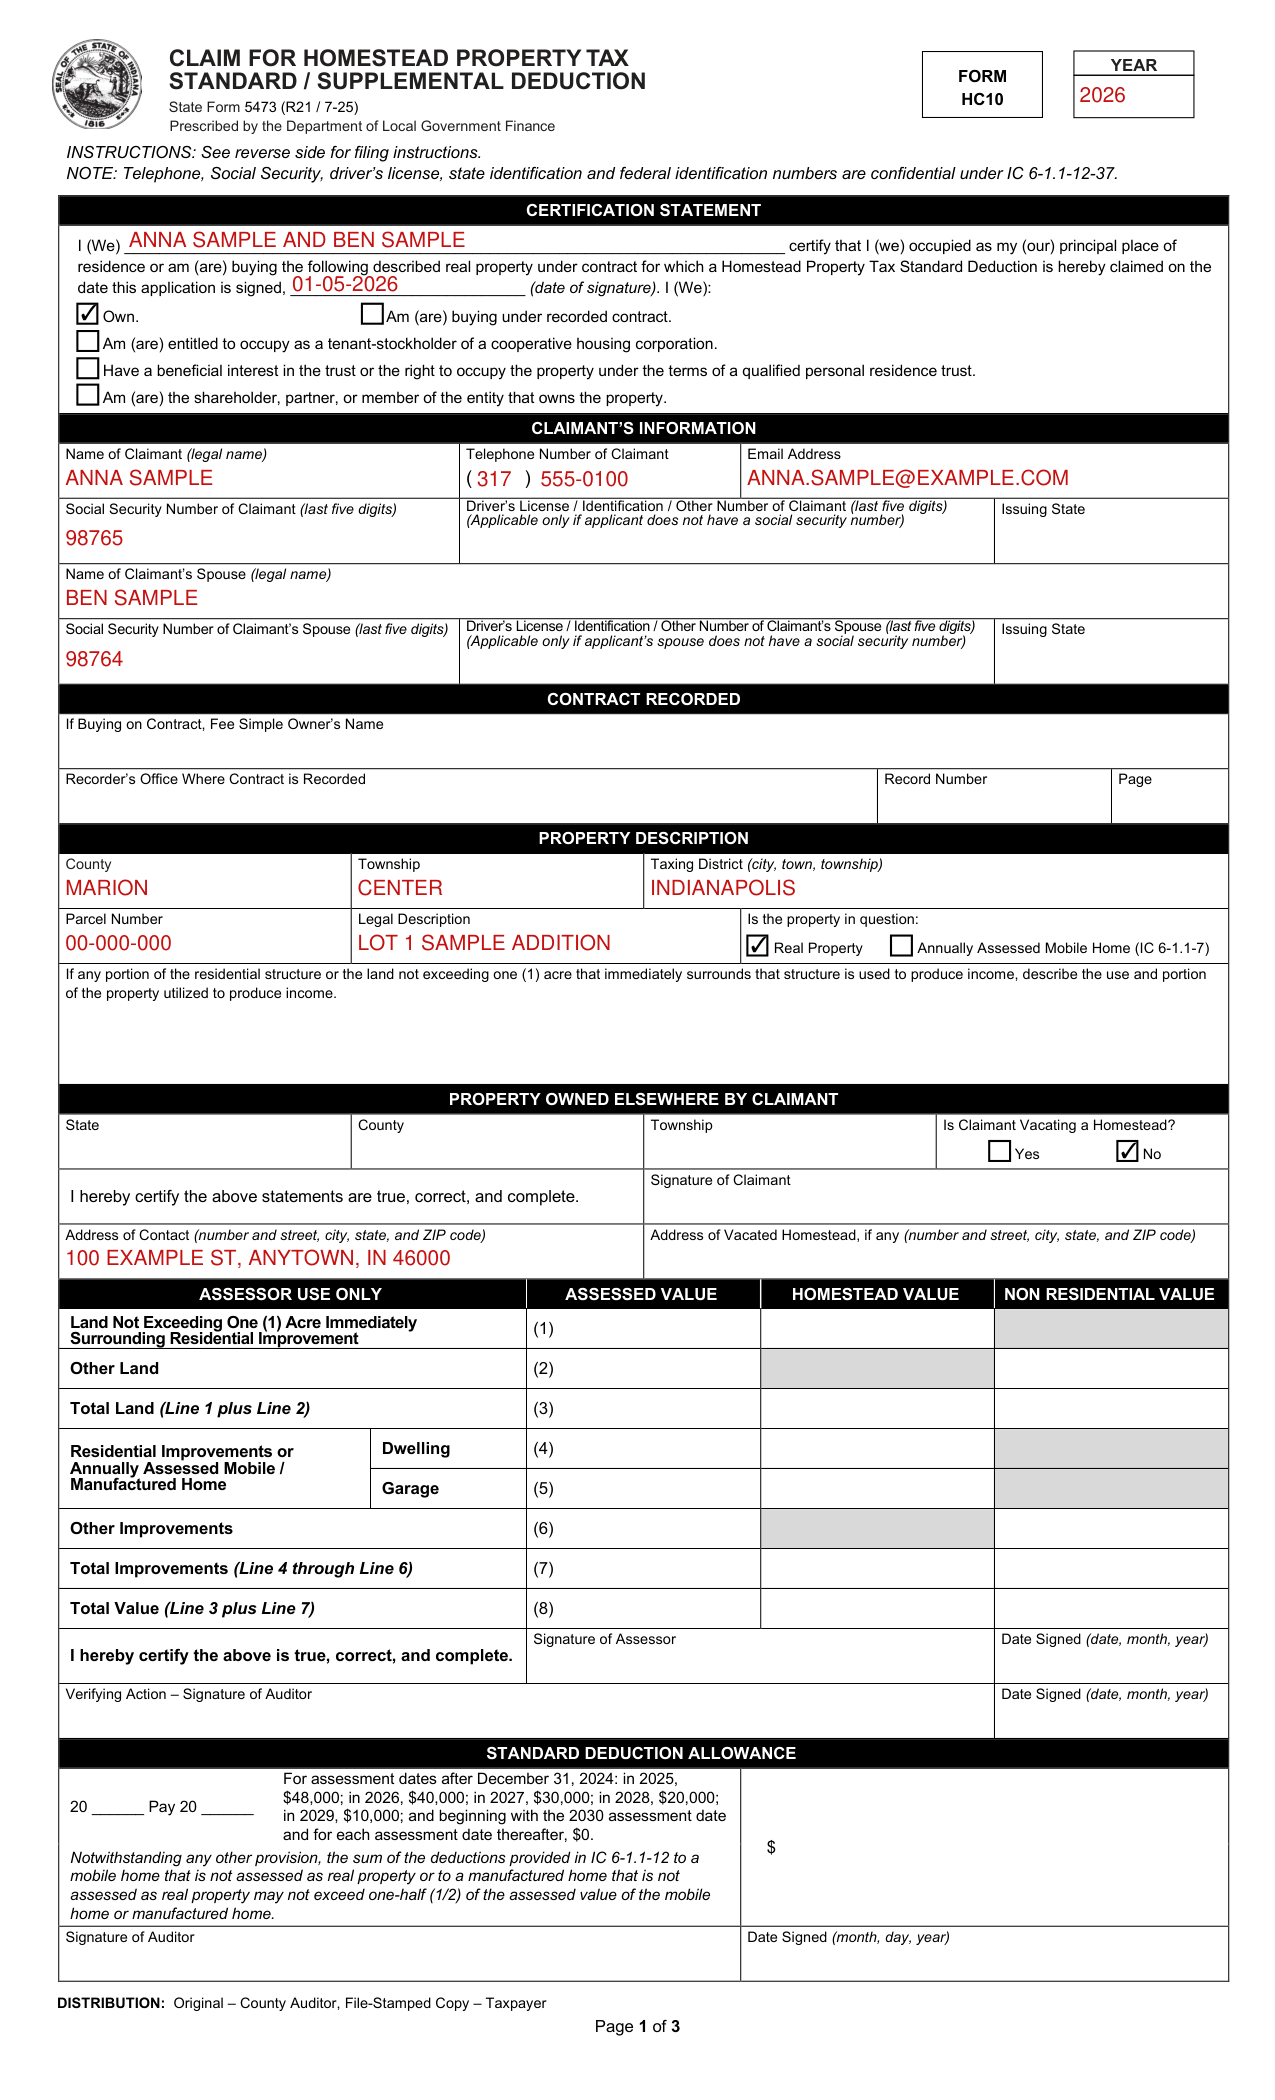
How to fill out Form HC10, box by box
Certification statement: Own, Am (are) buying under recorded contract
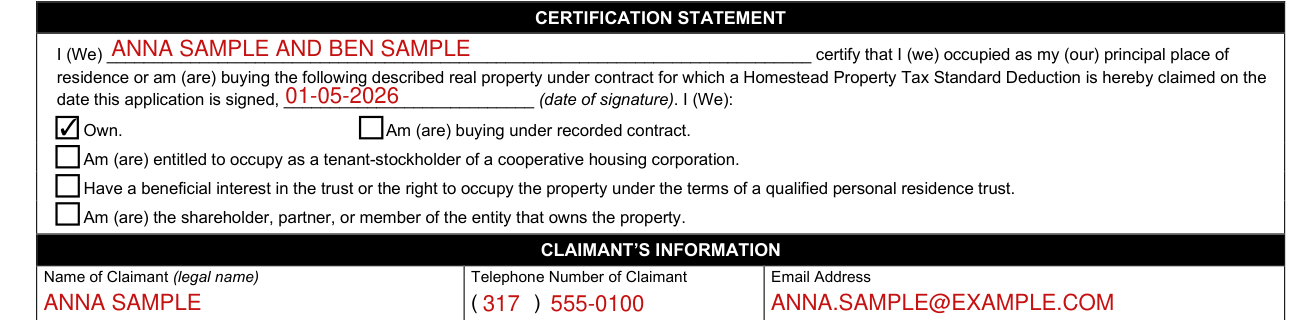
In the CERTIFICATION STATEMENT, check the box that applies. Own. Am (are) buying under recorded contract. Am (are) entitled to occupy as a tenant-stockholder of a cooperative housing corporation. Have a beneficial interest in the trust or the right to occupy the property under the terms of a qualified personal residence trust. Am (are) the shareholder, partner, or member of the entity that owns the property.
Under CERTIFICATION STATEMENT, write on the line for the (date of signature).
Claimant's information
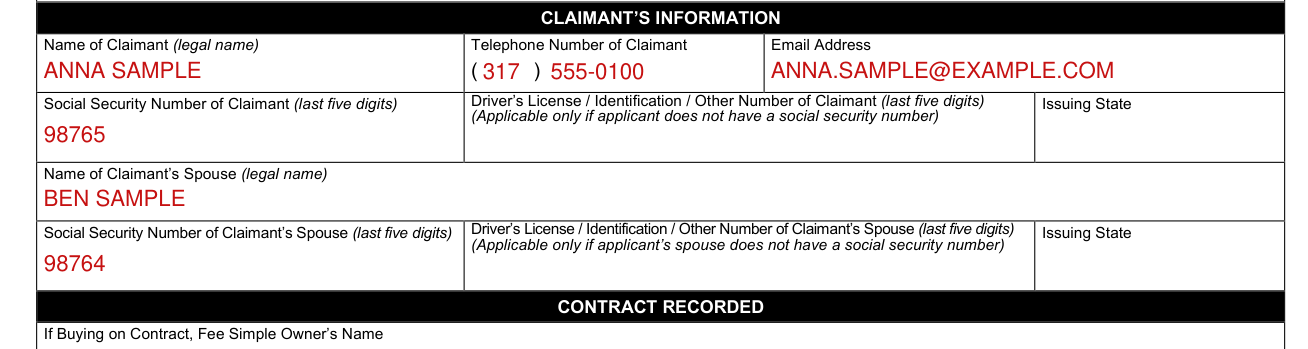
Enter the Name of Claimant (legal name), the Telephone Number of Claimant and the Email Address.
Enter the Social Security Number of Claimant (last five digits). Enter the Driver's License / Identification / Other Number of Claimant (last five digits) (Applicable only if applicant does not have a social security number) and the Issuing State.
Enter the Name of Claimant's Spouse (legal name) and the Social Security Number of Claimant's Spouse (last five digits). Enter the Driver's License / Identification / Other Number of Claimant's Spouse (last five digits) (Applicable only if applicant's spouse does not have a social security number) and the Issuing State.
Contract recorded
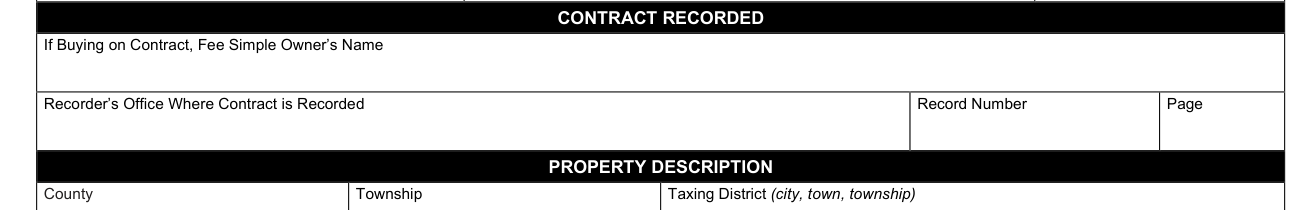
If Buying on Contract, enter the Fee Simple Owner's Name, the Recorder's Office Where Contract is Recorded, the Record Number and the Page.
Property description
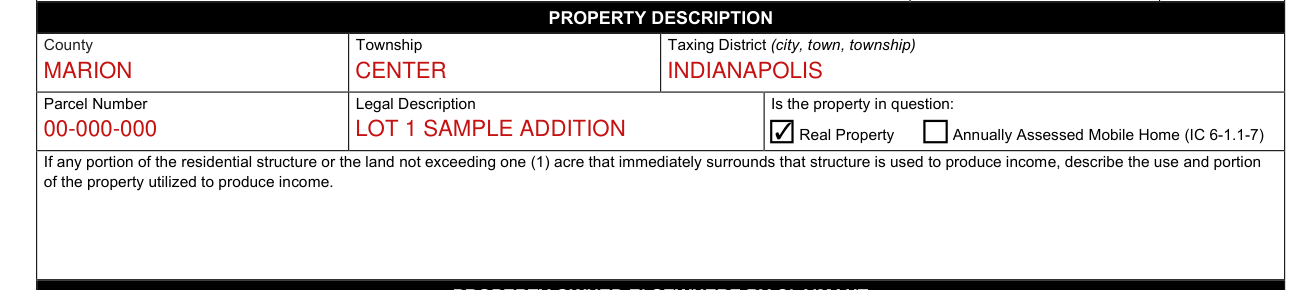
Enter the County, Township, Taxing District (city, town, township), Parcel Number and Legal Description of the property.
Check Real Property or Annually Assessed Mobile Home (IC 6-1.1-7) after "Is the property in question:".
If any portion of the residential structure or the land not exceeding one (1) acre that immediately surrounds that structure is used to produce income, describe the use and portion of the property utilized to produce income.
No portion of a residential dwelling that is income-producing is eligible for the homestead standard deduction, including, but not limited to, one-half of a duplex side or rented apartment that is a part of the structure, a beauty shop or crafts shop in one or two rooms of the structure, a dry cleaners or electronics shop beneath an apartment, or an auto repair shop in the garage.
Property owned elsewhere by claimant
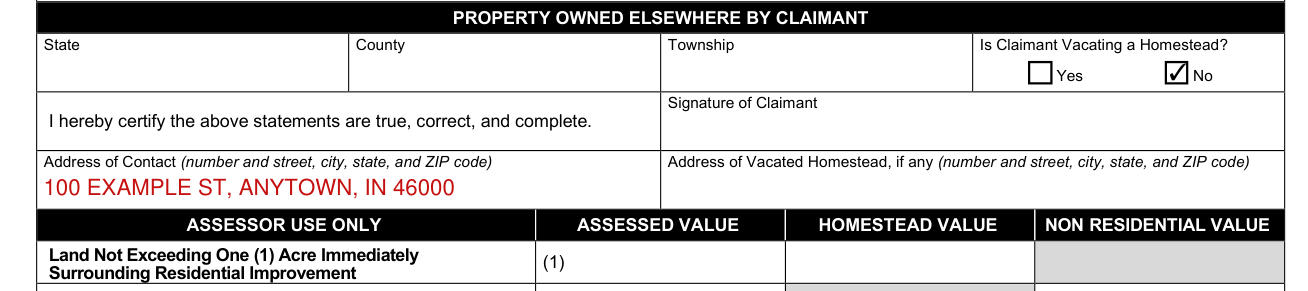
Under PROPERTY OWNED ELSEWHERE BY CLAIMANT, enter the State, County and Township.
Check Yes or No after "Is Claimant Vacating a Homestead?".
Enter the Address of Vacated Homestead, if any (number and street, city, state, and ZIP code).
Signature of claimant
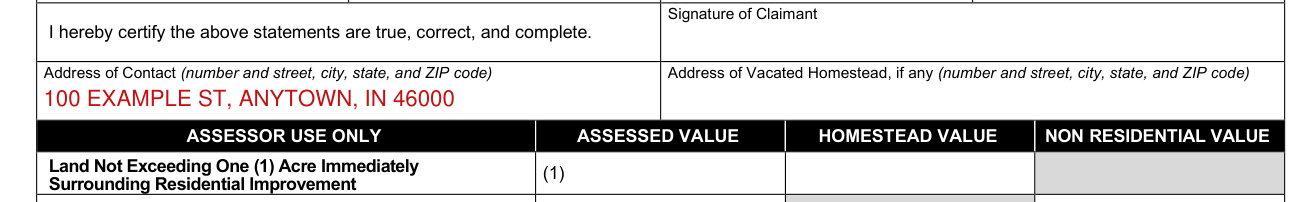
Sign on the Signature of Claimant line: "I hereby certify the above statements are true, correct, and complete."
Enter the Address of Contact (number and street, city, state, and ZIP code).
A person must actually be eligible for the deduction at the time the application is signed, meaning the property is being used as the person's principal place of residence at the time of signing.
Assessor use only
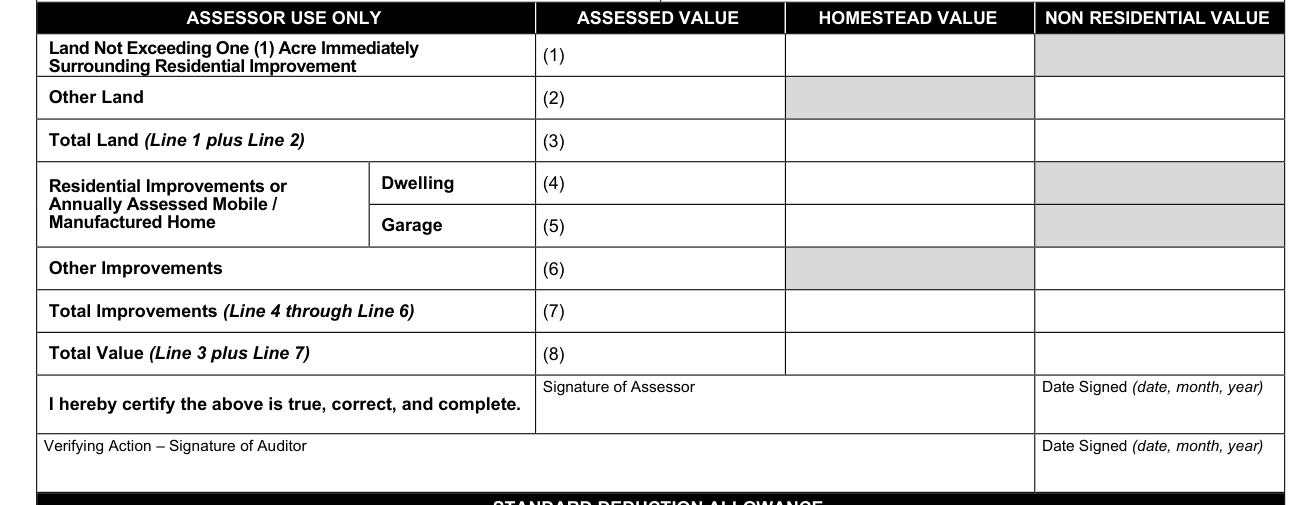
Assessor use only: assessed value, homestead value, non residential value.
Signature of Assessor and Verifying Action - Signature of Auditor each have a Date Signed (date, month, year) line.
Standard deduction allowance
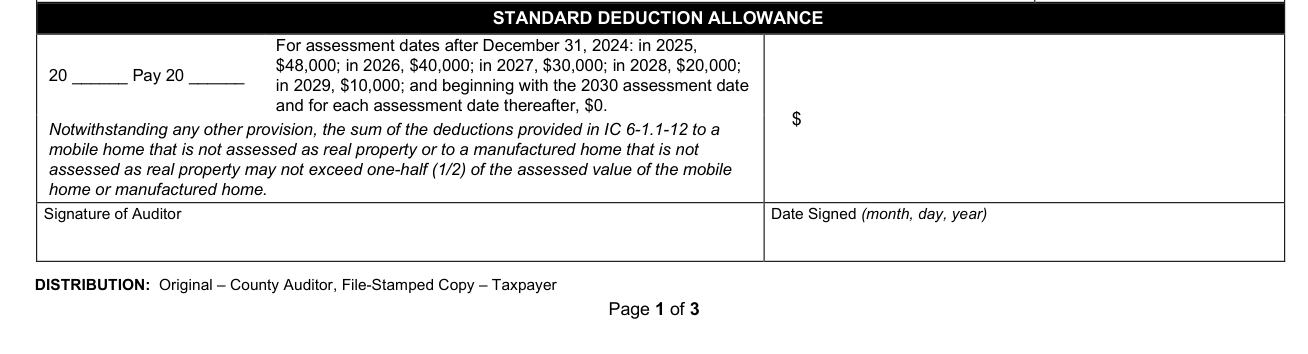
STANDARD DEDUCTION ALLOWANCE: Signature of Auditor, Date Signed (month, day, year).
More rules for Form HC10
If an individual mails this form and desires to have a file-stamped copy returned, the individual must provide a self-addressed, stamped envelope to the county auditor's office.
Common mistake: The portion of the form before the "Signature of claimant" must be completed in full before the deduction will be considered.
If your situation is different
A person moves to a new principal place of residence
If a person moves from the person's Indiana principal place of residence (for which the person is receiving a homestead deduction) after the assessment date to a new principal place of residence later that year, the homestead deduction on the first property will stay in place for that tax cycle and the person can apply for and potentially receive a homestead deduction on the new property for that same tax cycle.
For the next assessment date, the homestead deduction would be removed from the first property.
You claim a homestead deduction for different property on another application
Only one individual or married couple may receive a homestead deduction for a particular homestead in a particular year.
The county auditor may not grant an individual or married couple a homestead deduction if: 1. for the same year, the individual or married couple claims the homestead deduction on two (2) or more different deduction applications; and 2. the applications claim the homestead deduction for different property.
The property is owned by a corporation, partnership, limited liability company, or other entity
Property owned by a corporation, partnership, limited liability company, or other entity is not entitled to the homestead standard deduction unless the requirements of IC 6-1.1-12-37(r) are met.
Common questions about Form HC10
Is there a deadline?
To obtain the deduction for a desired calendar year in which property taxes are first due and payable, the application must be completed, dated, and filed or postmarked with the county auditor on or before January 15 of the calendar year in which the property taxes are first due and payable. The application applies for that first year and any succeeding year for which the deduction is allowed.
Where do I file it?
Forms must be filed at the county auditor's office in the county where the homestead is located.
Is there a penalty?
If an individual whose property becomes ineligible for the homestead deduction fails to file a certified statement with the county auditor notifying the auditor of the ineligibility within sixty (60) days after the date of the change, the individual is liable for the amount of the deduction allowed for that real property, plus a civil penalty equal to ten percent (10%) of the additional taxes due.
Sources
[1] Form HC10 (State Form 5473, R21 / 7-25), Department of Local Government Finance, State of Indiana (the Official source link on this page).