
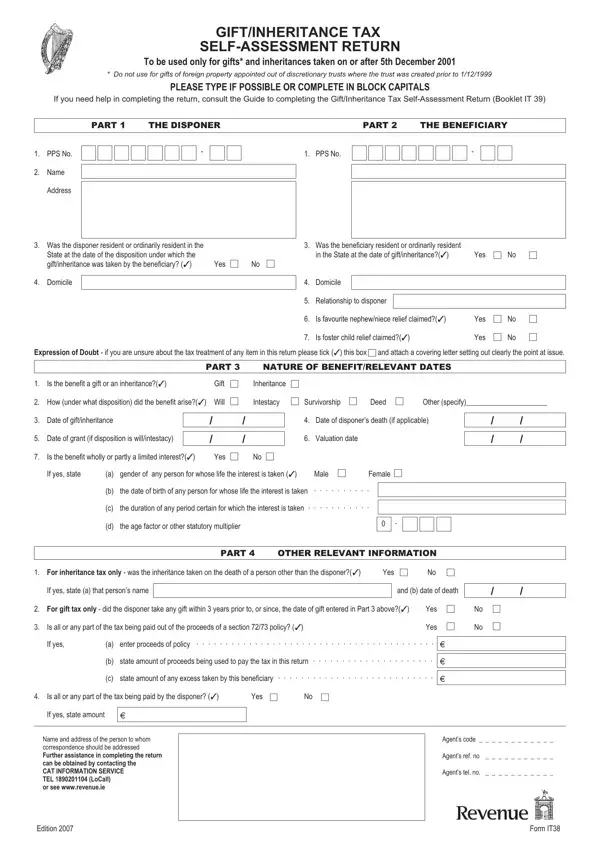

Form IT38S at a glance
What it is: Form IT38S is the Capital Acquisitions Tax (CAT) return for gift(s) and/or inheritance(s) received on or after the 5th of December 2001.
Where and when to file: Complete the payslip and forward it to the Collector-General, PO Box 354, Limerick.
A filled-in Form IT38S example: a gift from a father
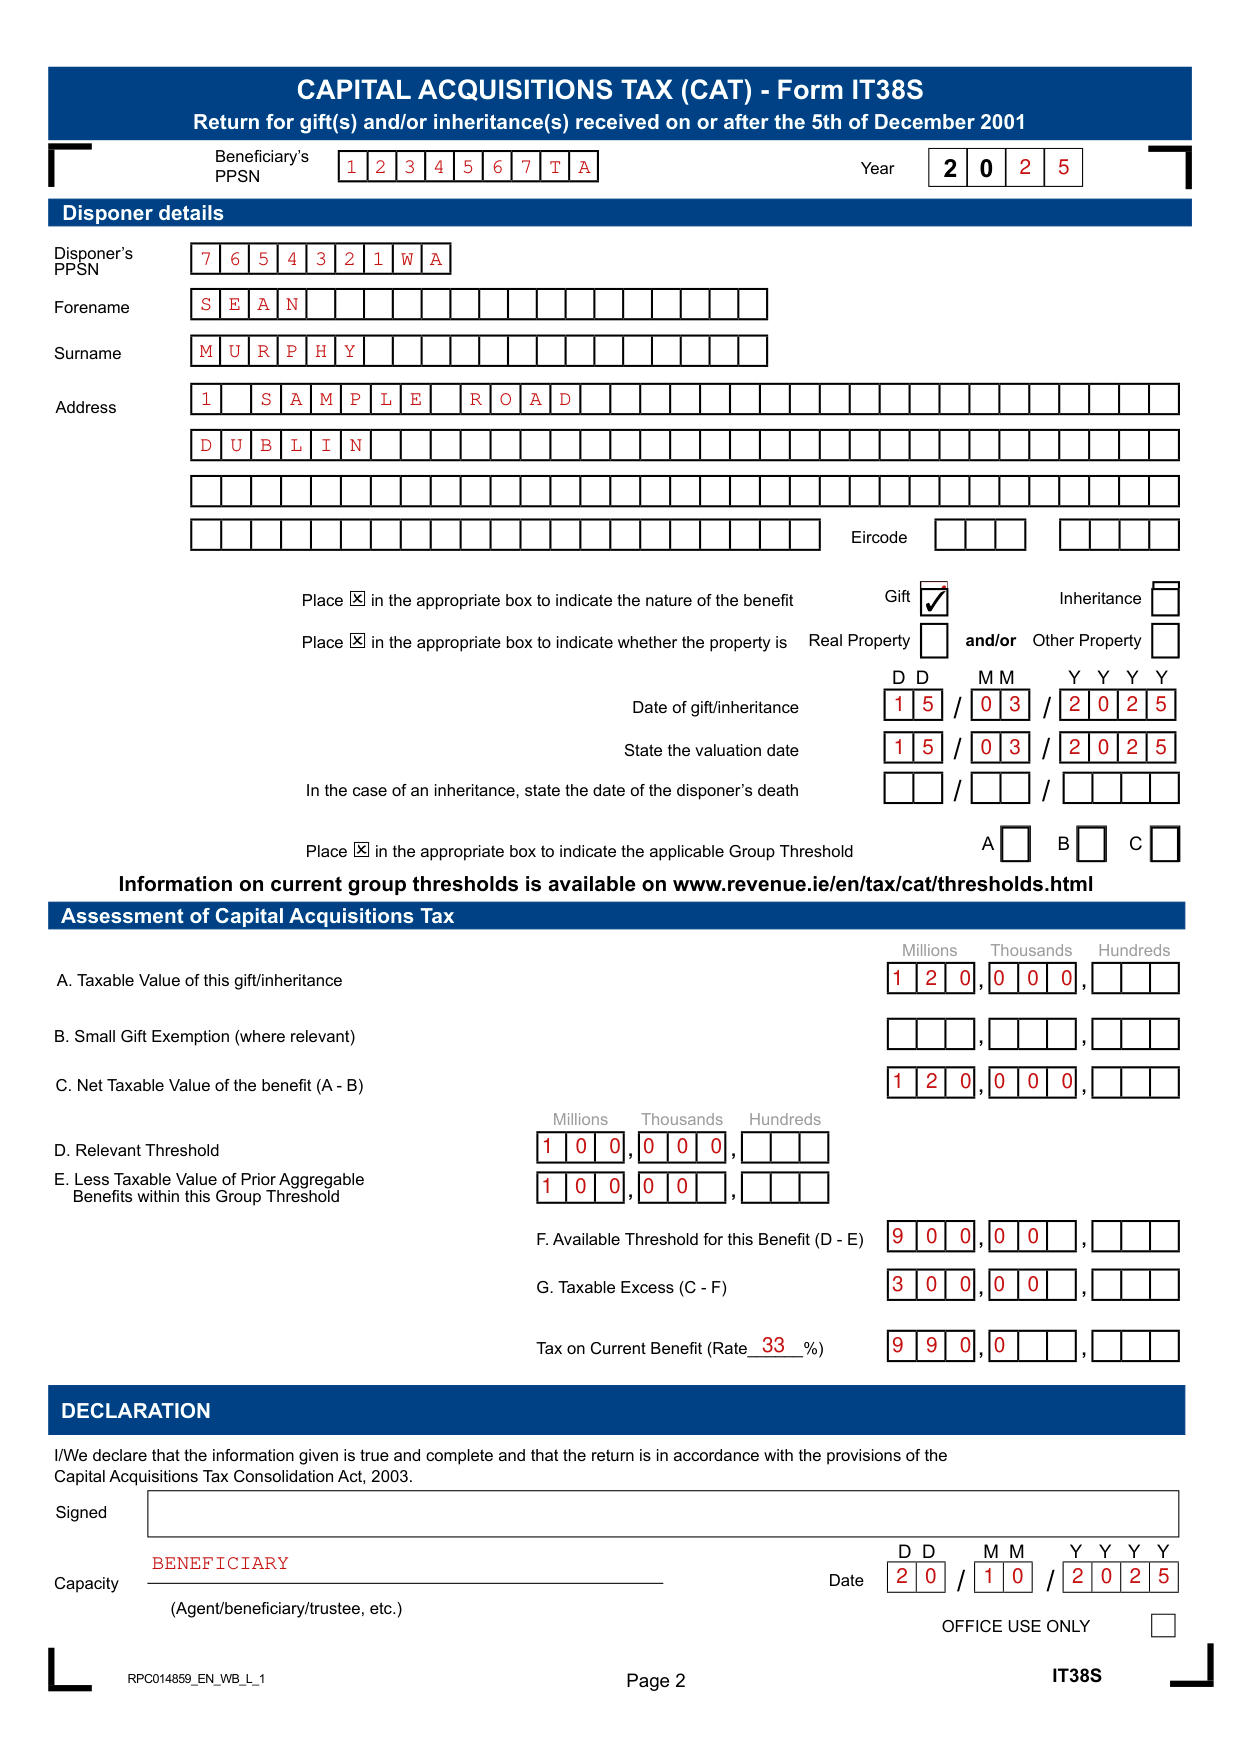
How to fill out Form IT38S, box by box
Who may use this form
You may only use this form if no relief, exemption or credit is claimed, apart from small gift exemption, and the benefit taken is an absolute interest without conditions or restrictions.
You may only use this form if the property included in the return was taken from only one disponer and is not part of a larger benefit or series of benefits taken by a beneficiary on the same day. In all other situations the return must be made in electronic form.
A return of Capital Acquisitions Tax may be made in electronic form using Revenue's Online Service.
1. Beneficiary details and 2. Filer details
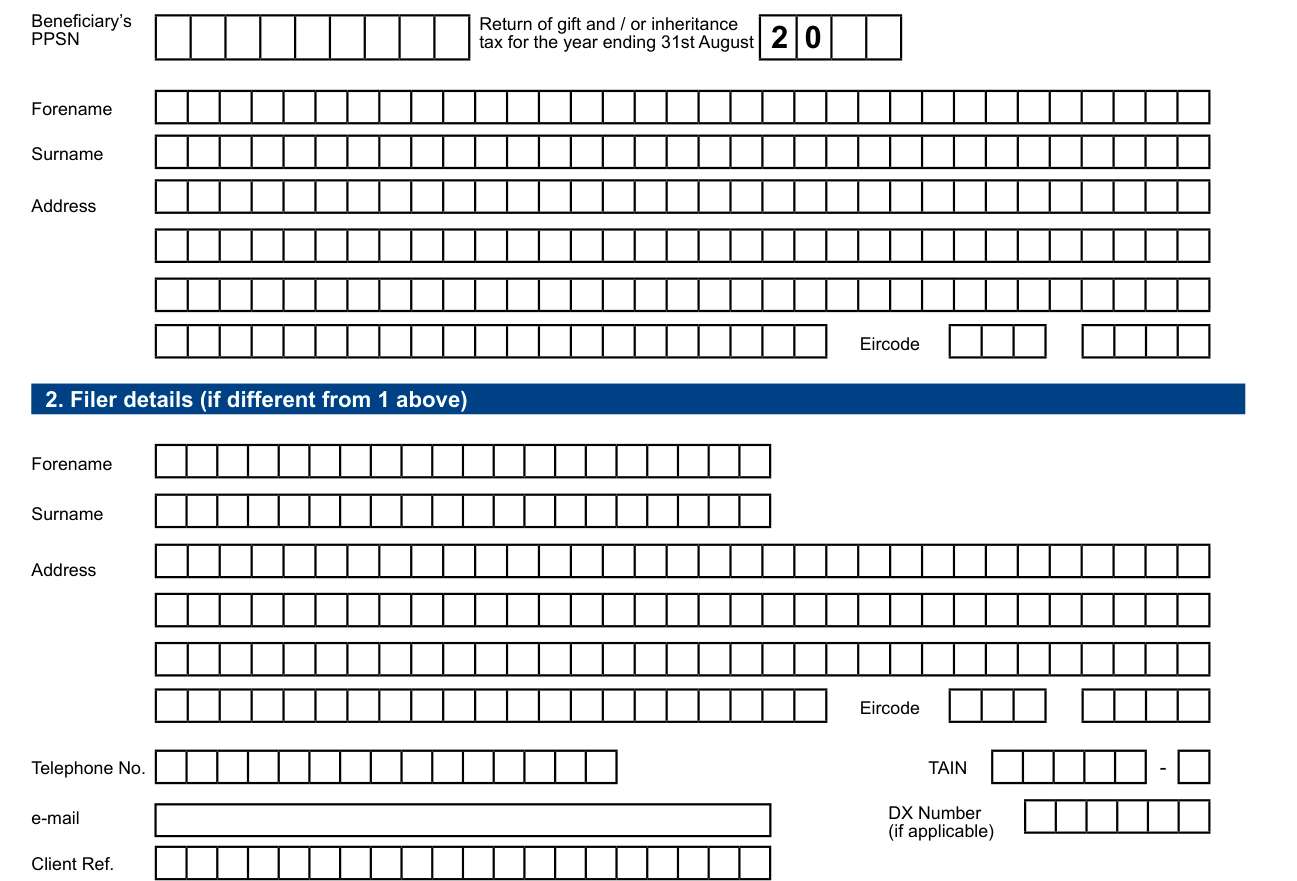
Complete this form in BLOCK CAPITALS in BLUE INK. Enter all considerations in WHOLE EURO ONLY and do not enter cent.
Under 1. Beneficiary details, enter the Beneficiary's PPSN and the year ending 31st August for the return of gift and / or inheritance tax.
Enter the Forename, Surname, Address and Eircode.
Under 2. Filer details (if different from 1. Beneficiary details), enter the Forename, Surname, Address and Eircode, then the Telephone No., TAIN, DX Number (if applicable), e-mail and Client Ref.
Disponer details
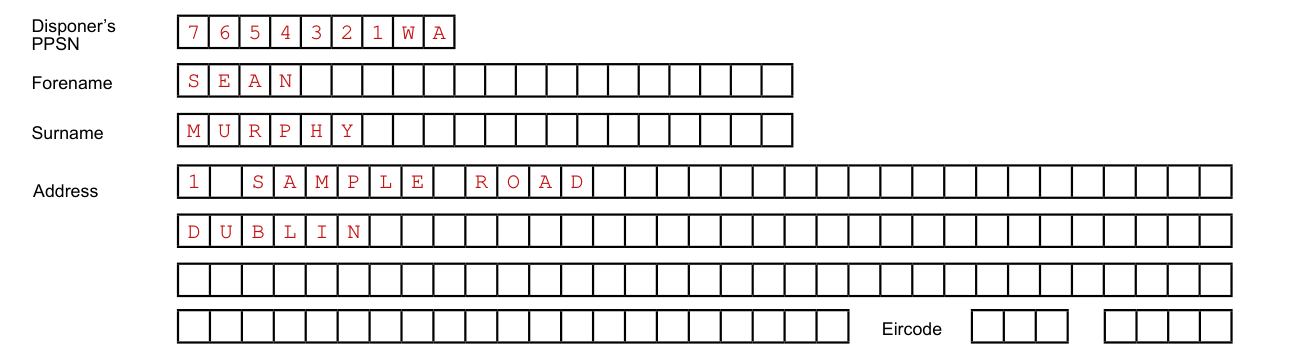
Enter the Beneficiary's PPSN and Year, then the Disponer's PPSN.
Under Disponer details, enter the Forename, Surname, Address and Eircode.
The nature of the benefit, the dates and the Group Threshold
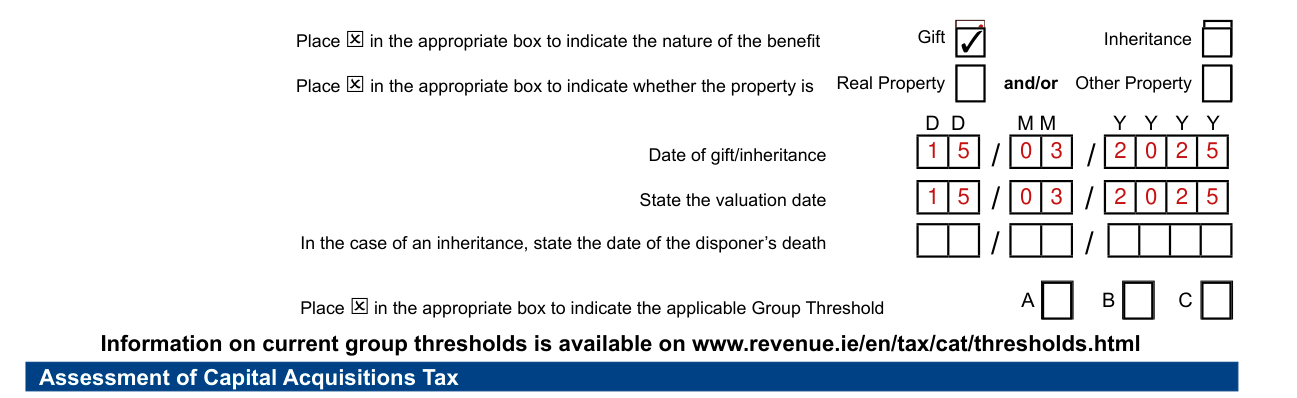
Place in the appropriate box to indicate the nature of the benefit: Gift or Inheritance.
Place in the appropriate box to indicate whether the property is Real Property and/or Other Property.
Enter the Date of gift/inheritance.
State the valuation date.
In the case of an inheritance, state the date of the disponer's death.
Place in the appropriate box to indicate the applicable Group Threshold, A, B or C. Information on current group thresholds is available on www.revenue.ie/en/tax/cat/thresholds.html
Assessment of Capital Acquisitions Tax
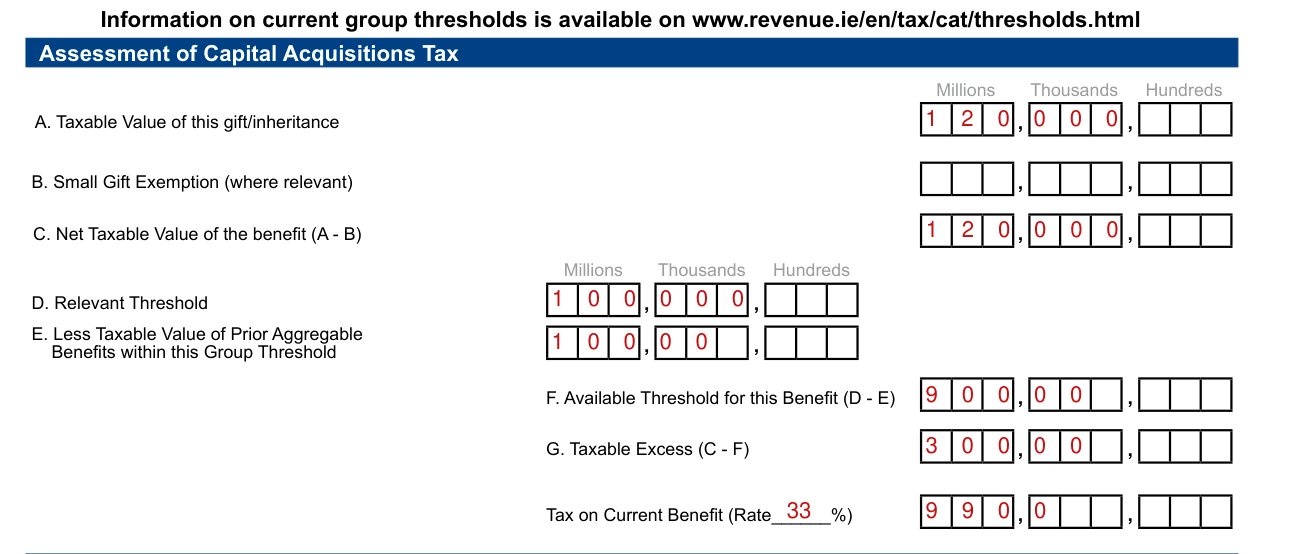
In the Assessment of Capital Acquisitions Tax, on line A, enter the Taxable Value of this gift/inheritance.
On line B, enter the Small Gift Exemption (where relevant).
On line C, enter the Net Taxable Value of the benefit (A - B).
On line D, enter the Relevant Threshold.
On line E, enter the Less Taxable Value of Prior Aggregable Benefits within this Group Threshold.
On line F, enter the Available Threshold for this Benefit (D - E).
On line G, enter the Taxable Excess (C - F).
Enter the Tax on Current Benefit, filling in the Rate.
DECLARATION

Sign under DECLARATION that the information given is true and complete and that the return is in accordance with the provisions of the Capital Acquisitions Tax Consolidation Act, 2003.
Enter the Date and the Capacity (Agent/beneficiary/trustee, etc.).
How to complete the payslip
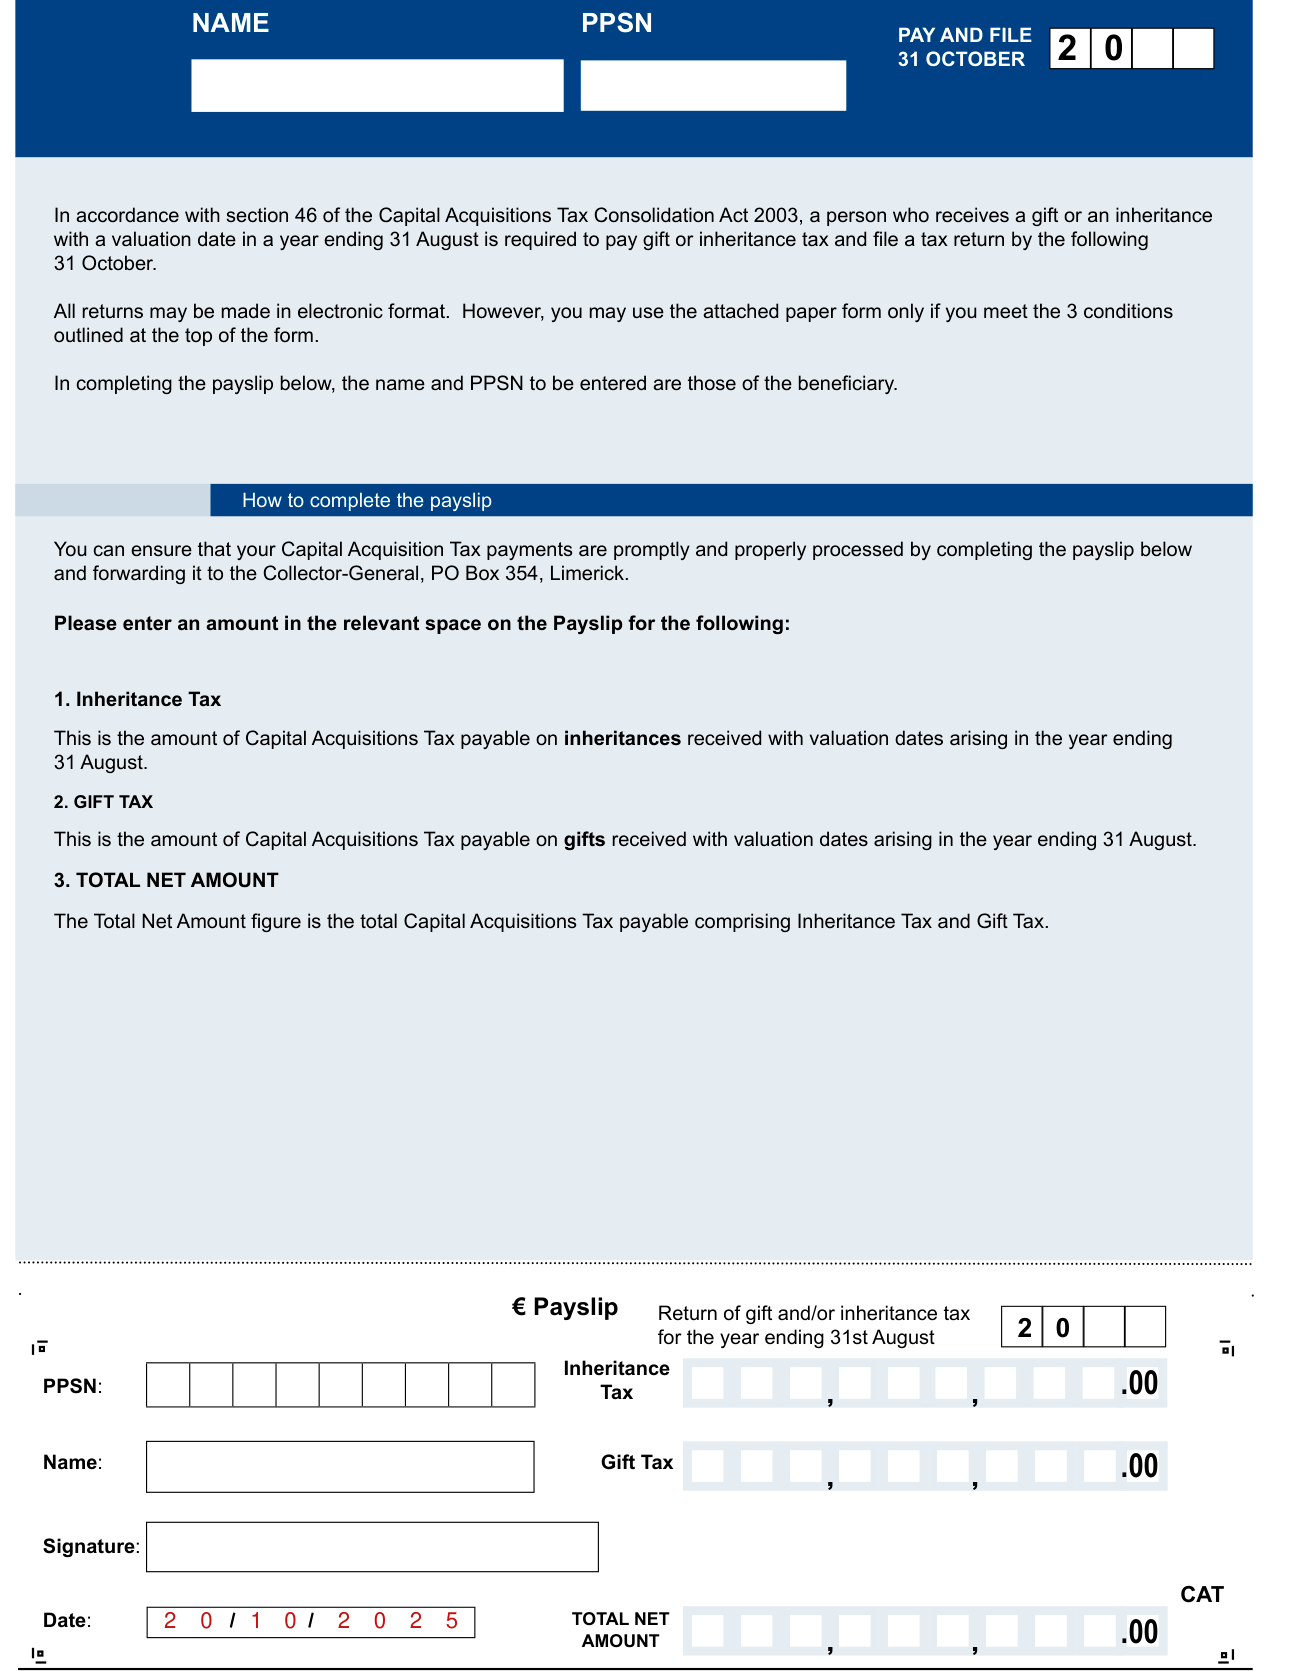
In completing the payslip, the name and PPSN to be entered are those of the beneficiary.
Enter in 1. Inheritance Tax the amount of Capital Acquisitions Tax payable on inheritances received with valuation dates arising in the year ending 31 August.
Enter in 2. GIFT TAX the amount of Capital Acquisitions Tax payable on gifts received with valuation dates arising in the year ending 31 August.
Enter in 3. TOTAL NET AMOUNT the total Capital Acquisitions Tax payable comprising Inheritance Tax and Gift Tax.
More rules for Form IT38S
YOU MUST KEEP RECORDS FOR A PERIOD OF SIX YEARS AS YOU MAY BE ASKED TO SUBMIT THEM IF YOUR RETURN IS CHOSEN FOR DETAILED EXAMINATION.
Make sure that you allow sufficient time, at least three working days, for your payment to reach the Collector-General by the due date. Late payment of tax carries an interest charge.
All cheques should be made payable to the Collector-General and forwarded with the completed payslip.
Do not enclose cash.
Common questions about Form IT38S
Is there a deadline?
In accordance with section 46 of the Capital Acquisitions Tax Consolidation Act 2003, a person who receives a gift or an inheritance with a valuation date in a year ending 31 August is required to pay gift or inheritance tax and file a tax return by the 31 October after it.
Where do I file it?
Return the payslip with a payment to: COLLECTOR-GENERAL, PO BOX 354, LIMERICK.
Is there a penalty?
YOU MAY BE LIABLE TO PENALTIES AND / OR PROSECUTION IF YOU FAIL TO MAKE A TRUE AND COMPLETE RETURN.
Sources
[1] Form IT38S (RPC014859_EN_WB_L_1), Revenue Commissioners (the Official source link on this page).