
Form T3012A at a glance
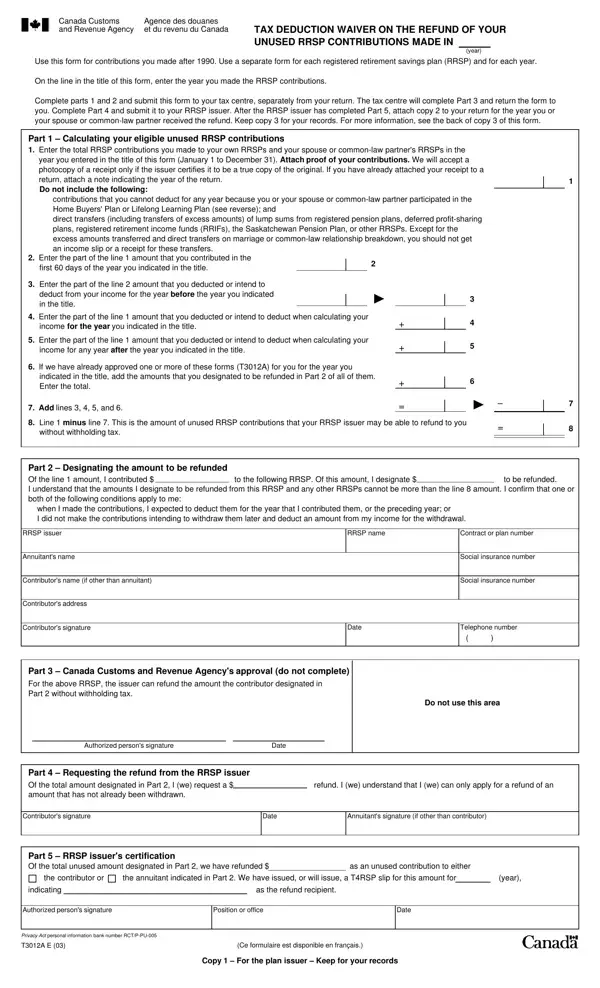
What it is: Form T3012A is the Tax Deduction Waiver on the Refund of Your Unused RRSP, PRPP, or SPP Contributions from Your RRSP, PRPP, or SPP.
Where and when to file: Fill in Parts 1 and 2 and send four copies of the form to your tax centre.
Use this form if you want the CRA to authorize your RRSP issuer, or PRPP or SPP administrator to refund your unused RRSP, PRPP or SPP contributions without withholding tax.
You have to meet all of the following conditions: You made the contributions to your own RRSP, PRPP, or SPP or your spouse's or common-law partner's RRSP or SPP, and you have not previously deducted them, or have not designated them as a repayment under the Home Buyers' Plan or the Lifelong Learning Plan.
You have not designated the refund as a qualifying withdrawal to have your past-service pension adjustment certified.
No part of the refund relates to a lump-sum payment from an RPP, a PRPP, or an SPP, or certain deferred profit sharing plan amounts, that were transferred directly to an RRSP, a PRPP, or an SPP.
You or your spouse or common-law partner will receive the refund of contributions from an RRSP, PRPP or SPP in one of the following years: the year you made the contributions; the following year; the year that the CRA sent you a notice of assessment or reassessment for the year you made the contributions, or the following year.
In addition, it has to be reasonable for the CRA to consider that at least one of these conditions applies: you reasonably expected to be able to fully deduct the RRSP, PRPP, and SPP contributions for the year you made the contributions or the immediately preceding year; you did not make the RRSP, PRPP, or SPP contributions intending to withdraw them and deduct an amount from your income for the withdrawal.
If you have already withdrawn your unused RRSP, PRPP or SPP contribution without using this form, use Form T746 to calculate the amount you can deduct.
A filled-in Form T3012A example: a contributor asks for a refund of unused contributions
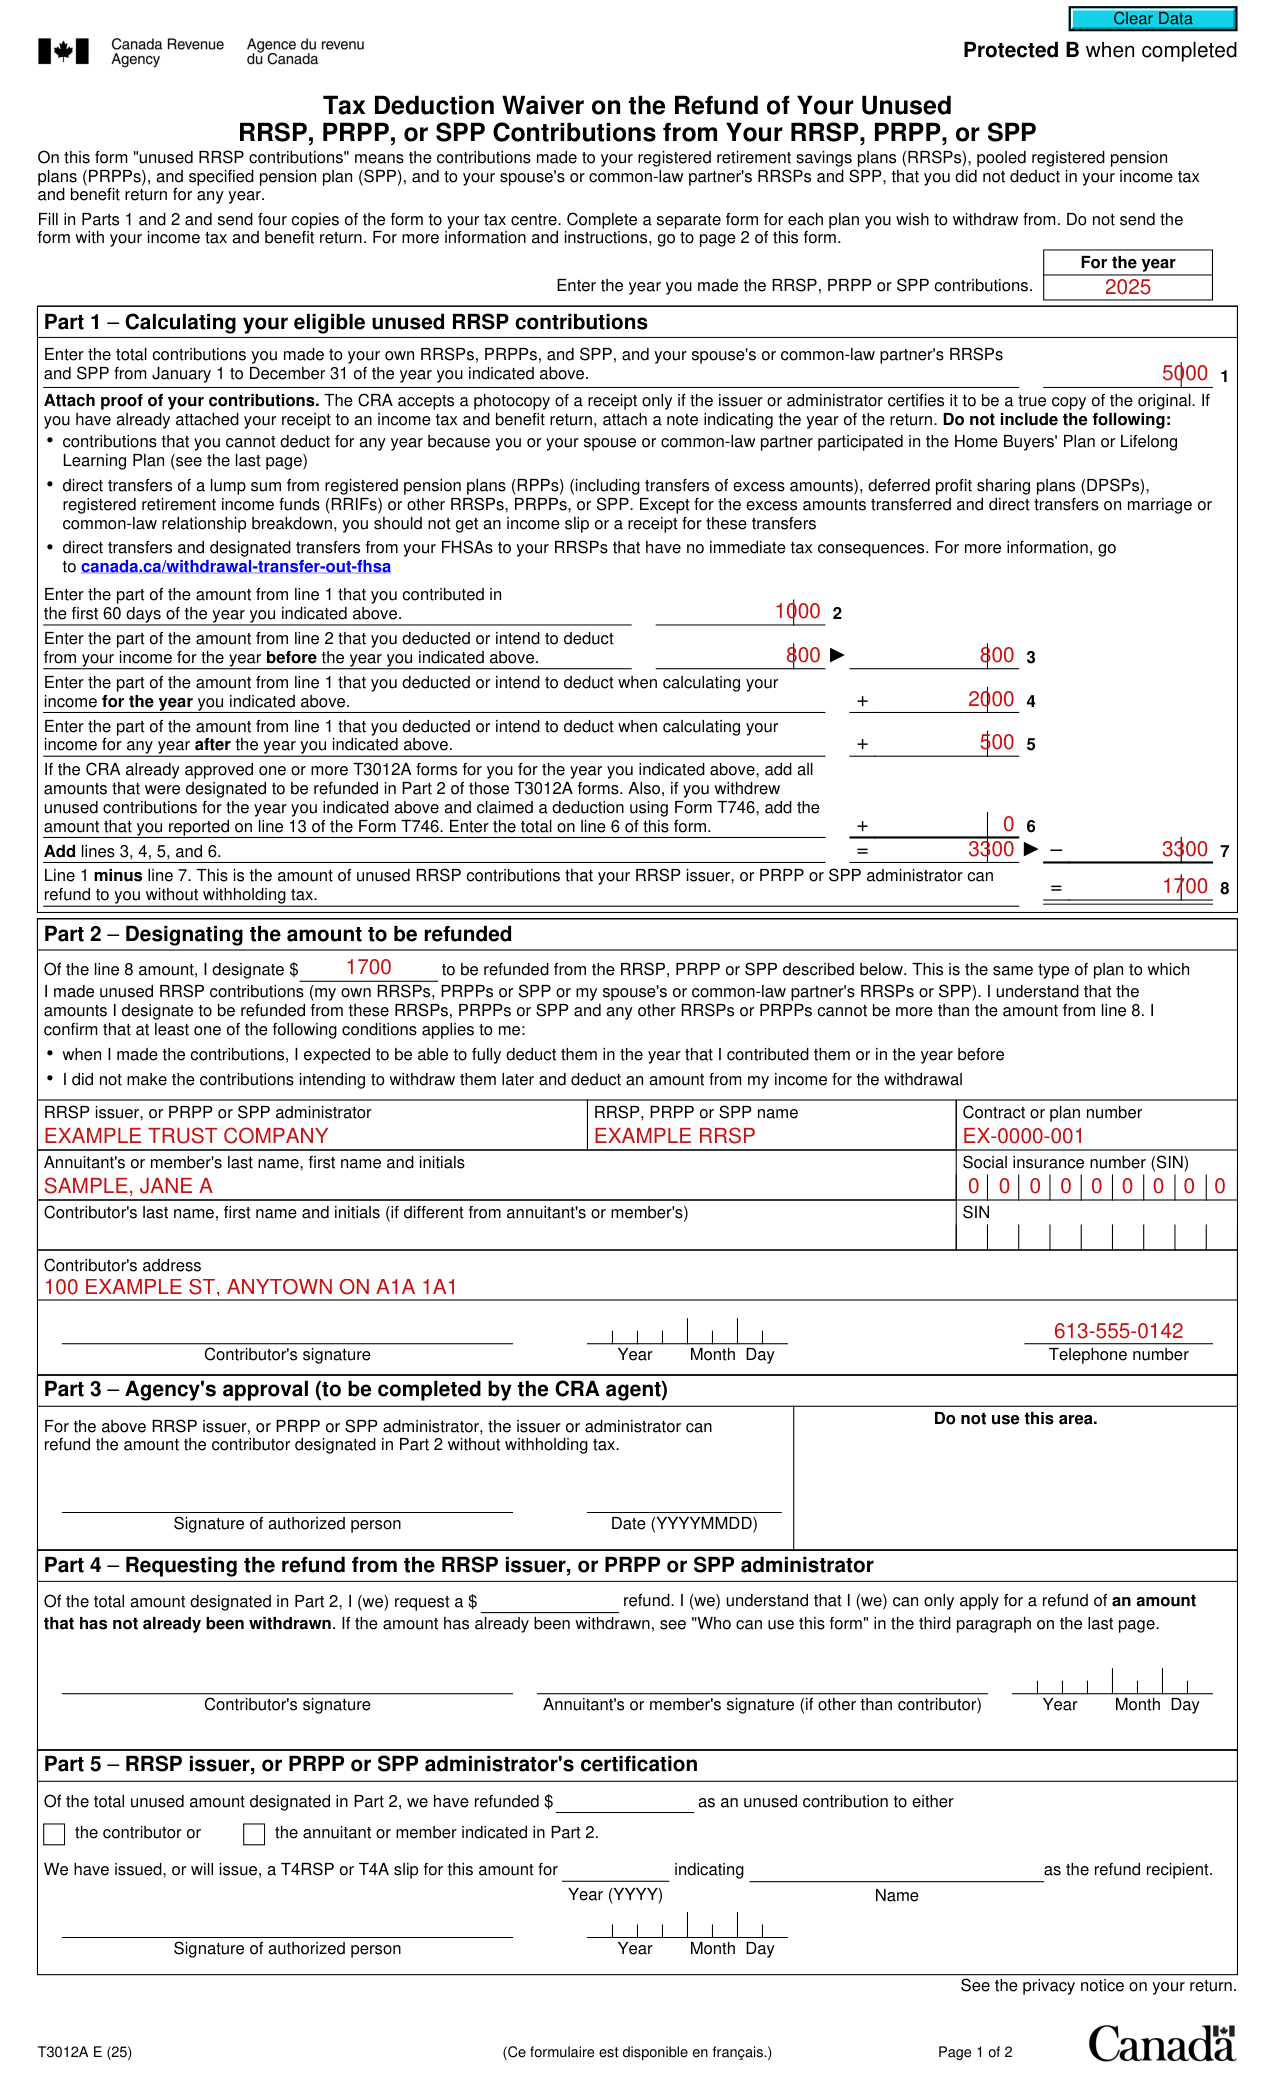
How to fill out Form T3012A, box by box
Part 1 - Calculating your unused RRSP contributions
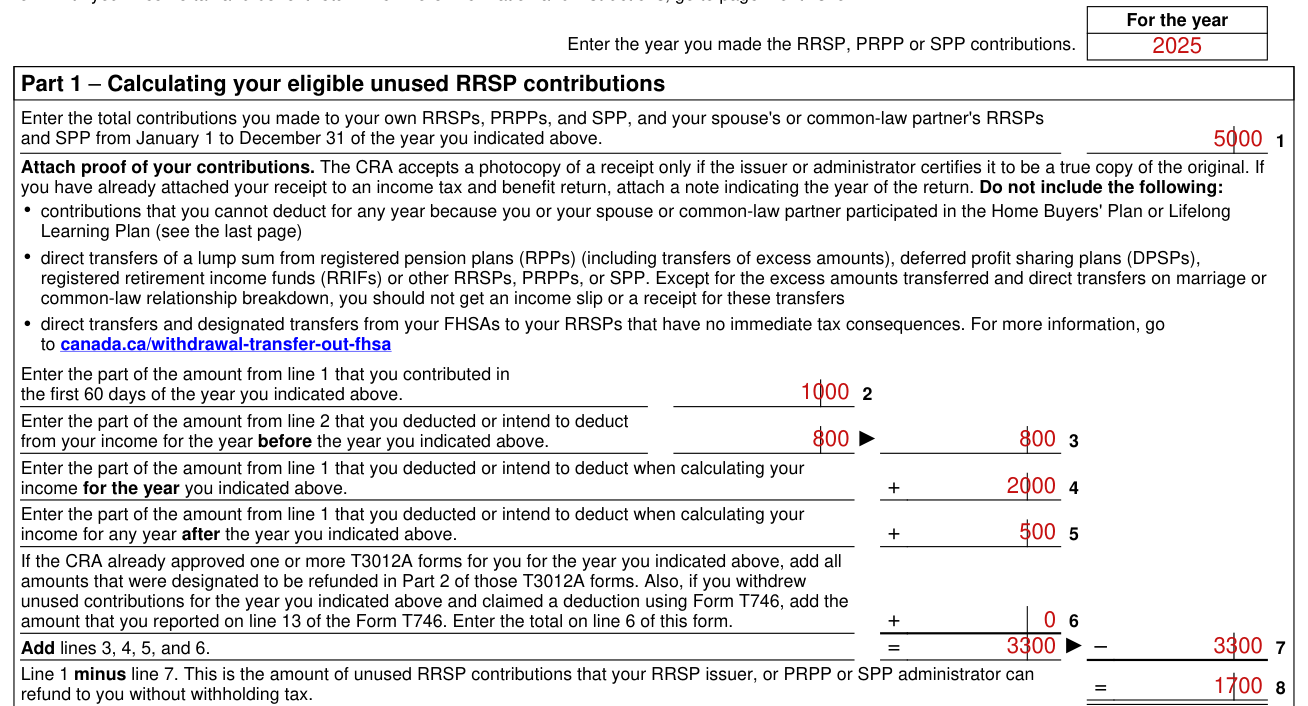
For the year, enter the year you made the RRSP, PRPP or SPP contributions.
Line 1: enter the total contributions you made to your own RRSPs, PRPPs, and SPP, and your spouse's or common-law partner's RRSPs and SPP from January 1 to December 31 of that year.
Attach proof of your contributions. The CRA accepts a photocopy of a receipt only if the issuer or administrator certifies it to be a true copy of the original. If you have already attached your receipt to an income tax and benefit return, attach a note indicating the year of the return. Do not include the following:
Contributions that you cannot deduct for any year because you or your spouse or common-law partner participated in the Home Buyers' Plan or Lifelong Learning Plan. Direct transfers of a lump sum from registered pension plans (RPPs) (including transfers of excess amounts), deferred profit sharing plans (DPSPs), registered retirement income funds (RRIFs) or other RRSPs, PRPPs, or SPP. Except for the excess amounts transferred and direct transfers on marriage or common-law relationship breakdown, you should not get an income slip or a receipt for these transfers. Direct transfers and designated transfers from your FHSAs to your RRSPs that have no immediate tax consequences.
Parts 1 and 2, line 1: if you contribute to an RRSP in the 89-day period before you or your spouse or common-law partner make a withdrawal under the Lifelong Learning Plan or Home Buyers' Plan, you may not be able to deduct the contribution from your income for any year. Do not include these contributions on line 1.
Line 2: enter the part of the amount from line 1 that you contributed in the first 60 days of that year.
Line 3: enter the part of the amount from line 2 that you deducted or intend to deduct from your income for the year before that year.
Line 4: enter the part of the amount from line 1 that you deducted or intend to deduct when calculating your income for that year.
Line 5: enter the part of the amount from line 1 that you deducted or intend to deduct when calculating your income for any year after that year.
Line 6: if the CRA already approved one or more T3012A forms for you for that year, add all amounts that were designated to be refunded in Part 2 of those T3012A forms. Also, if you withdrew unused contributions for that year and claimed a deduction using Form T746, add the amount that you reported on line 13 of the Form T746. Enter the total on line 6 of this form.
Line 7: add lines 3, 4, 5, and 6.
Line 8: line 1 minus line 7. This is the amount of unused RRSP contributions that your RRSP issuer, or PRPP or SPP administrator can refund to you without withholding tax.
Part 2 - Designating the amount to be refunded
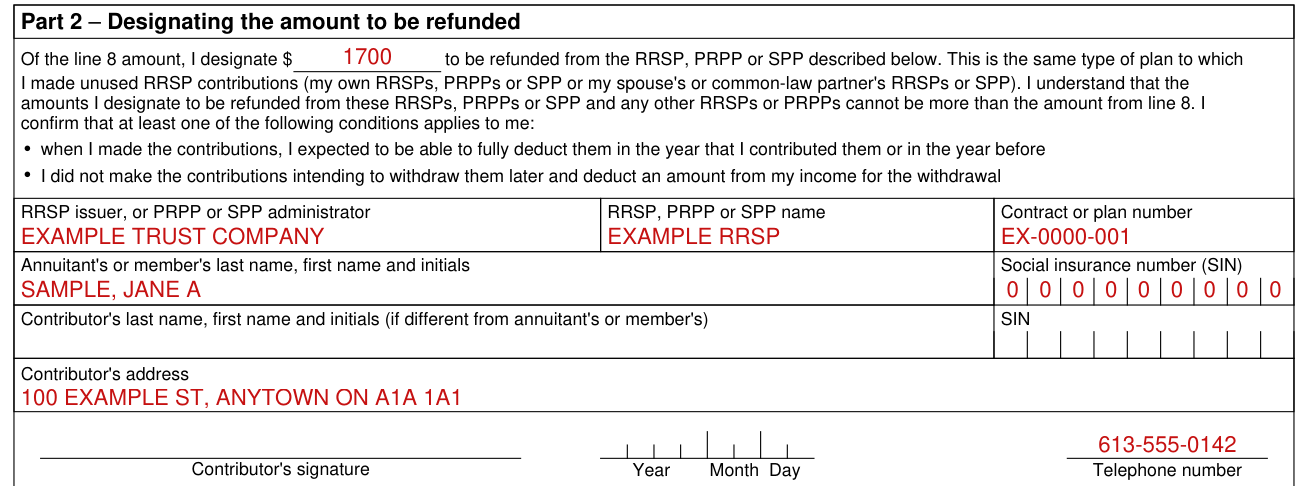
Of the line 8 amount, enter the amount to be designated for refund from the RRSP, PRPP or SPP described below. This is the same type of plan to which you made unused RRSP contributions. The amounts designated to be refunded from these RRSPs, PRPPs or SPP and any other RRSPs or PRPPs cannot be more than the amount from line 8. You confirm that at least one of the conditions applies.
Enter the RRSP issuer, or PRPP or SPP administrator, the RRSP, PRPP or SPP name and the Contract or plan number. Enter the annuitant's or member's last name, first name and initials and Social insurance number (SIN).
Enter the contributor's last name, first name and initials (if different from annuitant's or member's), the SIN, and the contributor's address.
Sign as the contributor and enter the Year Month Day and the Telephone number.
Part 4 - Requesting the refund from the RRSP issuer, or PRPP or SPP administrator
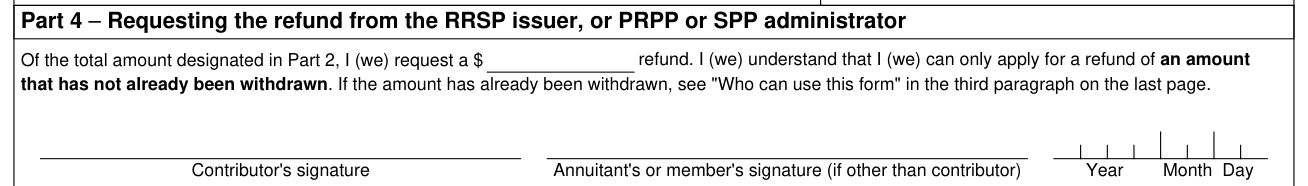
Of the total amount designated in Part 2, enter the refund you request. You can only apply for a refund of an amount that has not already been withdrawn. If the amount has already been withdrawn, see "Who can use this form" on the last page.
Sign as the contributor, and the annuitant or member signs if other than the contributor, with the Year Month Day.
Part 4: After the CRA has filled in Part 3 and returned the form to you, fill in Part 4 and send all three copies to your plan issuer or administrator.
If your situation is different
Do not use this form: situations for the individual receiving the refund
Do not use this form if any of the following situations apply to the individual who is receiving the refund (you or your spouse or common-law partner): a) you received the unused RRSP, PRPP, or SPP contributions in the form of a commutation payment from a matured RRSP b) you received or will receive a RRIF payment that is more than the minimum amount for the year, and the payment is for unused RRSP, PRPP, or SPP contributions that were transferred to the RRIF c) an RPP excess amount was transferred to an RRSP, PRPP, SPP, or a RRIF in the year or a previous year, and you are now withdrawing some or all of this amount from your RRSP, PRPP, SPP, or RRIF
Send the completed form and all supporting documents to your tax centre
Send the completed form and all supporting documents to your tax centre as indicated on your notice of assessment. Canada Revenue Agency Jonquière Tax Centre Pension Workflow Team 2251 René-Lévesque Boulevard Jonquière QC G7S 5J2. Canada Revenue Agency Sudbury Tax Centre Pension Workflow Team Post Office Box 20000, Station A Sudbury ON P3A 5C1. Canada Revenue Agency Winnipeg Tax Centre Pension Workflow Team Post Office Box 14000, Station Main Winnipeg MB R3C 3M2.
Sources
[1] Form T3012A E (25), Tax Deduction Waiver on the Refund of Your Unused RRSP, PRPP, or SPP Contributions from Your RRSP, PRPP, or SPP, Canada Revenue Agency (the Official source link on this page).