
Form W-4S at a glance
What it is: Form W-4S is the Request for Federal Income Tax Withholding From Sick Pay, which you give to the third-party payer of your sick pay if you want federal income tax withheld from the payments.
Who signs: Form W-4S is not valid unless you sign it.
Where and when to file: Give this form to the third-party payer of your sick pay.
Give this form to the third-party payer of your sick pay, such as an insurance company, if you want federal income tax withheld from the payments.
You aren't required to have federal income tax withheld from sick pay paid by a third party.
Sick pay is a payment that you receive under a plan to which your employer is a party, and in place of wages for any period when you're temporarily absent from work because of your sickness or injury.
If you receive sick pay under a collective bargaining agreement, see your union representative or employer.
A filled-in Form W-4S example: an unmarried employee sets her withholding
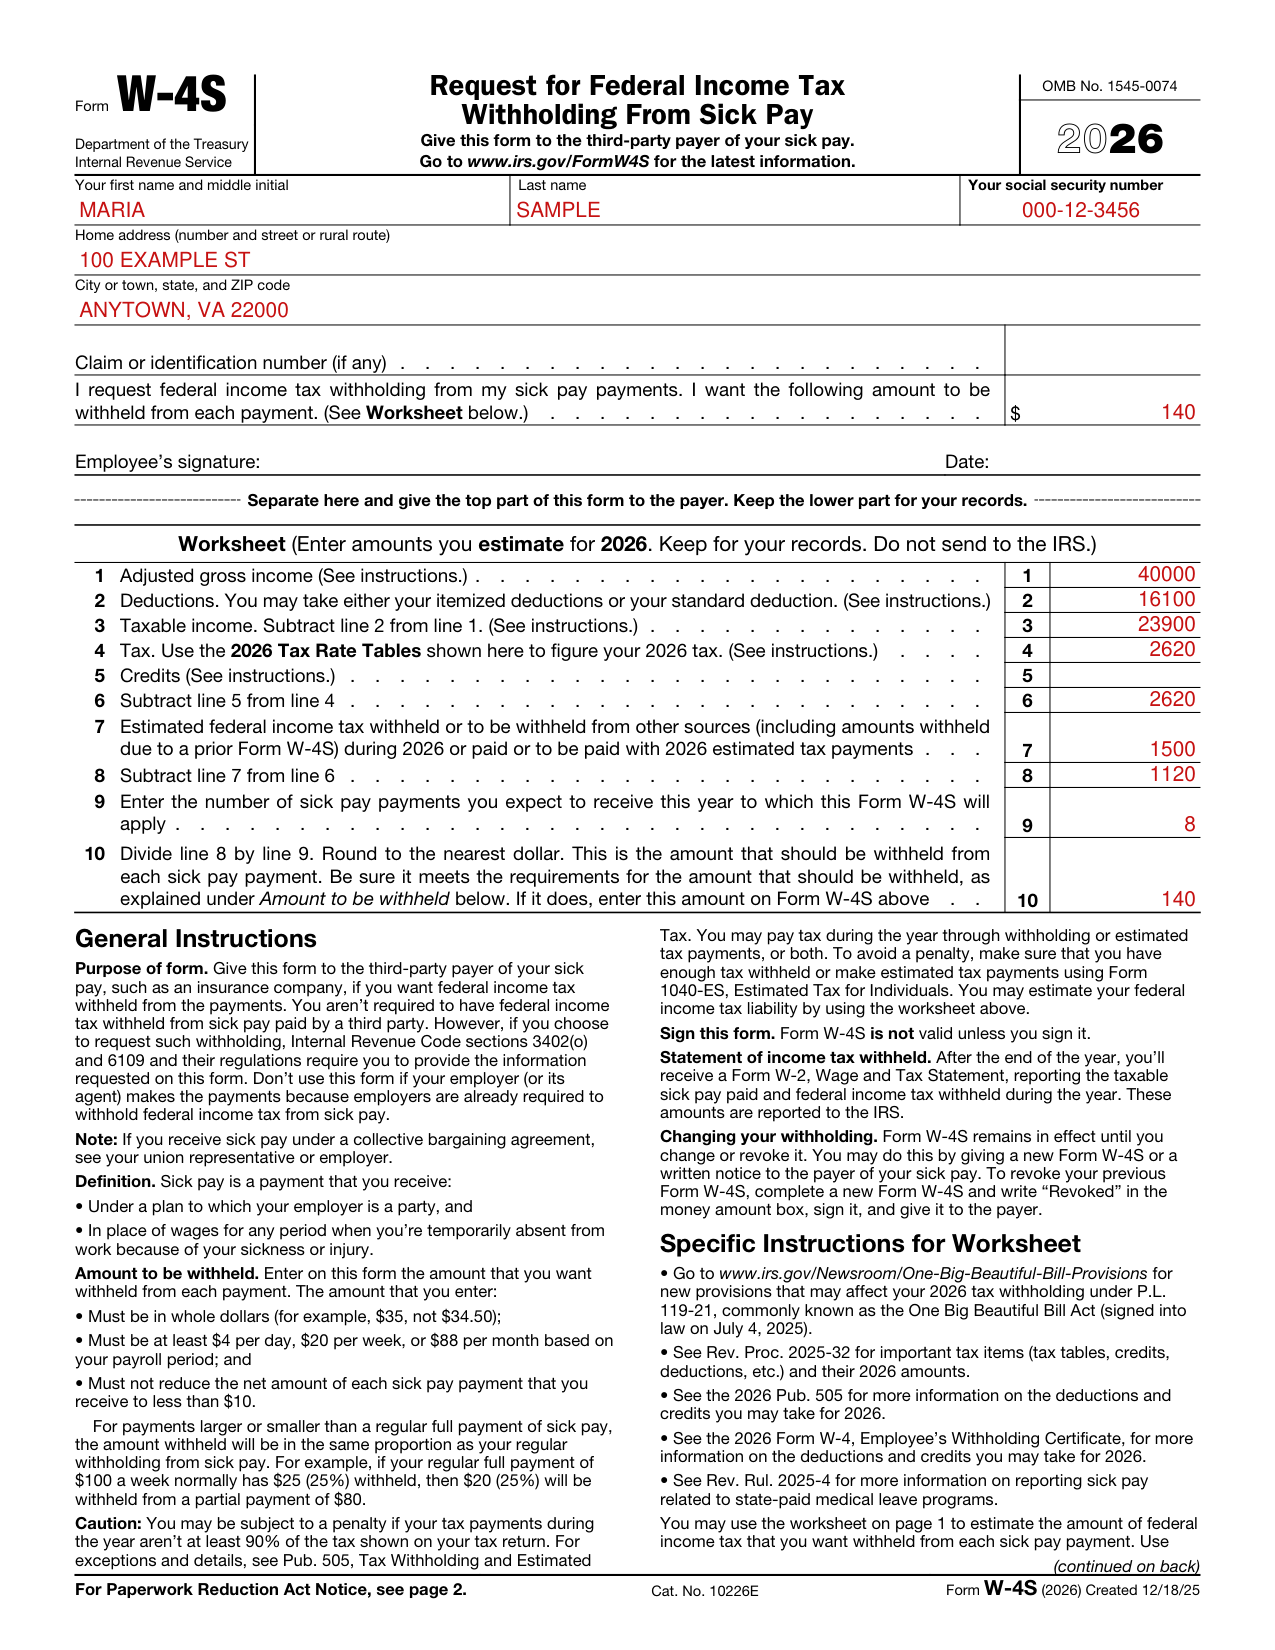
How to fill out Form W-4S, box by box
Your name, address and social security number
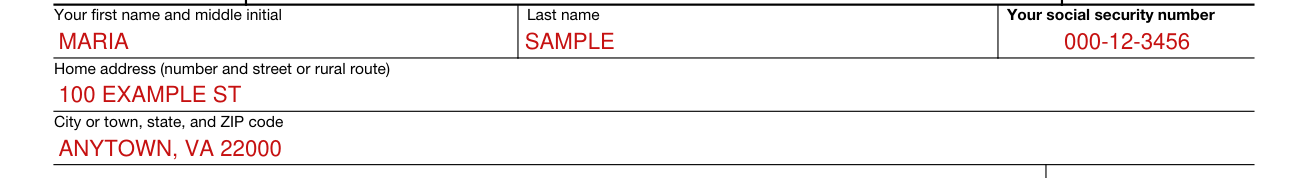
Enter your first name and middle initial, your last name and your social security number.
Enter your home address (number and street or rural route).
Enter your city or town, state, and ZIP code.
Claim or identification number (if any)

Enter your claim or identification number, if any.
Amount to withhold from each payment

Enter the amount that you want withheld from each payment. (See Worksheet.)
The amount that you enter must be in whole dollars (for example, $35, not $34.50). (checked November 8, 2026)
The amount that you enter must be at least $4 per day, $20 per week, or $88 per month based on your payroll period, and must not reduce the net amount of each sick pay payment that you receive to less than $10. (checked November 8, 2026)
Sign under Employee's signature and enter the Date.
Worksheet
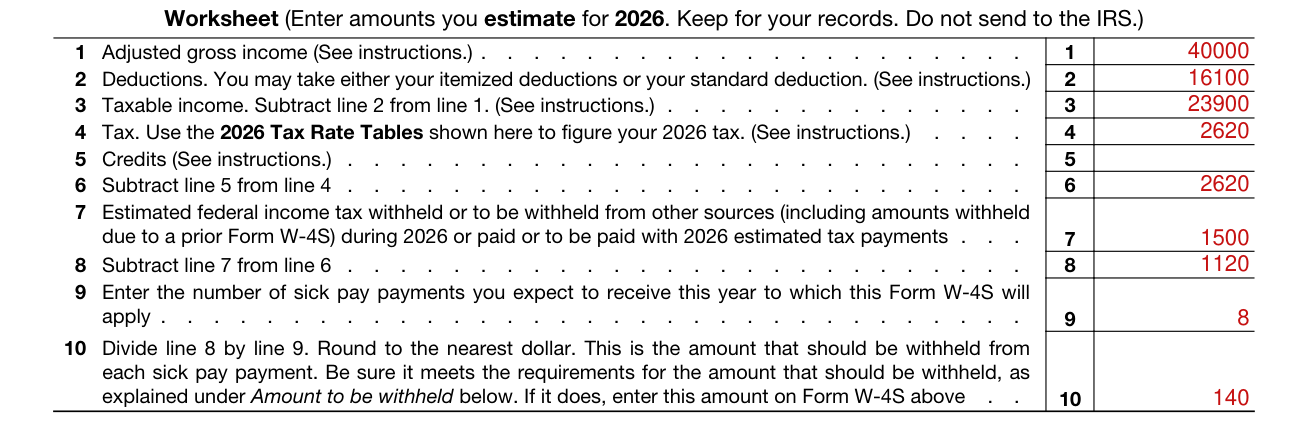
On the Worksheet, enter amounts you estimate for 2026. Keep it for your records. Do not send it to the IRS.
On line 1, enter your Adjusted gross income (See instructions.)
On line 2, enter Deductions. You may take either your itemized deductions or your standard deduction. (See instructions.)
Miscellaneous itemized deductions are no longer allowed. Regular itemized deductions may be reduced for individuals with taxable income in the 37% rate bracket.
For tax years beginning in 2026, the standard deduction is $32,200 for married individuals filing joint returns and surviving spouses, $24,150 for heads of households, $16,100 for unmarried individuals (other than surviving spouses and heads of households) and $16,100 for married individuals filing separate returns. (checked November 8, 2026)
On line 3, enter Taxable income. Subtract line 2 from line 1. (See instructions.)
On line 4, enter Tax. Use the 2026 Tax Rate Tables shown here to figure your 2026 tax. (See instructions.)
For Unmarried Individuals (Other Than Surviving Spouses and Heads of Households): If taxable income is not over $12,400: the tax is 10% of the taxable income. If taxable income is over $12,400 but not over $50,400: the tax is $1,240 plus 12% of the excess over $12,400. If taxable income is over $50,400 but not over $105,700: the tax is $5,800 plus 22% of the excess over $50,400. If taxable income is over $105,700 but not over $201,775: the tax is $17,966 plus 24% of the excess over $105,700. If taxable income is over $201,775 but not over $256,225: the tax is $41,024 plus 32% of the excess over $201,775. If taxable income is over $256,225 but not over $640,600: the tax is $58,448 plus 35% of the excess over $256,225. If taxable income is over $640,600: the tax is $192,979.25 plus 37% of the excess over $640,600. (checked November 8, 2026)
On line 5, enter Credits (See instructions.)
On line 5, include any tax credits that you're entitled to claim, such as the child tax credit and credit for other dependents, higher education credits, credit for child and dependent care expenses, earned income credit, or credit for the elderly or the disabled.
On line 6, subtract line 5 from line 4.
On line 7, enter Estimated federal income tax withheld or to be withheld from other sources (including amounts withheld due to a prior Form W-4S) during 2026 or paid or to be paid with 2026 estimated tax payments.
On line 7, enter the federal income tax that you expect will be withheld this year on income other than sick pay and any payments made or to be made with 2026 estimated tax payments. Include any federal income tax already withheld or to be withheld from wages and pensions.
On line 8, subtract line 7 from line 6.
On line 9, enter the number of sick pay payments you expect to receive this year to which this Form W-4S will apply.
If you expect to file a joint return, be sure to include the income, deductions, credits, and payments of both yourself and your spouse in figuring the amount you want withheld.
On line 10, divide line 8 by line 9. Round to the nearest dollar. This is the amount that should be withheld from each sick pay payment. Be sure it meets the requirements for the amount that should be withheld, as explained under Amount to be withheld. If it does, enter this amount on Form W-4S.
More rules for Form W-4S
Separate here and give the top part of this form to the payer. Keep the lower part for your records.
Form W-4S remains in effect until you change or revoke it. You may do this by giving a new Form W-4S or a written notice to the payer of your sick pay.
To revoke your previous Form W-4S, complete a new Form W-4S and write “Revoked” in the money amount box, sign it, and give it to the payer.
You may not want to use Form W-4S if you already have your total tax covered by estimated tax payments or other withholding.
If any of the amounts on the worksheet change after you give Form W-4S to the payer, you should use a new Form W-4S to request a change in the amount withheld.
After the end of the year, you'll receive a Form W-2, Wage and Tax Statement, reporting the taxable sick pay paid and federal income tax withheld during the year.
To avoid a penalty, make sure that you have enough tax withheld or make estimated tax payments using Form 1040-ES, Estimated Tax for Individuals.
For exceptions and details on the penalty for tax payments under 90% of the tax shown on your tax return, see Pub. 505.
If your situation is different
Your employer or its agent makes the payments
Don't use this form if your employer (or its agent) makes the payments because employers are already required to withhold federal income tax from sick pay.
Common questions about Form W-4S
Who signs it?
Form W-4S is not valid unless you sign it.
Is there a penalty?
You may be subject to a penalty if your tax payments during the year aren't at least 90% of the tax shown on your tax return.
Sources
[1] Form W-4S (2026, Rev. Proc. 2025), Request for Federal Income Tax Withholding From Sick Pay, Department of the Treasury Internal Revenue Service (the Official source link on this page).
