

Form WT-4A at a glance
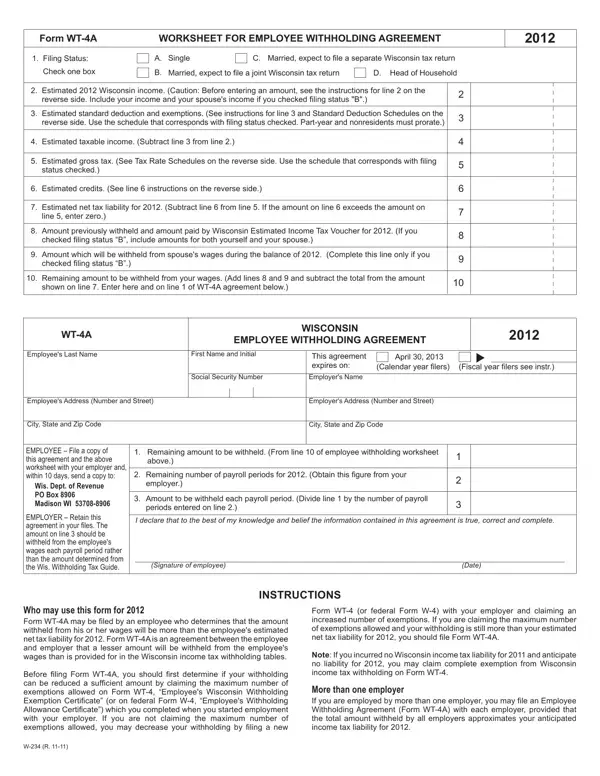
What it is: Form WT-4A for 2026 is an agreement between the employee and employer that a lesser amount will be withheld from the employee's wages than is provided for in the Wisconsin income tax withholding tables.
Where and when to file: EMPLOYEE: file a copy of the agreement and the worksheet with your employer and, within 10 days, send a copy to Wis. Dept. of Revenue, PO Box 8906, Madison WI 53708-8906.
Form WT-4A may be filed by an employee who determines that the amount withheld from their wages will be more than the employee's estimated net tax liability for 2026.
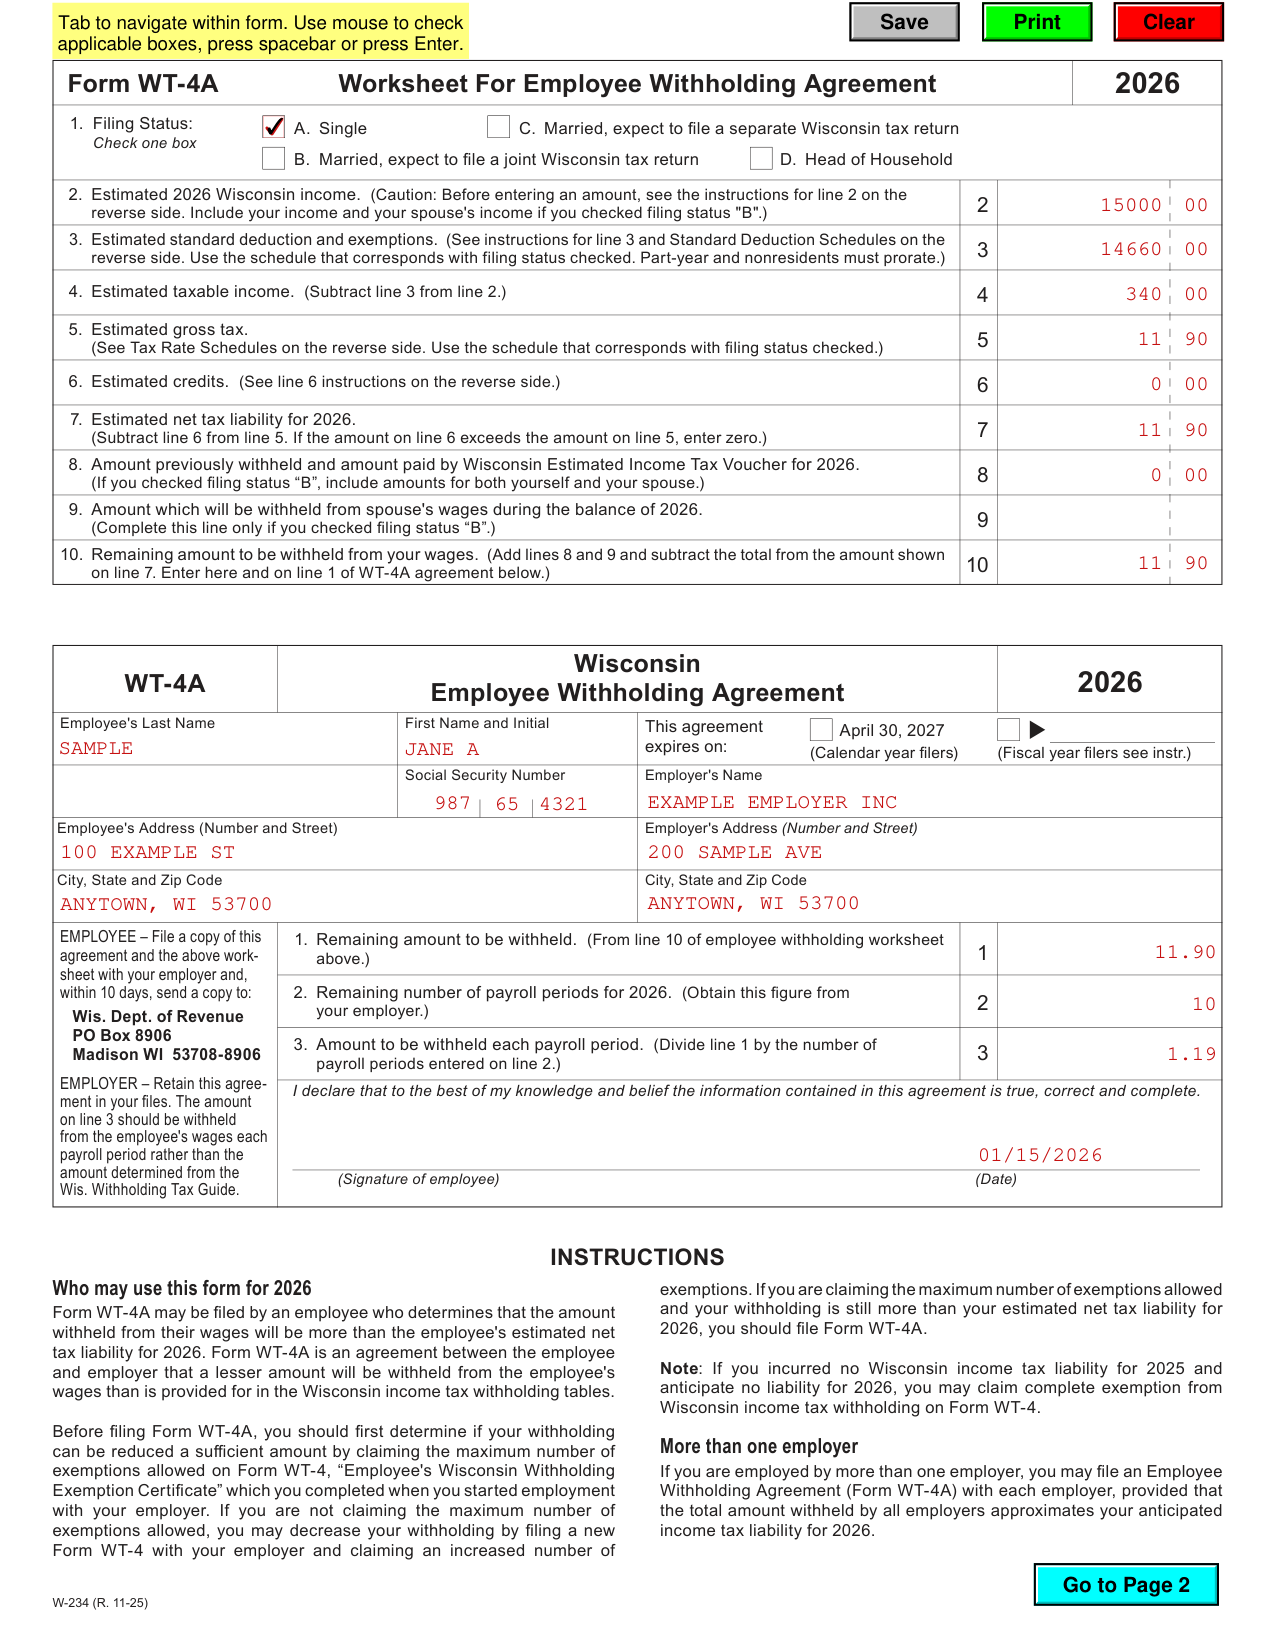
A filled-in Form WT-4A example: a single employee agrees to lower withholding
How to fill out Form WT-4A, box by box
1. Filing Status
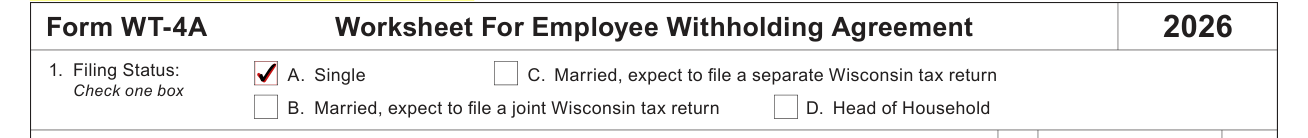
Under 1. Filing Status, check one box: A. Single, B. Married, expect to file a joint Wisconsin tax return, C. Married, expect to file a separate Wisconsin tax return, or D. Head of Household.
2. Estimated 2026 Wisconsin income

On line 2, enter the estimated 2026 Wisconsin income. Before entering an amount, see the instructions for line 2 on the reverse side. Include your income and your spouse's income if you checked filing status "B".
Refer to the Wisconsin income reported on line 7 of Form 1 or line 30 of Form 1NPR of your Wisconsin income tax return.
3. Estimated standard deduction and exemptions

On line 3, enter the estimated standard deduction and exemptions. See instructions for line 3 and Standard Deduction Schedules on the reverse side. Use the schedule that corresponds with filing status checked.
Your exemptions are $700 for yourself, $700 for your spouse if filing a joint return, and $700 for each dependent (checked October 22, 2026).
Add $250 to the total if you are 65 years of age or over and, add $250 if your spouse is 65 years of age or over (checked October 22, 2026).
If you are claimed as a dependent on someone else's return, you do not qualify for an exemption.
4. Estimated taxable income

On line 4, enter the estimated taxable income: subtract line 3 from line 2.
5. Estimated gross tax

On line 5, enter the estimated gross tax from the Tax Rate Schedules for the filing status checked.
6. Estimated credits

On line 6, enter the estimated credits. See line 6 instructions on the reverse side.
For line 6, refer to a 2025 Wisconsin Form 1, or Form 1NPR.
7. Estimated net tax liability for 2026

On line 7, enter the estimated net tax liability for 2026: subtract line 6 from line 5. If the amount on line 6 exceeds the amount on line 5, enter zero.
8. Amount previously withheld

On line 8, enter the amount previously withheld and amount paid by Wisconsin Estimated Income Tax Voucher for 2026. If you checked filing status "B", include amounts for both yourself and your spouse.
9. Amount withheld from spouse's wages

On line 9, enter the amount which will be withheld from spouse's wages during the balance of 2026. Complete this line only if you checked filing status "B".
10. Remaining amount to be withheld from your wages

On line 10, enter the remaining amount to be withheld from your wages: add lines 8 and 9 and subtract the total from the amount shown on line 7. Enter it here and on line 1 of the WT-4A agreement below.
Withholding Agreement: names and addresses
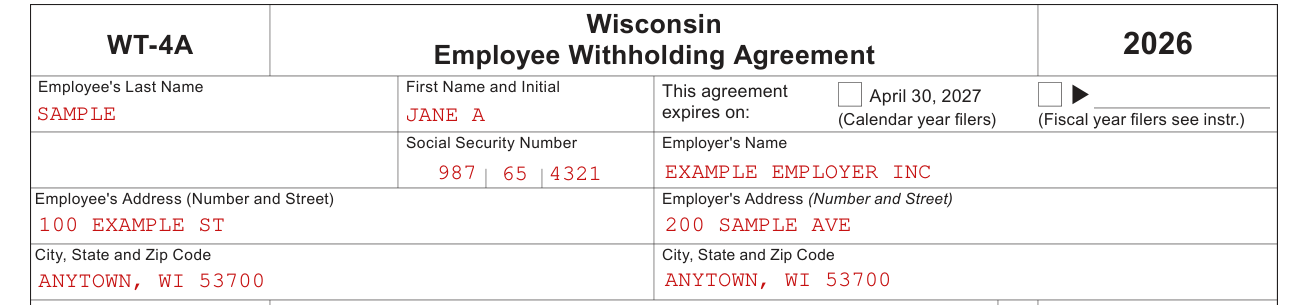
On the Employee Withholding Agreement, enter the Employee's Last Name, First Name and Initial, Social Security Number, Employer's Name, and the Employee's and Employer's Address (Number and Street) and City, State and Zip Code.
This agreement expires on
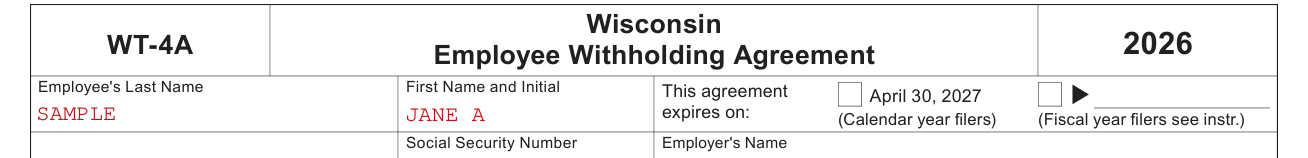
The agreement expires on April 30, 2027 (Calendar year filers) (Fiscal year filers see instr.).
Calendar year filers should place an "X" in the April 30, 2027 box on Form WT-4A.
For fiscal year filers, the agreement will expire on the last day of the fourth month following the close of their fiscal year. Fiscal year filers should enter the appropriate expiration date in the space provided on Form WT-4A and place an "X" in the box.
Withholding Agreement: lines 1 to 3
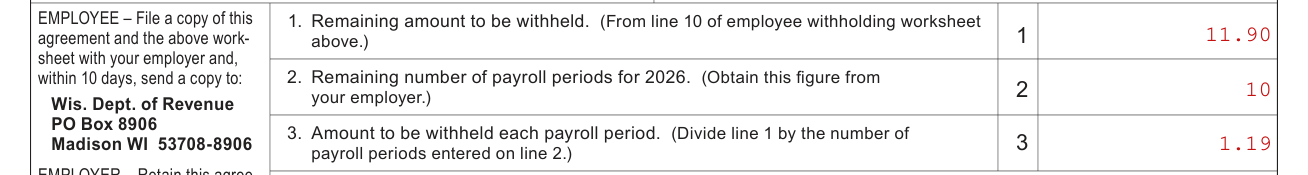
On line 1 of the agreement, enter the remaining amount to be withheld, from line 10 of the employee withholding worksheet.
On line 2 of the agreement, enter the remaining number of payroll periods for 2026, a figure to obtain from your employer.
On line 3 of the agreement, enter the amount to be withheld each payroll period: divide line 1 by the number of payroll periods entered on line 2.
Signature of employee and the copy

The employee declares that to the best of their knowledge and belief the information contained in the agreement is true, correct and complete, then enters the (Signature of employee) and the (Date).
Complete both the WT-4A worksheet and the withholding agreement. Provide one copy of the worksheet and the withholding agreement to your employer. Mail another copy to the Department of Revenue within 10 days after the WT-4A is filed with your employer.
Other situations
Before filing Form WT-4A
Before filing Form WT-4A, first determine if your withholding can be reduced a sufficient amount by claiming the maximum number of exemptions allowed on Form WT-4, "Employee's Wisconsin Withholding Exemption Certificate". If you are not claiming the maximum number of exemptions allowed, you may decrease your withholding by filing a new Form WT-4 with your employer and claiming an increased number of exemptions.
If you are claiming the maximum number of exemptions allowed and your withholding is still more than your estimated net tax liability for 2026, you should file Form WT-4A.
If you incurred no Wisconsin income tax liability for 2025 and anticipate no liability for 2026, you may claim complete exemption from Wisconsin income tax withholding on Form WT-4.
More than one employer
If you are employed by more than one employer, you may file an Employee Withholding Agreement (Form WT-4A) with each employer, provided that the total amount withheld by all employers approximates your anticipated income tax liability for 2026.
Nonresidents and part-year residents
Nonresidents and part-year residents prorate the standard deduction as follows: (1) Figure your standard deduction using your federal adjusted gross income instead of your Wisconsin income, and (2) prorate using the ratio of Wisconsin income to federal adjusted gross income. Exemptions must also be prorated using the same ratio.
How to amend your agreement
If you have already filed Form WT-4A and you have a substantial increase or decrease in your 2026 estimated tax liability, you should fill out a new Form WT-4A. Write the word "AMENDED" at the top of the new form.
File one copy of the amended Form WT-4A with your employer and mail one copy to the Department of Revenue within 10 days after it is filed with your employer.
Revocation of the agreement
If the department determines that the amount to be withheld per the Employee Withholding Agreement, Form WT-4A, is insufficient, the department may void the agreement by notification to the employer and employee.
Common questions about Form WT-4A
What is a wt 4A form in Wisconsin?
Form WT-4A for 2026 is an agreement between the employee and employer that a lesser amount will be withheld from the employee's wages than is provided for in the Wisconsin income tax withholding tables. EMPLOYER: retain the agreement in your files. The amount on line 3 should be withheld from the employee's wages each payroll period rather than the amount determined from the Wis. Withholding Tax Guide.
Is there a penalty?
If you do not send a copy of Form WT-4A (including the worksheet) to the department within 10 days, the law provides for a $10 penalty to be imposed against you (checked October 22, 2026). If an employee enters into an agreement with the intent to defeat or evade the proper withholding of tax, the employee will be subject to a penalty equal to the difference between the amount required to be withheld and the amount actually withheld for the period that the agreement was in effect. Any employee who willfully supplies an employer with false or fraudulent information regarding an Employee Withholding Agreement with the intent to defeat or evade the proper withholding of tax may be imprisoned not more than 6 months, or fined not more than $500 plus the cost of prosecution, or both (checked October 22, 2026).
Sources
[1] Form WT-4A (W-234, R. 11-25), Worksheet for Employee Withholding Agreement, Wisconsin Department of Revenue (the Official source link on this page).