

Form 149 at a glance
What it is: Form 149 is the Sales and Use Tax Exemption Certificate, on which you select the appropriate box for the type of exemption to be claimed and complete any additional information requested.
Who signs: The Purchaser or the Purchaser's Agent signs.
What to bring and attach to Form 149
For Common Carrier, attach completed Form 5095.
A filled-in Form 149 example: a Missouri retailer buys goods for resale
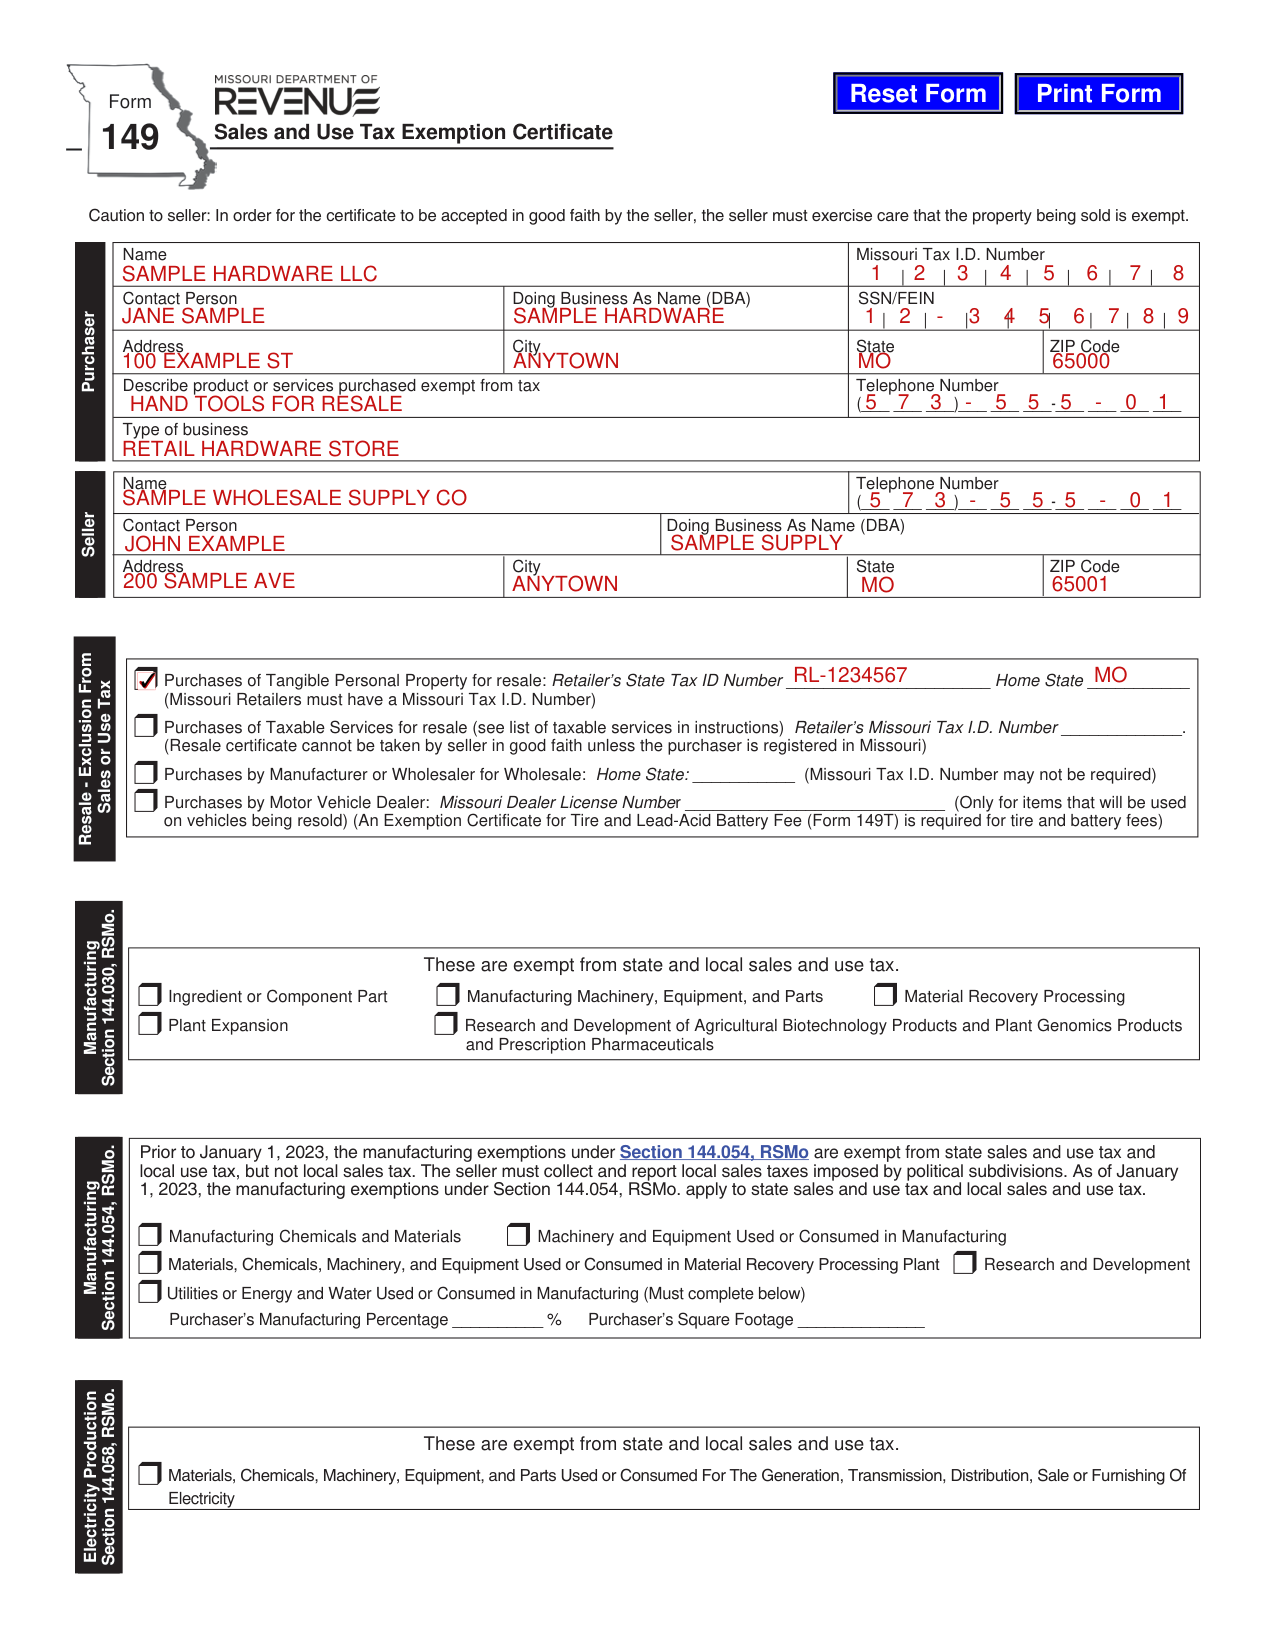
How to fill out Form 149, box by box
Purchaser
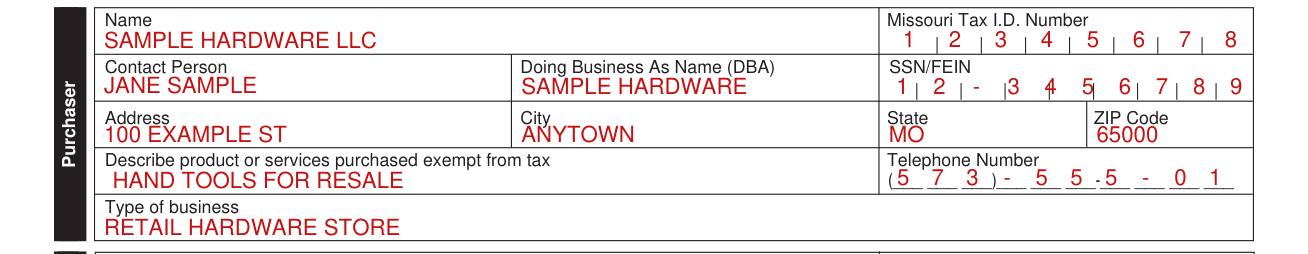
Enter the purchaser's Name and Missouri Tax I.D. Number.
Enter the purchaser's Contact Person, Doing Business As Name (DBA) and SSN/FEIN.
Enter the purchaser's Address, City, State and ZIP Code.
Describe the product or services purchased exempt from tax, and enter the purchaser's Telephone Number.
Enter the purchaser's Type of business.
Seller
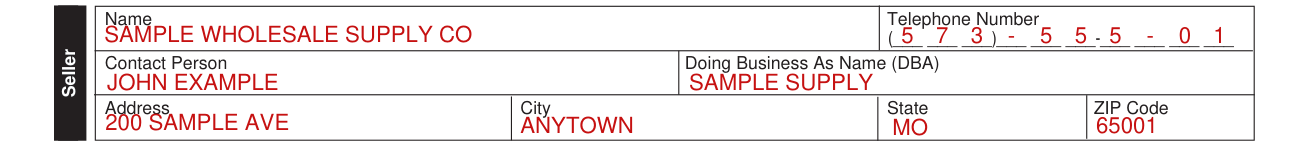
Enter the Seller's Name and Telephone Number.
Enter the Seller's Contact Person and Doing Business As Name (DBA).
Enter the Seller's Address, City, State and ZIP Code.
Resale, Exclusion From Sales or Use Tax
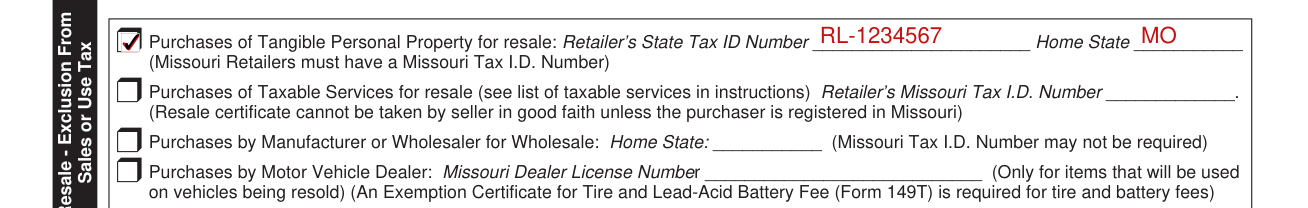
Purchases of Tangible Personal Property for resale: check the box, then enter the Retailer's State Tax ID Number and the Home State. Retailers that are purchasing tangible personal property for resale purposes are exempt from sales or use tax. Missouri Retailers must have a Missouri Tax I.D. Number.
The purchaser's state tax ID number can be found on the Missouri Retail License or out of state registration for retail sales.
Purchaser's Home State: Provide the state in which purchaser is located and registered.
Purchases of Taxable Services for resale: check the box and enter the Retailer's Missouri Tax I.D. Number. Purchasers for resale must have a Missouri retail license in order to claim resale of taxable services in Missouri.
For Purchases of Taxable Services for resale, a resale certificate cannot be taken by the seller in good faith unless the purchaser is registered in Missouri.
Purchases by Manufacturer or Wholesaler for Wholesale: check the box and enter the Home State. A Missouri Tax I.D. Number is not required to claim this exclusion.
Purchases by Motor Vehicle Dealer: check the box and enter the Missouri Dealer License Number. A motor vehicle dealer who is purchasing items for the repair of a vehicle being resold is exempt from sales or use tax.
For Purchases by Motor Vehicle Dealer, the exemption is only for items that will be used on vehicles being resold.
An Exemption Certificate for Tire and Lead-Acid Battery Fee (Form 149T) is required for tire and battery fees.
Manufacturing, Section 144.030, RSMo
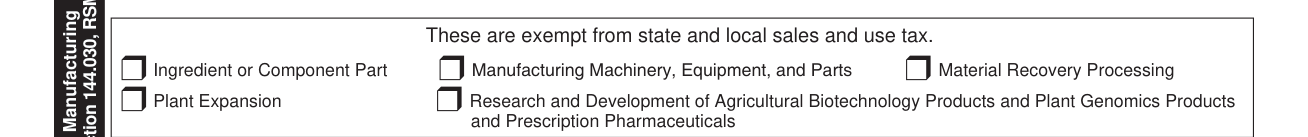
Check the appropriate box for the type of exemption to be claimed. All items selected in this Manufacturing section are exempt from state sales and use tax and local sales and use tax under Section 144.030, RSMo.
Ingredient or Component Parts: This exemption includes materials, manufactured goods, machinery, and parts that become a part of the final product. Manufacturing Machinery, Equipment and Parts: This exemption includes only machinery and equipment and their parts that are used directly in manufacturing a product. For both, to qualify, the product must ultimately be subject to sales or use tax, or its equivalent, in Missouri or other states.
Material Recovery Processing: This exemption includes machinery and equipment used to establish new or to replace existing material recovery processing plants.
Plant Expansion: This exemption includes machinery, equipment, and parts and the materials and supplies solely required for installing or constructing the machinery and equipment, used to establish new or to expand existing Missouri manufacturing, mining, or fabricating plants. To qualify, the machinery must be used directly in manufacturing, mining or fabricating a product that is ultimately subject to sales or use tax, or its equivalent, in Missouri or other states.
Research and Development of Agricultural Biotechnology Products and Plant Genomics Products and Prescription Pharmaceuticals: This exemption is specifically authorized in Section 144.030.2(34), RSMo, and exempts any tangible personal property used or consumed directly or exclusively in research and development of agricultural, biotechnology, and plant genomics products and prescription pharmaceuticals consumed by humans or animals.
Manufacturing, Section 144.054, RSMo
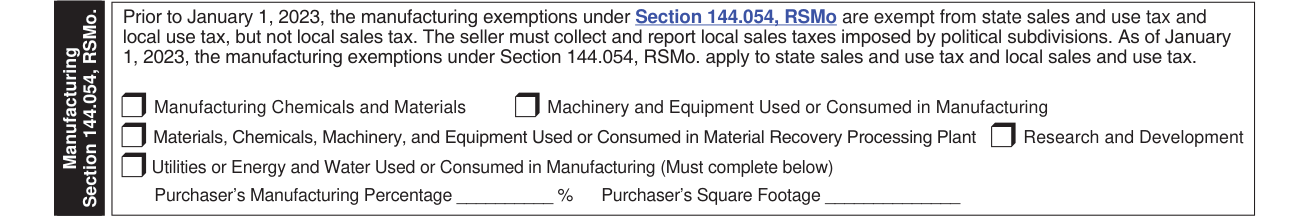
On Form 149, check the appropriate box for the type of exemption to be claimed according to Section 144.054, RSMo.
As of January 1, 2023, the manufacturing exemptions under Section 144.054, RSMo, apply to state sales and use tax and local sales and use tax.
To qualify for a manufacturing exemption in this section, the item must be used or consumed and does not have the same requirement of direct use that is required in Section 144.030, RSMo. Additionally, the manufactured product is not required to be ultimately subject to tax.
Manufacturing Chemicals and Materials: Check this box if the exemption is for chemicals, materials, critical materials, or critical pharmaceuticals used or consumed in manufacturing, processing, compounding or producing a product.
Machinery and Equipment Used or Consumed in Manufacturing: Check this box if the exemption is for machinery or equipment used or consumed in manufacturing, processing, compounding or producing a product.
Materials, Chemicals, Machinery, and Equipment Used or Consumed in Material Recovery Processing Plant: Check this box if the exemption is for material recovery processing.
Research and Development: Check this box if the exemption is for the research and development related to manufacturing, processing, compounding or producing a product.
Utilities or Energy and Water Used or Consumed in Manufacturing: If claiming utilities (electrical energy, gas or water), record account numbers, meter numbers, or other information as required by the vendor. All purchasers who are claiming an exemption for energy use must provide the amount of energy use which is related to manufacturing in the space provided and also select the method by which this percentage was obtained.
For Utilities or Energy and Water Used or Consumed in Manufacturing, you must complete the Purchaser's Manufacturing Percentage and the Purchaser's Square Footage.
Electricity Production, Section 144.058, RSMo
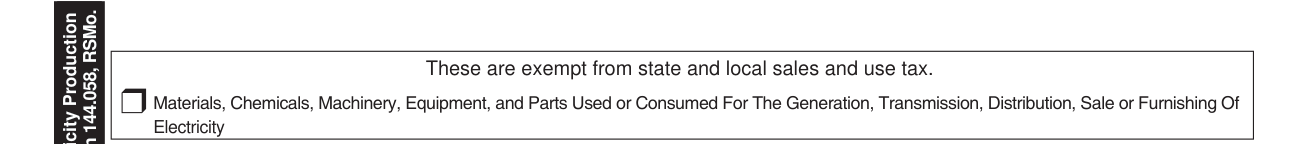
Check this box if the exemption is for any materials, chemicals, machinery, equipment, or parts that is used or consumed in the generation, transmission, distribution, sale, or furnishing of electricity.
Broadband Communications Services, Section 144.812, RSMo
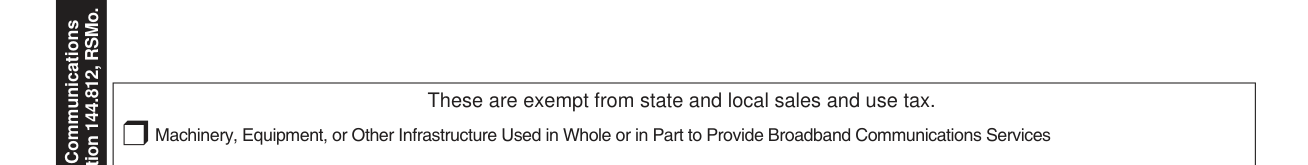
Check this box if the exemption is for any machinery, equipment, or other infrastructure used in whole or in part to provide broadband communications services.
Agricultural, Common Carrier, Locomotive Fuel, Pollution Control, Commercial Motor Vehicles, Nuclear Security Enterprise and Other
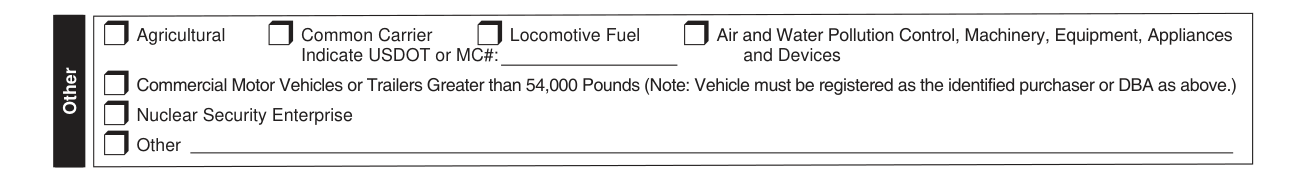
Agricultural: Farm machinery and equipment are exempt from tax if used for any agricultural purposes, used on land owned or leased for the purpose of producing farm products, and used directly in the production of farm products to be ultimately sold at retail.
Common Carrier: Materials, replacement parts and equipment purchased for use directly upon, and for the repair and maintenance or manufacture of, motor vehicles, watercraft, railroad rolling stock or aircraft engaged as common carriers of persons or property. Indicate USDOT or MC#. See Section 144.030.2(3), RSMo.
Locomotive Fuel: Fuel purchased for use in a locomotive that is a common carrier is exempt from sales and use tax.
Air and Water Pollution Control Machinery, Equipment, Appliances and Devices: Machinery, equipment, appliances and devices purchased or leased and used solely for the purpose of preventing, abating or monitoring water and air pollution, and materials and supplies solely required for the installation, construction or reconstruction of such machinery, equipment, appliances and devices.
Commercial Motor Vehicles or Trailers Greater Than 54,000 Pounds: Motor vehicles registered for and capable of pulling in excess of 54,000 pounds and their trailers actually used in the normal course of business to haul property on the public highways of the state are exempt from tax. The vehicle must be registered as the identified purchaser or DBA.
Nuclear Security Enterprise: Tangible personal property, building materials, equipment, fixtures, manufactured goods, machinery, and parts for the purposes of constructing all or any portion of a nuclear security enterprise located in any city with more than four hundred thousand inhabitants and located in more than one county is exempt from state and local sales and use tax.
Other: Exemptions not listed on this sheet, but are provided by statute. Provide explanation of exemption being claimed.
Signature, Title and Date

Sign as the Purchaser or the Purchaser's Agent, then enter your Title and the Date (MM/DD/YYYY).
Under penalties of perjury, the purchaser declares that the information on the form and any attached supplement is true, complete, and correct.
Where to get help with Form 149
If you have questions, contact the Department of Revenue at Phone: (573) 751-2836, TTY: (800) 735-2966, Fax: (573) 522-1666 or E-mail: salestaxexemptions@dor.mo.gov.
Sources
[1] Form 149 (Revised 08-2026), Sales and Use Tax Exemption Certificate, Missouri Department of Revenue (the Official source link on this page).
