

Form TC-721 at a glance
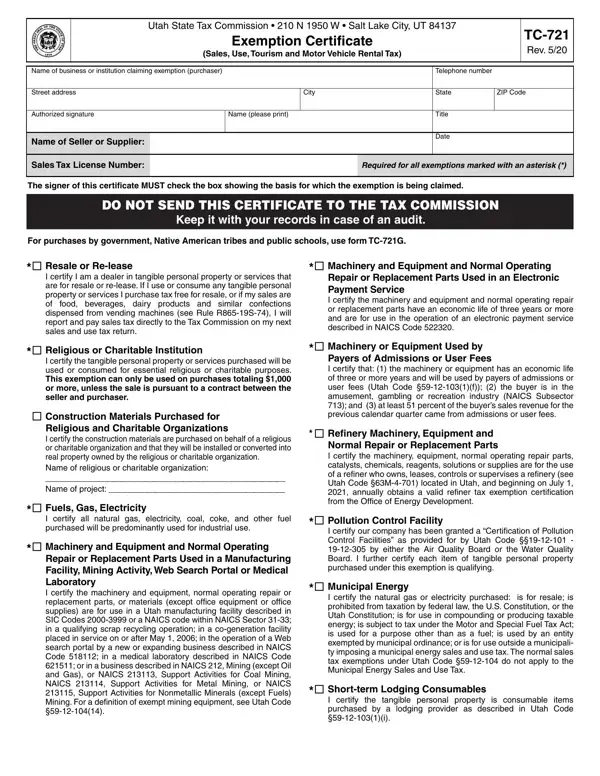
What it is: This exemption certificate is for Sales, Use, Tourism and Motor Vehicle Rental Tax; the signer must check the box showing the basis for which the exemption is being claimed.
Who signs: Sign on the Authorized signature line, then enter Name (please print) and Title.
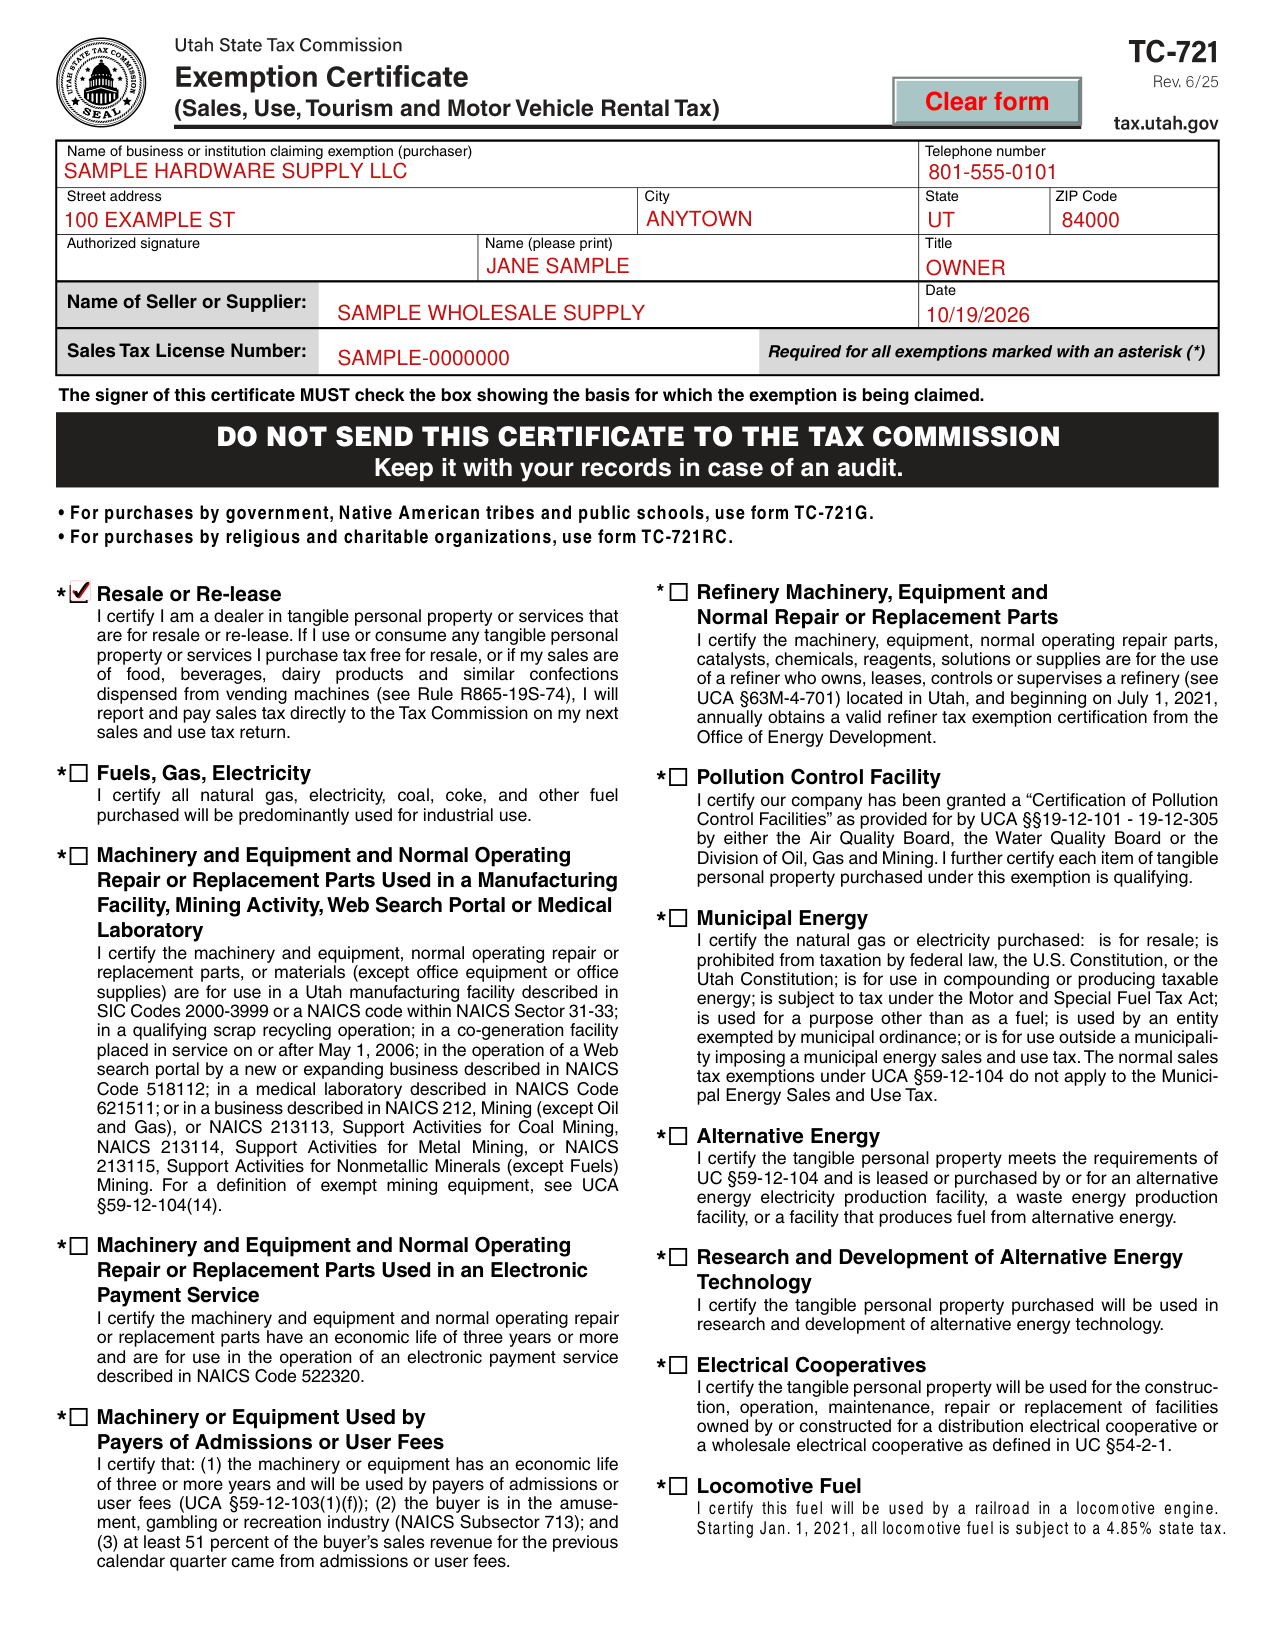
A filled-in Form TC-721 example: a dealer claims the resale exemption
How to fill out Form TC-721, box by box
Business name, telephone and street address

Enter the Name of business or institution claiming exemption (purchaser) and its Telephone number.
Enter the Street address, City, State and ZIP Code.
Authorized signature, seller, date and sales tax license number
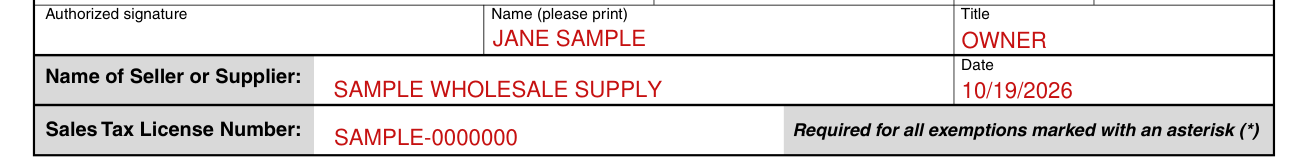
Sign on the Authorized signature line, then enter Name (please print) and Title.
Enter the Name of Seller or Supplier and the Date.
Enter the Sales Tax License Number.
Where a box is marked with *, the purchaser must provide the sales tax license number in the header on page 1.
Resale, fuels and manufacturing machinery
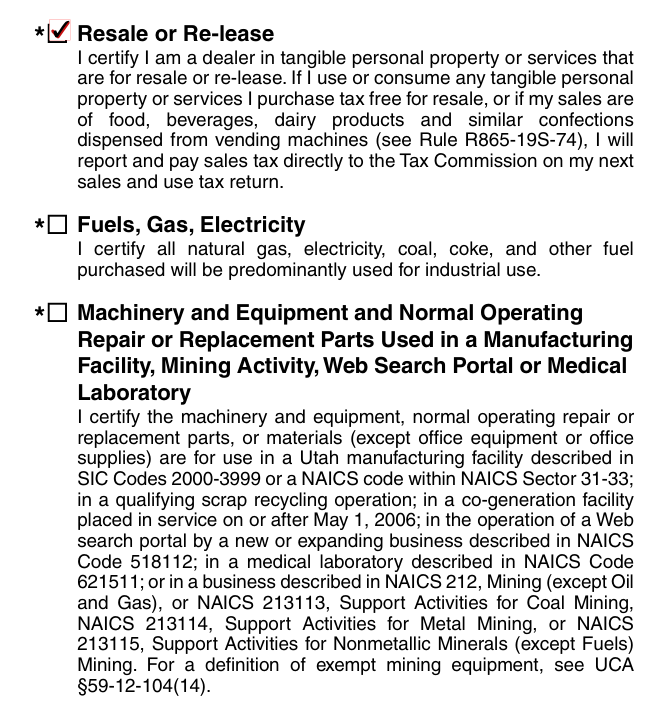
Check Resale or Re-lease to certify that you are a dealer in tangible personal property or services that are for resale or re-lease. If you use or consume any tangible personal property or services you purchase tax free for resale, or if your sales are of food, beverages, dairy products and similar confections dispensed from vending machines (see Rule R865-19S-74), you will report and pay sales tax directly to the Tax Commission on your next sales and use tax return.
Check Fuels, Gas, Electricity to certify that all natural gas, electricity, coal, coke, and other fuel purchased will be predominantly used for industrial use.
Check the box for Machinery and Equipment and Normal Operating Repair or Replacement Parts Used in a Manufacturing Facility, Mining Activity, Web Search Portal or Medical Laboratory to certify that the machinery and equipment, normal operating repair or replacement parts, or materials (except office equipment or office supplies) are for use in a Utah manufacturing facility described in SIC Codes 2000-3999 or a NAICS code within NAICS Sector 31-33; in a qualifying scrap recycling operation; in a co-generation facility placed in service on or after May 1, 2006; in the operation of a Web search portal by a new or expanding business described in NAICS Code 518112; in a medical laboratory described in NAICS Code 621511; or in a business described in NAICS 212, Mining (except Oil and Gas), or NAICS 213113, Support Activities for Coal Mining, NAICS 213114, Support Activities for Metal Mining, or NAICS 213115, Support Activities for Nonmetallic Minerals (except Fuels) Mining. For a definition of exempt mining equipment, see UCA 59-12-104(14).
Refinery machinery and pollution control facility
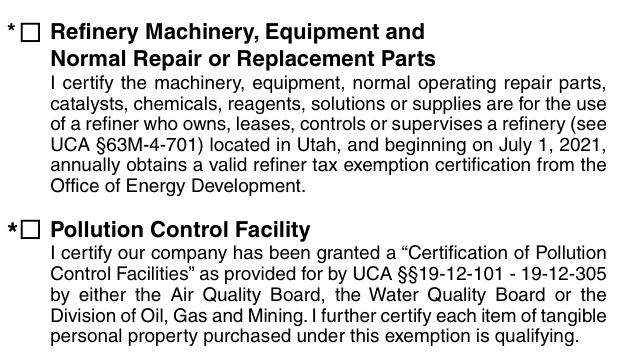
Check Refinery Machinery, Equipment and Normal Repair or Replacement Parts to certify that the machinery, equipment, normal operating repair parts, catalysts, chemicals, reagents, solutions or supplies are for the use of a refiner who owns, leases, controls or supervises a refinery (see UCA 63M-4-701) located in Utah, and beginning on July 1, 2021, annually obtains a valid refiner tax exemption certification from the Office of Energy Development.
Check Pollution Control Facility to certify that your company has been granted a "Certification of Pollution Control Facilities" as provided for by UCA 19-12-101 to 19-12-305 by either the Air Quality Board, the Water Quality Board or the Division of Oil, Gas and Mining, and that each item of tangible personal property purchased under this exemption is qualifying.
Locomotive fuel
Check Locomotive Fuel to certify that this fuel will be used by a railroad in a locomotive engine. Starting Jan. 1, 2021, all locomotive fuel is subject to a 4.85% state tax.
Service provider consumables, commercial airlines, commercials and mailing lists
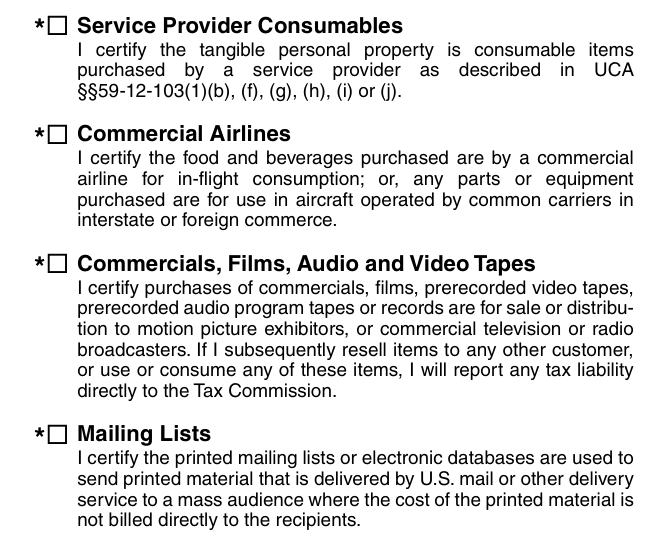
Check Service Provider Consumables to certify that the tangible personal property is consumable items purchased by a service provider as described in UCA 59-12-103(1)(b), (f), (g), (h), (i) or (j).
Check Commercial Airlines to certify that the food and beverages purchased are by a commercial airline for in-flight consumption; or, any parts or equipment purchased are for use in aircraft operated by common carriers in interstate or foreign commerce.
Check Commercials, Films, Audio and Video Tapes to certify that purchases of commercials, films, prerecorded video tapes, prerecorded audio program tapes or records are for sale or distribution to motion picture exhibitors, or commercial television or radio broadcasters. If you subsequently resell items to any other customer, or use or consume any of these items, you will report any tax liability directly to the Tax Commission.
Check Mailing Lists to certify that the printed mailing lists or electronic databases are used to send printed material that is delivered by U.S. mail or other delivery service to a mass audience where the cost of the printed material is not billed directly to the recipients.
Film, construction materials, agricultural producer and motor vehicle rental
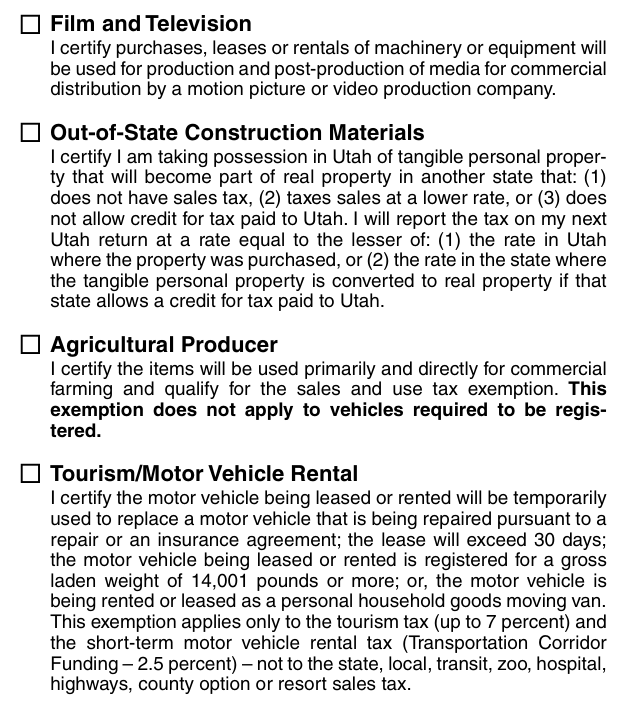
Check Film and Television to certify that purchases, leases or rentals of machinery or equipment will be used for production and post-production of media for commercial distribution by a motion picture or video production company.
Check Out-of-State Construction Materials to certify that you are taking possession in Utah of tangible personal property that will become part of real property in another state that: (1) does not have sales tax, (2) taxes sales at a lower rate, or (3) does not allow credit for tax paid to Utah. You will report the tax on your next Utah return at a rate equal to the lesser of: (1) the rate in Utah where the property was purchased, or (2) the rate in the state where the tangible personal property is converted to real property if that state allows a credit for tax paid to Utah.
Check Agricultural Producer to certify that the items will be used primarily and directly for commercial farming and qualify for the sales and use tax exemption. This exemption does not apply to vehicles required to be registered.
Check Tourism/Motor Vehicle Rental to certify that the motor vehicle being leased or rented will be temporarily used to replace a motor vehicle that is being repaired pursuant to a repair or an insurance agreement; the lease will exceed 30 days; the motor vehicle being leased or rented is registered for a gross laden weight of 14,001 pounds or more; or, the motor vehicle is being rented or leased as a personal household goods moving van. This exemption applies only to the tourism tax (up to 7 percent) and the short-term motor vehicle rental tax (Transportation Corridor Funding, 2.5 percent), not to the state, local, transit, zoo, hospital, highways, county option or resort sales tax.
Textbooks for higher education and direct mail
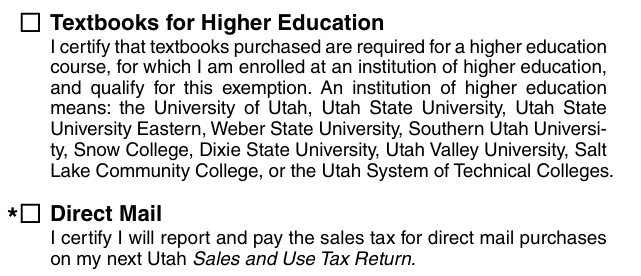
Check Textbooks for Higher Education to certify that textbooks purchased are required for a higher education course, for which you are enrolled at an institution of higher education, and qualify for this exemption. An institution of higher education means the University of Utah, Utah State University, Utah State University Eastern, Weber State University, Southern Utah University, Snow College, Dixie State University, Utah Valley University, Salt Lake Community College, or the Utah System of Technical Colleges.
Check Direct Mail to certify that you will report and pay the sales tax for direct mail purchases on your next Utah Sales and Use Tax Return.
More rules for Form TC-721
As the purchaser, you must notify the seller of cancellation, modification, or limitation of the exemption you have claimed.
Common questions about Form TC-721
Where do I file it?
Do not send this certificate to the Tax Commission. Keep it with your records in case of an audit.
When is this form not the right one?
For purchases by government, Native American tribes and public schools, use form TC-721G. For purchases by religious and charitable organizations, use form TC-721RC.
Where to get help with Form TC-721
Questions? Email taxmaster@utah.gov, or call 801-297-2200 or 1-800-662-4335.
Sources
[1] Form TC-721, Exemption Certificate for Sales, Use, Tourism and Motor Vehicle Rental Tax, Utah State Tax Commission (the Official source link on this page).