

Form 700 at a glance
What it is: Form 700 is the State of Illinois Estate & Generation-Skipping Transfer Tax Return for decedents dying on or after January 1, 2023.
Who signs: Sign and fill in the Title and Date on Signature of decedent's personal representative and on Signature of preparer.
If an estate's gross value exceeds $4 million after inclusion of adjusted taxable gifts, an Illinois Form 700 must be filed, whether or not a Federal Return is required by the Internal Revenue Service (checked November 8, 2026).
What to bring and attach to Form 700
When the Tentative Taxable Estate plus adjusted taxable gifts exceeds the federal exclusion amount, the Illinois Estate Tax Return, Form 700, must include a copy of the Federal Form 706 with all schedules and attachments.
The undersigned further certify that the attached Will (if decedent died testate) is a true and correct copy of the Will of the decedent.
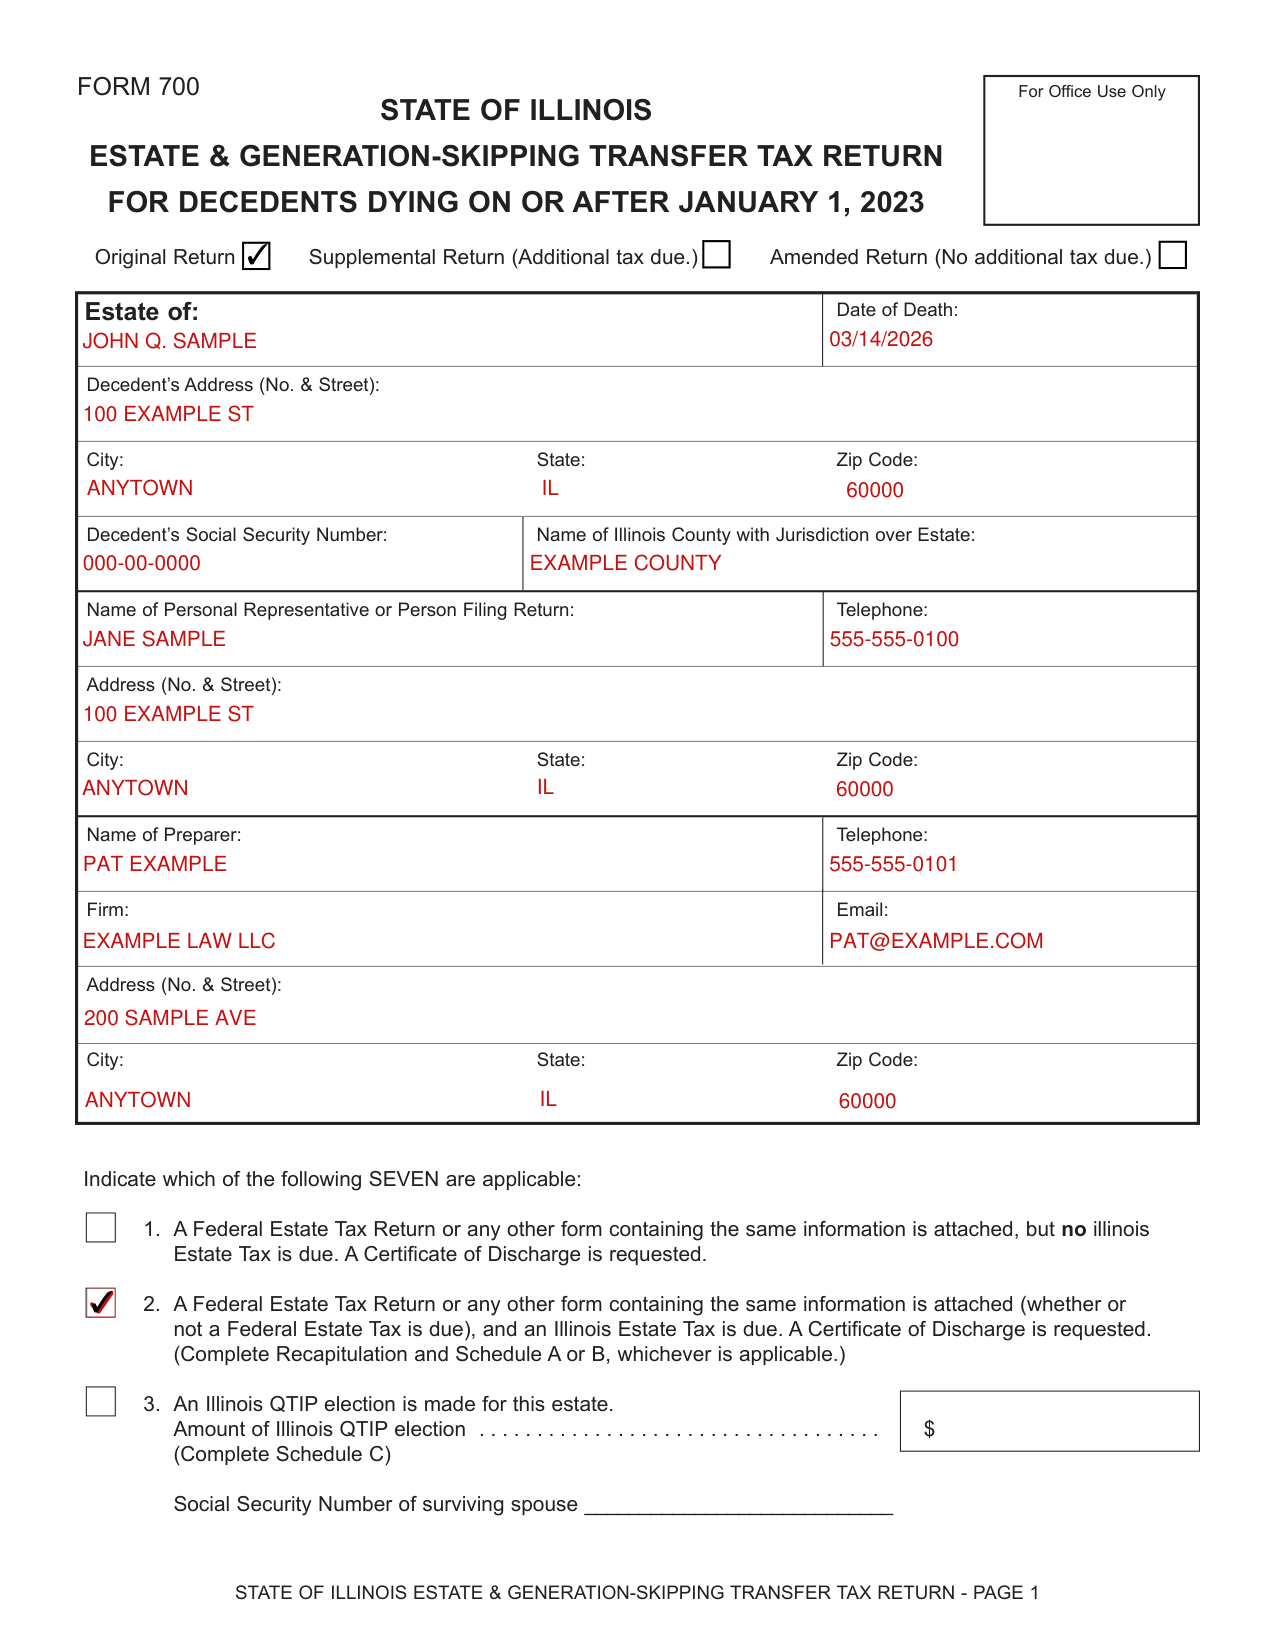
A filled-in Form 700 example: an Illinois estate with a federal return attached
How to fill out Form 700, box by box
When and where to file and pay
This return must be filed with the Illinois Attorney General within nine (9) months of the date of death.
Extensions are available upon written application to the Attorney General using Form 700-EXT or any other written submission. Additionally, the Attorney General recognizes federal extensions.
For Cook, Dupage, Lake, and McHenry counties, file the original of the Return with the Office of the Attorney General, Revenue Litigation Bureau, 115 S Lasalle Street, Chicago, IL 60603.
For all other counties, file the original of the Return with the Office of the Attorney General, Revenue Litigation Bureau, 500 South Second Street, Springfield, Illinois 62701.
Payment of all taxes, interest and penalties must be made payable to the Illinois State Treasurer with the “Illinois State Treasurer Estate Tax Payment Form” at the address designated therein. All payments must be mailed to or deposited with the State Treasurer in order to be credited with timely payment.
Original, Supplemental or Amended Return

Check one of Original Return, Supplemental Return (Additional tax due.) or Amended Return (No additional tax due.).
The estate and the decedent
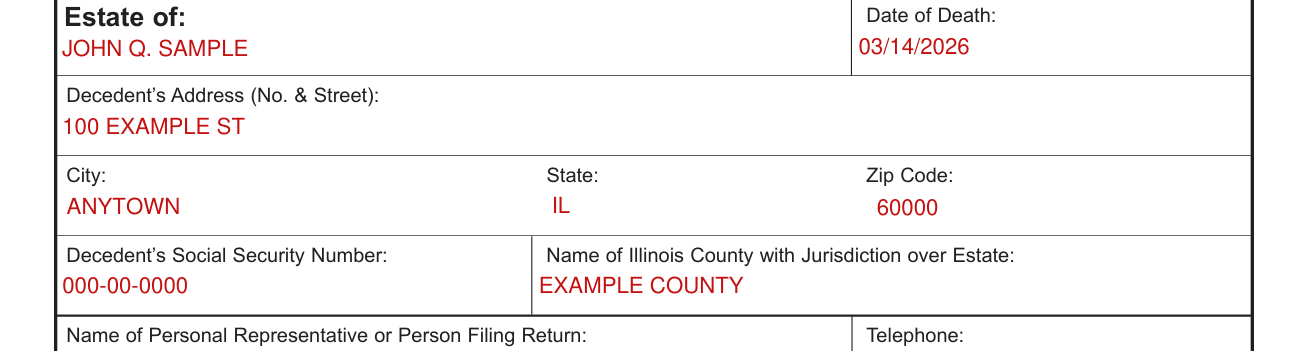
Enter Estate of, Date of Death, Decedent's Address (No. & Street), City, State, Zip Code, Decedent's Social Security Number and Name of Illinois County with Jurisdiction over Estate.
The personal representative
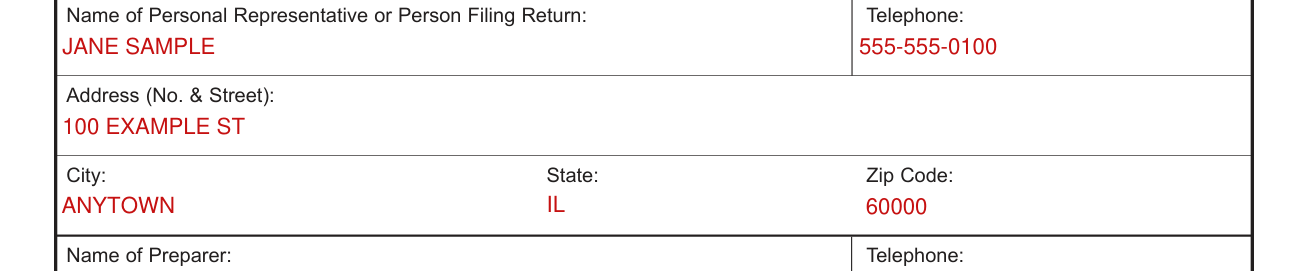
Enter Name of Personal Representative or Person Filing Return, Telephone, Address (No. & Street), City, State and Zip Code.
The preparer
Enter Name of Preparer, Telephone, Firm, Email, Address (No. & Street), City, State and Zip Code.
Which of the following SEVEN are applicable
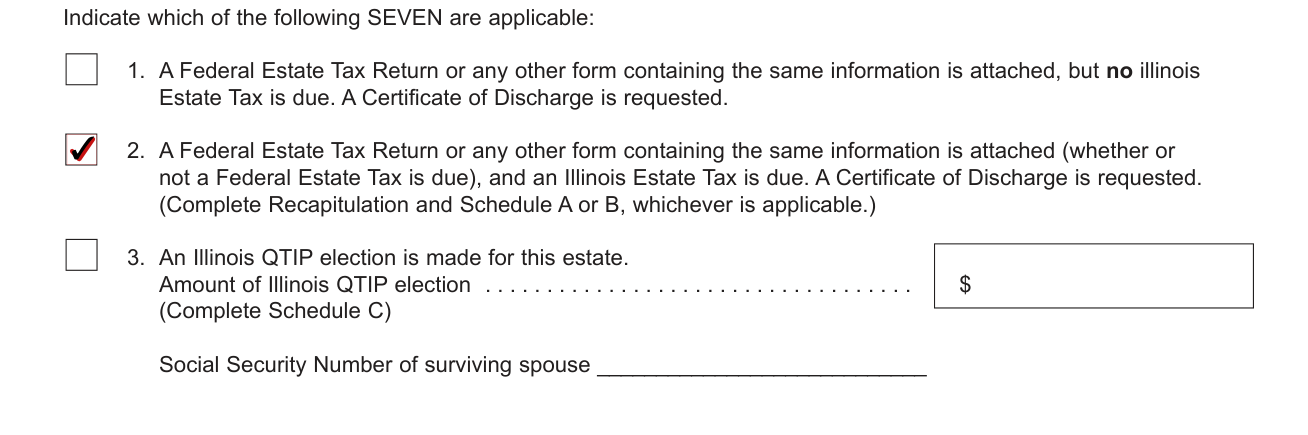
Indicate which of the following SEVEN are applicable: 1. A Federal Estate Tax Return or any other form containing the same information is attached, but no illinois Estate Tax is due. A Certificate of Discharge is requested. 2. A Federal Estate Tax Return or any other form containing the same information is attached (whether or not a Federal Estate Tax is due), and an Illinois Estate Tax is due. A Certificate of Discharge is requested. (Complete Recapitulation and Schedule A orB, whichever is applicable.) 3. An Illinois QTIP election is made for this estate. Amount of Illinois QTIP election $ (Complete Schedule C) Social Security Number of surviving spouse.
An itemized list of property included in the Illinois QTIP should be submitted with the Return.
Boxes 4 to 6 on page 2
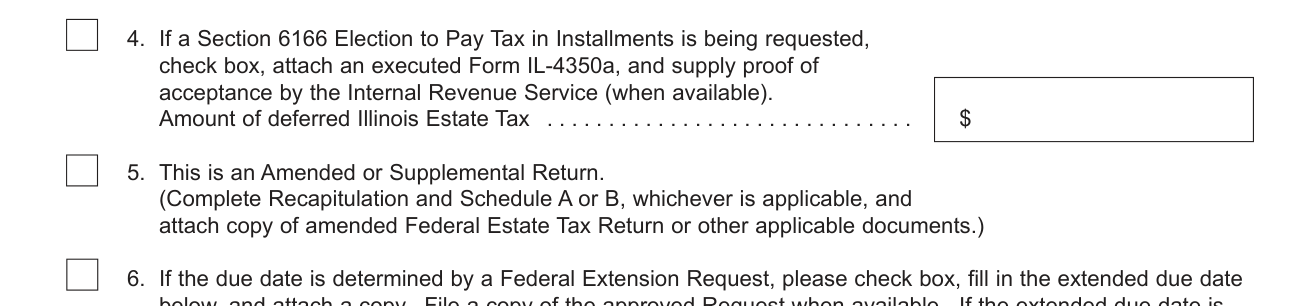
If a Section 6166 Election to Pay Tax in Installments is being requested, check box, attach an executed Form IL-4350a, and supply proof of acceptance by the Internal Revenue Service (when available).
Amount of deferred Illinois Estate Tax.
This is an Amended or Supplemental Return. (Complete Recapitulation and Schedule A orB, whichever is applicable, and attach copy of amended Federal Estate Tax Return or other applicable documents.)
If the due date is determined by a Federal Extension Request, please check box, fill in the extended due date, and attach a copy. File a copy of the approved Request when available.
If the extended due date is based on an Illinois request, check the box and fill in the extended due date in Due date of this Return.
Decedent was a resident or a non-resident
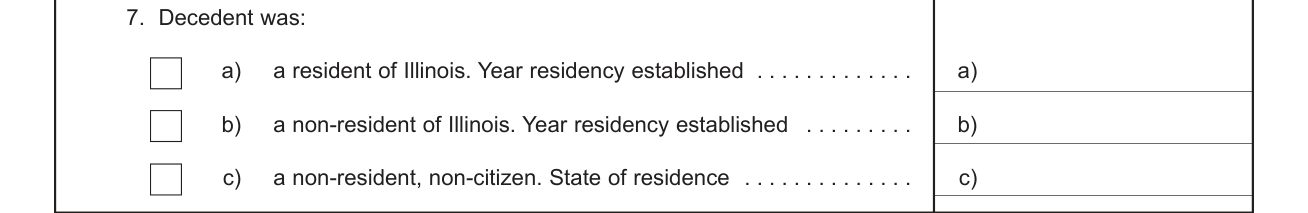
Decedent was: a resident of Illinois (Year residency established); a non-resident of Illinois (Year residency established); or a non-resident, non-citizen (State of residence).
The signatures
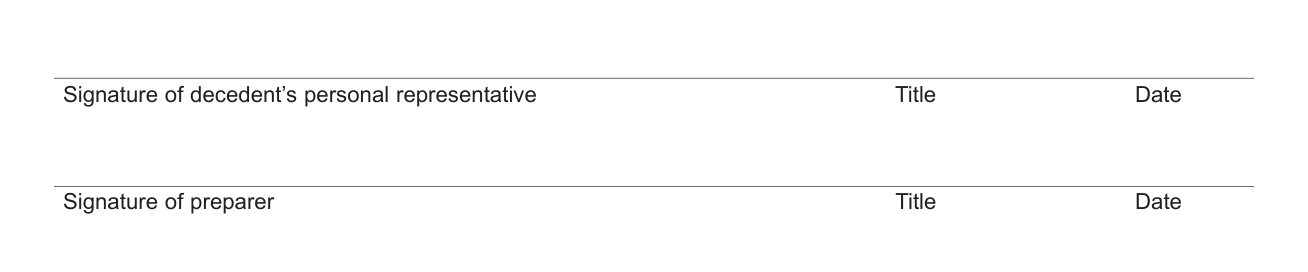
Sign and fill in the Title and Date on Signature of decedent's personal representative and on Signature of preparer.
The undersigned declare, under penalties of perjury, that they have examined this return, including any and all accompanying schedules or attachments, and that they believe the same to be true and correct as to every material matter and further verify that any attached Federal Estate Tax Return and any other applicable Federal tax documents are true and corrected copies of the originals filed with the Internal Revenue Service.
Schedule A, Resident Decedent's Estate
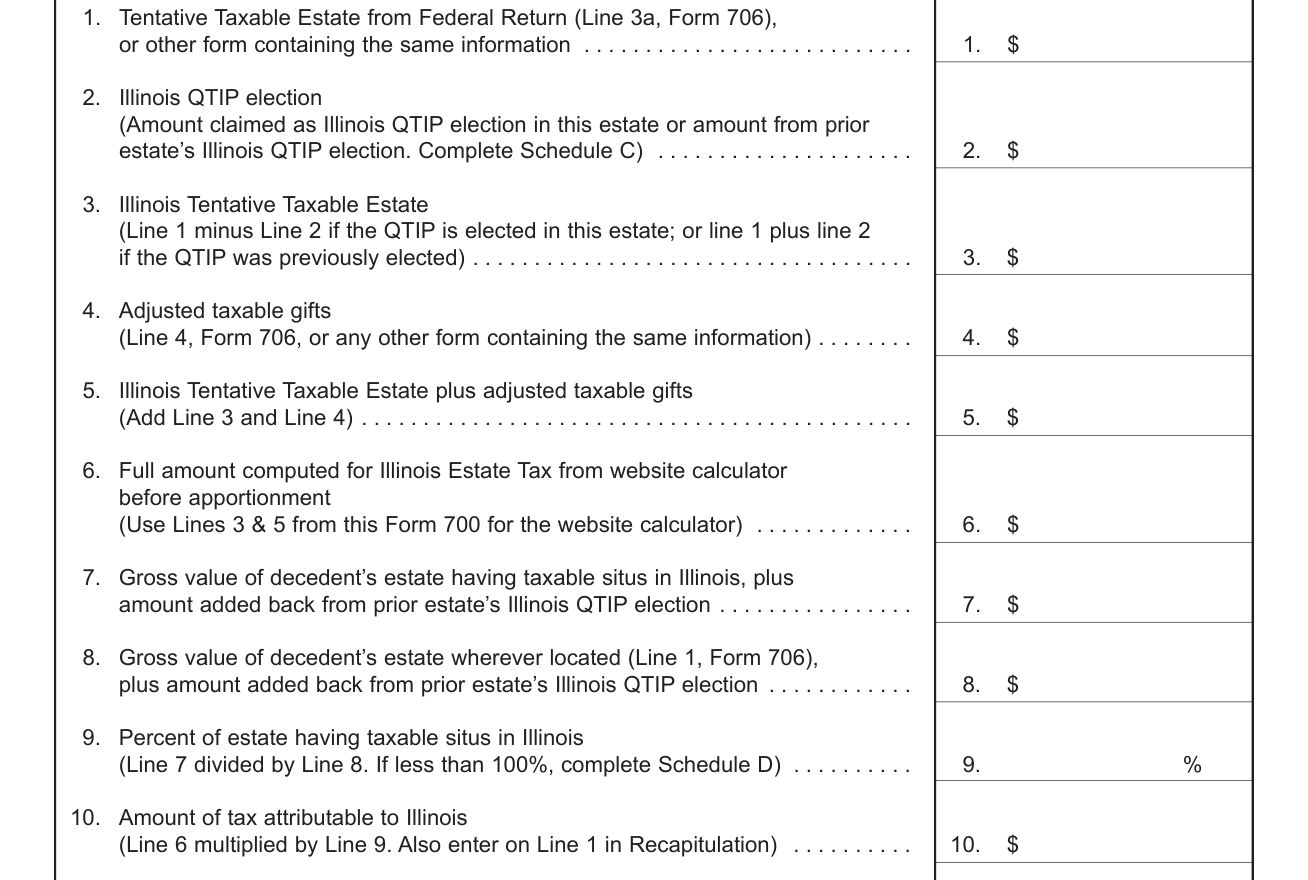
Schedule A, Resident Decedent's Estate: Tentative Taxable Estate from Federal Return (Line 3a, Form 706), or other form containing the same information.
Illinois QTIP election (Amount claimed as Illinois QTIP election in this estate or amount from prior estate's Illinois QTIP election. Complete Schedule C).
Illinois Tentative Taxable Estate (Line 1 minus Line 2 if the QTIP is elected in this estate; or line 1 plus line 2 if the QTIP was previously elected).
Adjusted taxable gifts (Line 4, Form 706, or any other form containing the same information).
Illinois Tentative Taxable Estate plus adjusted taxable gifts (Add Line 3 and Line 4).
Full amount computed for Illinois Estate Tax from website calculator before apportionment (Use Lines 3 & 5 from this Form 700 for the website calculator).
The calculator at the Illinois Attorney General's website (www.illinoisattorneygeneral.gov) may be used for this computation. To determine tax due, insert the amounts from Lines 3 and 5 of Schedule A orB, Form 700. Please note that the Calculator will not perform the computation unless amounts are entered into both fields.
Gross value of decedent's estate having taxable situs in Illinois, plus amount added back from prior estate's Illinois QTIP election.
Gross value of decedent's estate wherever located (Line 1, Form 706), plus amount added back from prior estate's Illinois QTIP election.
Percent of estate having taxable situs in Illinois (Line 7 divided by Line 8. If less than 100%, complete ScheduleD).
Amount of tax attributable to Illinois (Line 6 multiplied by Line 9. Also enter on Line 1 in Recapitulation).
In the case of a decedent who was a resident of this State at the time of death, all of the transferred property has a tax situs in this State, including any such property held in trust, except real or tangible personal property physically situated in another state.
Schedule B, Non-Resident Decedent's Estate
Schedule B is for a Non-Resident Decedent's Estate.
Recapitulation
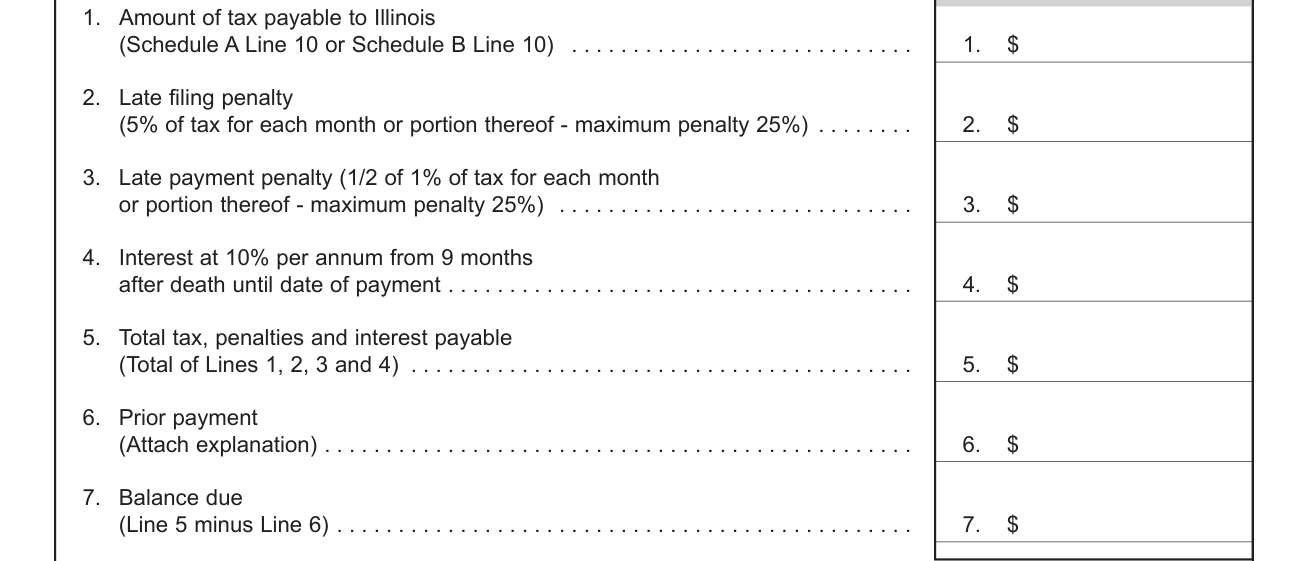
Recapitulation: Amount of tax payable to Illinois (Schedule A Line 10 or Schedule B Line 10). Total tax, penalties and interest payable (Total of Lines 1, 2, 3 and 4). Prior payment (Attach explanation). Balance due (Line 5 minus Line 6).
Interest is 10% per annum from 9 months after death until date of payment.
Late filing penalty is 5% of tax for each month or portion thereof, with a maximum penalty 25%. Late payment penalty is 1/2 of 1% of tax for each month or portion thereof, with a maximum penalty 25%.
Schedule C, Illinois QTIP
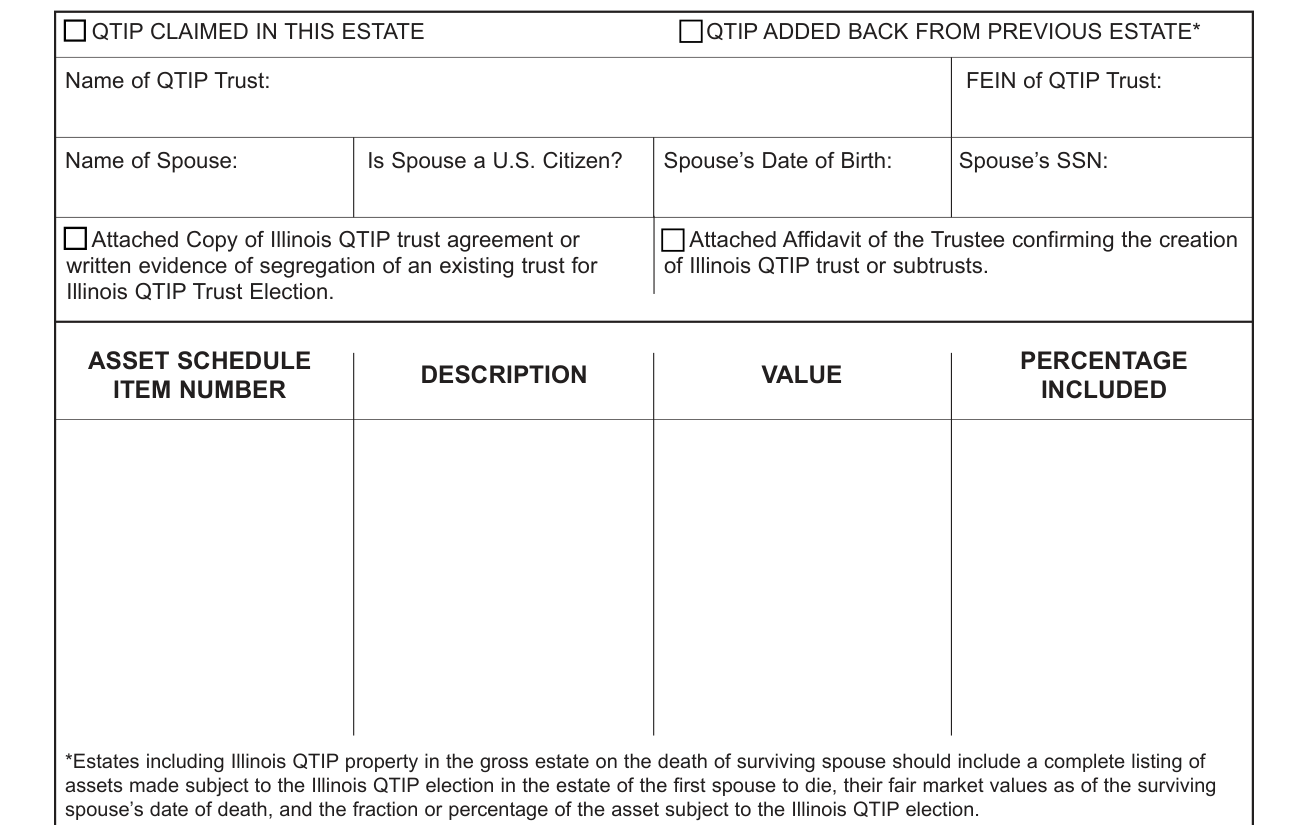
Schedule C, Illinois Qualified Terminable Interest Property (QTIP): check QTIP CLAIMED IN THIS ESTATE or QTIP ADDED BACK FROM PREVIOUS ESTATE.
Enter Name of QTIP Trust, FEIN of QTIP Trust, Name of Spouse, Is Spouse a U.S. Citizen?, Spouse's Date of Birth and Spouse's SSN.
Schedule D, Property with Situs Outside Illinois
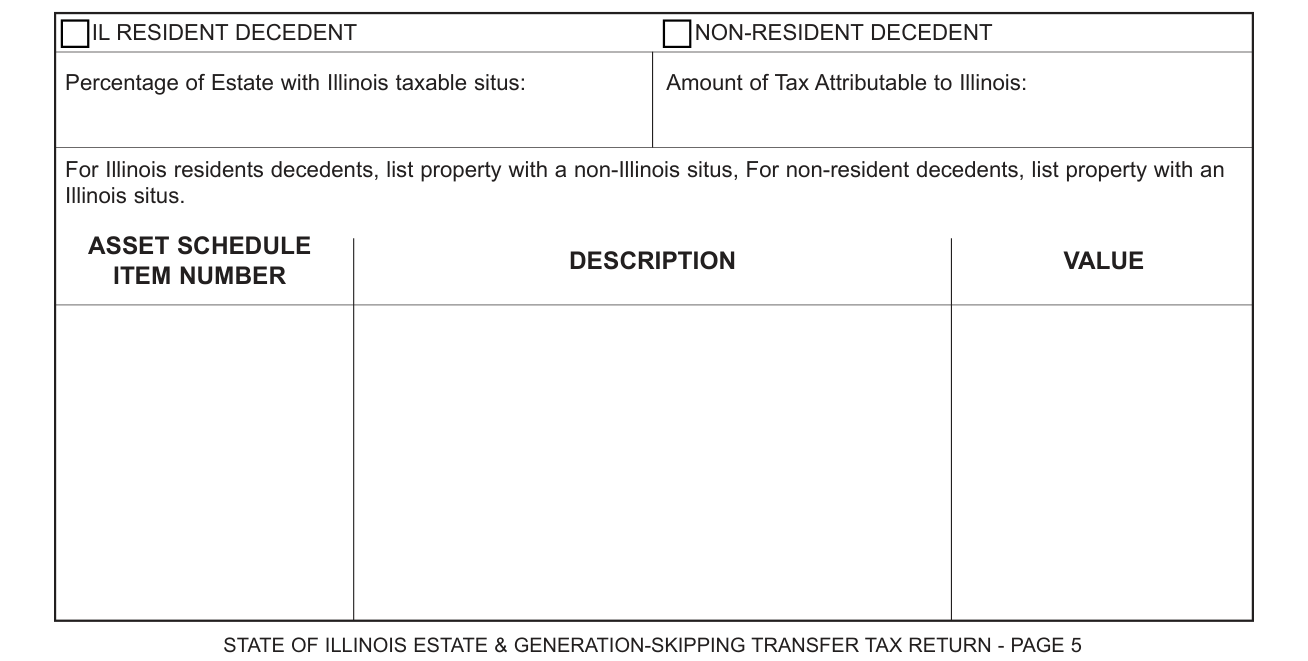
Schedule D, Estates Containing Property with Situs Outside Illinois: check IL RESIDENT DECEDENT or NON-RESIDENT DECEDENT and enter Percentage of Estate with Illinois taxable situs and Amount of Tax Attributable to Illinois. For Illinois residents decedents, list property with a non-Illinois situs, For non-resident decedents, list property with an Illinois situs.
Sources
[1] Form 700 (Revised 10/24), Illinois Attorney General (the Official source link on this page).