

Form 50-246 at a glance
What it is: Form 50-246 is the Texas Comptroller of Public Accounts Dealer's Motor Vehicle Inventory Tax Statement.
Who signs: Signature required on last page only.
A dealer of motor vehicles must file this inventory tax statement under Tax Code Section 23.122.
What to bring and attach to Form 50-246
File this statement together with an amount equal to the total amount of the unit property tax assigned to all motor vehicles sold in the preceding month.
File a separate statement for each business location and retain documentation relating to the disposition of each vehicle.
A filled-in Form 50-246 example: a dealer reports two sales in one month
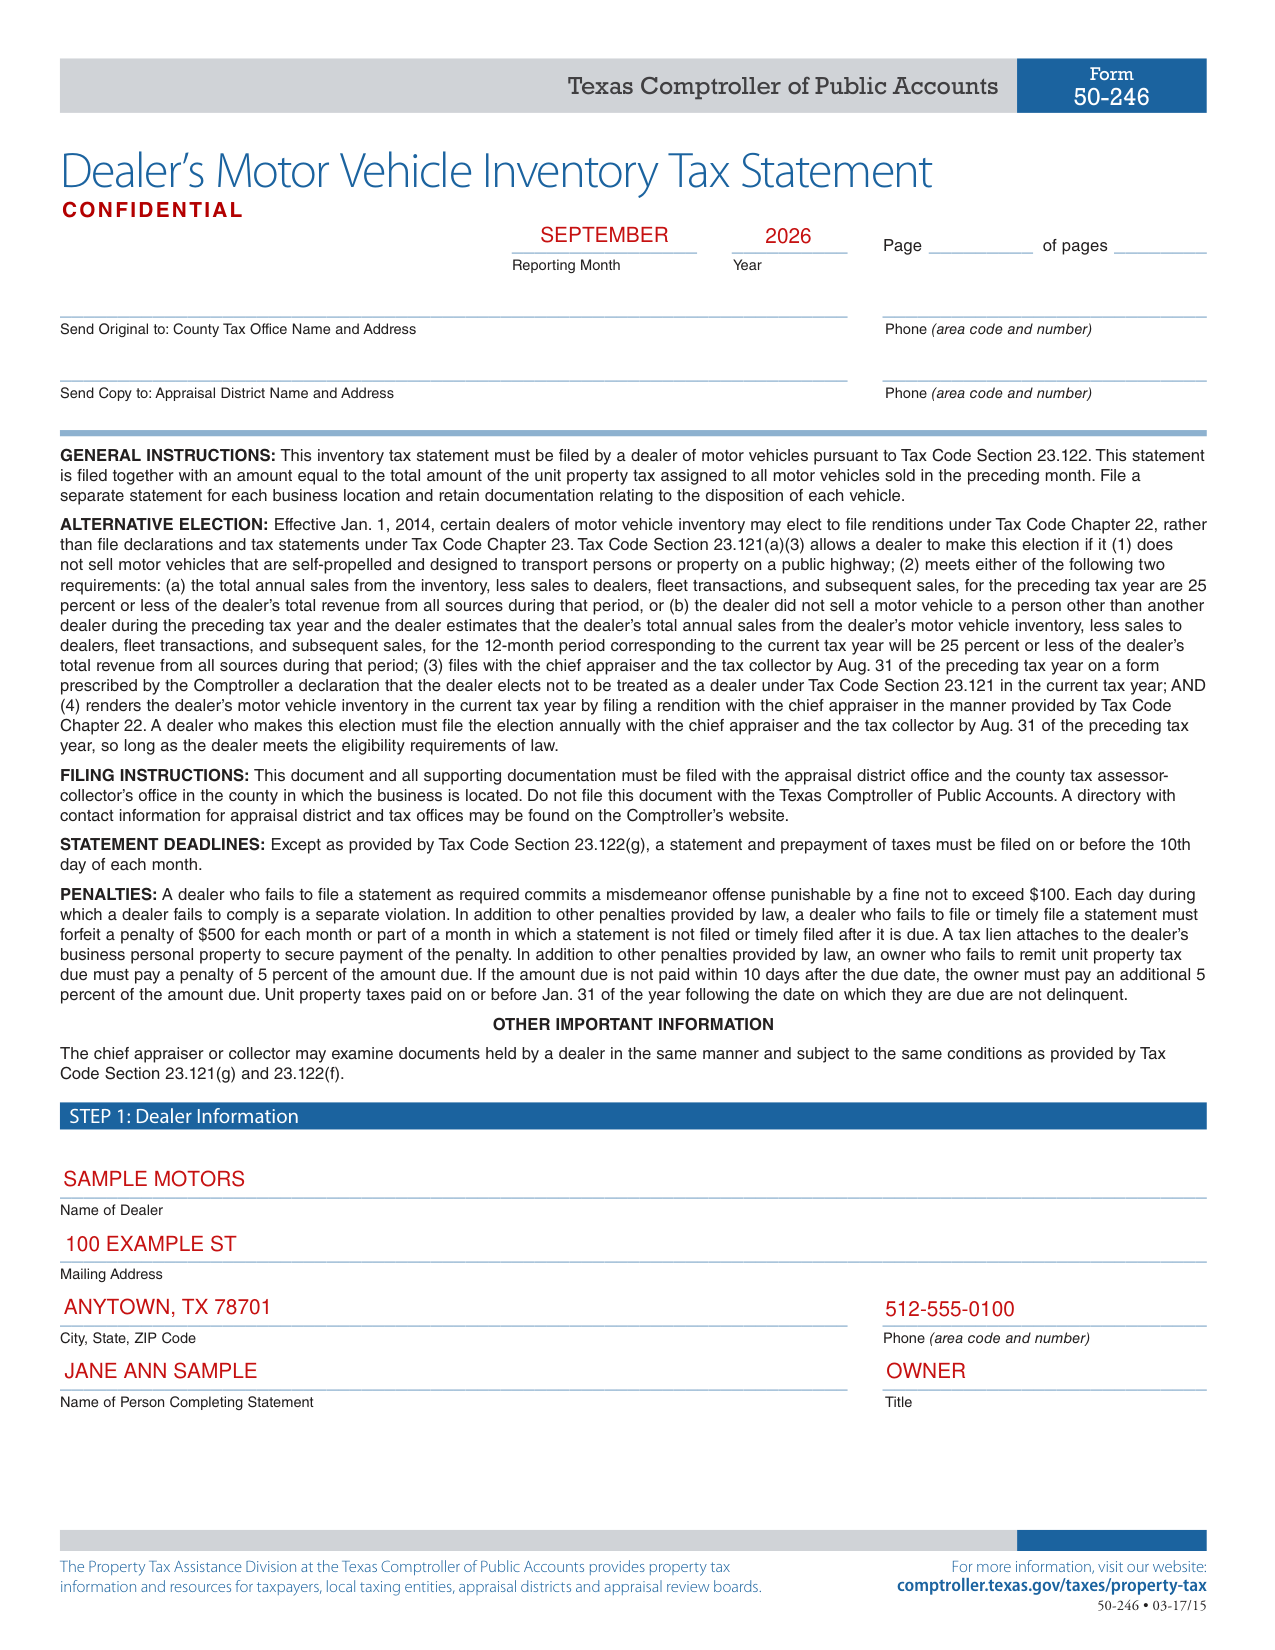
How to fill out Form 50-246, box by box
Name of Dealer, Mailing Address and Person Completing Statement
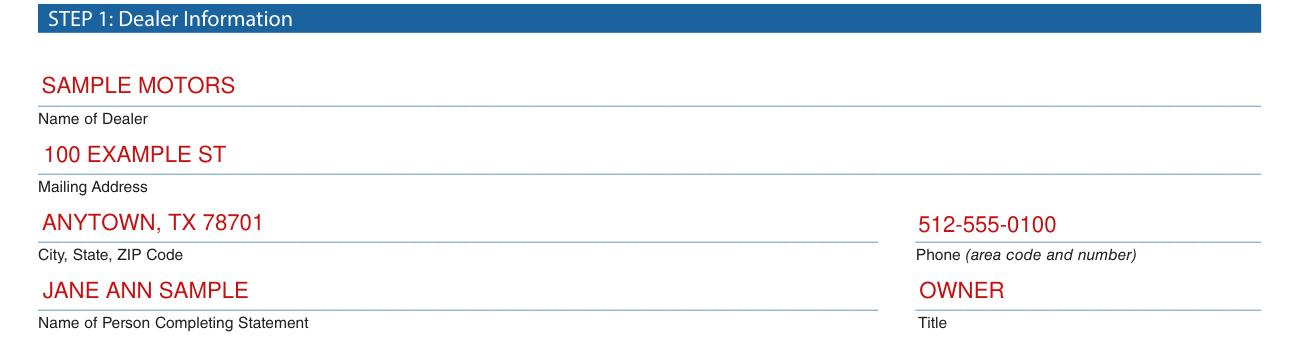
Enter the Name of Dealer, the Mailing Address, the City, State, ZIP Code, the Phone (area code and number), the Name of Person Completing Statement and the Title.
Name of Business, Address and Business Start Date
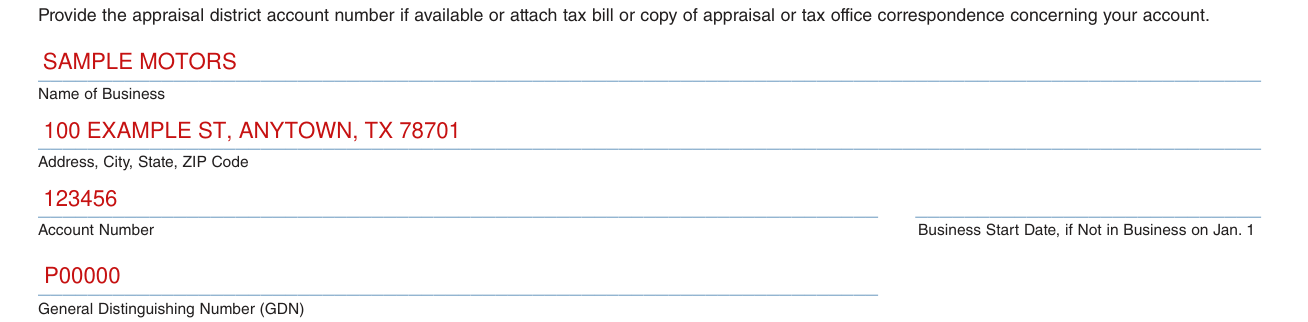
Enter the Name of Business, the Address, City, State, ZIP Code, the Account Number, the Business Start Date, if Not in Business on Jan. 1, and the General Distinguishing Number (GDN).
Provide the appraisal district account number if available or attach tax bill or copy of appraisal or tax office correspondence concerning your account.
Step 3: Vehicle Inventory Information
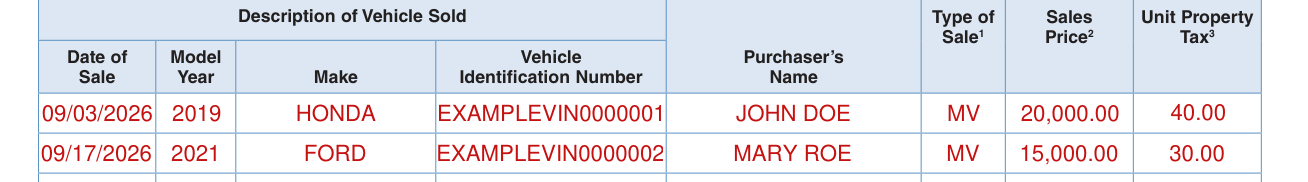
Provide the information about each motor vehicle sale during the reporting month.
Complete the information on each motor vehicle sold, including the date of sale, model year, model make, vehicle identification number, purchaser's name, type of sale, sales price and unit property tax.
Continue on additional sheets if necessary.
In lieu of filling out the information in this step, you may attach separate documentation setting forth the information required, and all such information must be separately identified in a manner that conforms to the column headers used in the table.
Footnote 1, Type of Sale: Place one of the following codes by each sale reported: MV - motor vehicle inventory - sales of motor vehicles.
A motor vehicle is a fully self-propelled vehicle with at least two wheels which has the primary purpose of transporting people or property (whether or not intended for use on a public street, road, or highway) and includes a towable recreational vehicle.
FL - fleet transactions - motor vehicles included in the sale of five or more motor vehicles from inventory to the same person within one calendar year.
DL - dealer sales - sales of vehicles to another Texas dealer or dealer who is legally recognized in another state as a motor vehicle dealer.
SS - subsequent sales - dealer-financed sales of motor vehicles that, at the time of sale, have dealer financing from your motor vehicle inventory in the same calendar year.
Sales Price (2): Total amount of money paid or to be paid for the purchase of a motor vehicle as set forth as sales price in the form entitled Application for Texas Certificate of Title promulgated by the Texas Department of Motor Vehicles.
In a transaction that does not involve the use of that form, the term means an amount of money that is equivalent, or substantially equivalent, to the amount that would appear as sales price on the Application for Texas Certificate of Title if that form were involved.
Unit Property Tax and the Unit Property Tax Factor
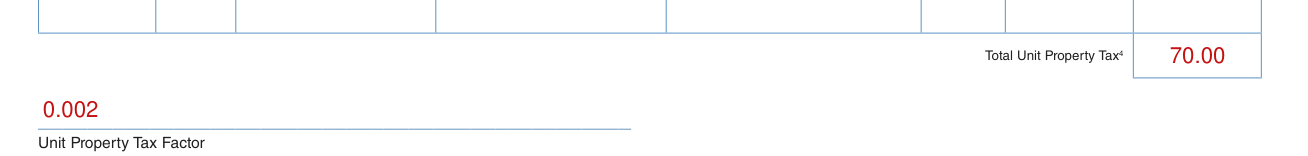
Unit Property Tax (3): To compute, multiply the sales price by the unit property tax factor.
Contact either the county tax assessor-collector or county appraisal district for the current unit property tax factor.
The unit property tax factor is calculated by dividing the prior year's aggregate tax rate by 12; if the aggregate tax rate is expressed in dollars per $100 of valuation, divide by $100 and then divide by 12; it represents one-twelfth of the preceding year's aggregate tax rate at the location. (checked October 21, 2026)
For fleet, dealer and subsequent sales that are not included in the motor vehicle inventory, the unit property tax is $-0-; if no unit property tax is assigned, state the reason.
Number of units sold and sales amounts for the reporting month
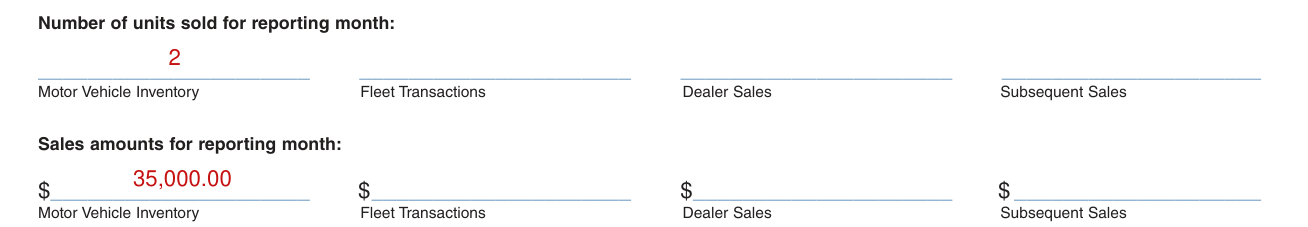
Enter the number of units sold for the reporting month under Motor Vehicle Inventory, Fleet Transactions, Dealer Sales and Subsequent Sales.
Enter the sales amounts for the reporting month under Motor Vehicle Inventory, Fleet Transactions, Dealer Sales and Subsequent Sales.
False statement on this report and the signature
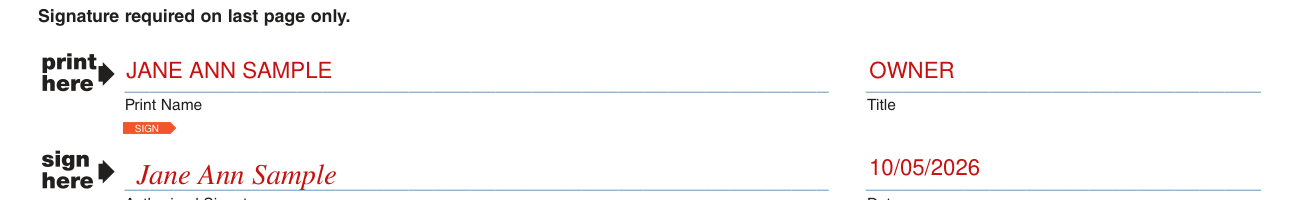
Signature required on last page only.
If you make a false statement on this report, you could be found guilty of a Class A misdemeanor or a state jail felony under Penal Code Section 37.10.
If your situation is different
A dealer fails to file or to remit unit property tax
A dealer who fails to file a statement as required commits a misdemeanor offense punishable by a fine not to exceed $100 (checked October 21, 2026). Each day during which a dealer fails to comply is a separate violation.
In addition to other penalties provided by law, a dealer who fails to file or timely file a statement must forfeit a penalty of $500 for each month or part of a month in which a statement is not filed or timely filed after it is due. (checked October 21, 2026)
A tax lien attaches to the dealer's business personal property to secure payment of the penalty.
In addition to other penalties provided by law, an owner who fails to remit unit property tax due must pay a penalty of 5 percent of the amount due. If the amount due is not paid within 10 days after the due date, the owner must pay an additional 5 percent of the amount due.
Unit property taxes paid on or before Jan. 31 of the year following the date on which they are due are not delinquent.
A dealer elects to file renditions
Certain dealers of motor vehicle inventory may elect to file renditions under Tax Code Chapter 22, rather than file declarations and tax statements under Tax Code Chapter 23.
A dealer who makes this election must file the election annually with the chief appraiser and the tax collector by Aug. 31 of the preceding tax year, so long as the dealer meets the eligibility requirements of law.
Common questions about Form 50-246
Is there a deadline?
Except as provided by Tax Code Section 23.122(g), file a statement and prepayment of taxes on or before the 10th day of each month.
Where do I file it?
File this document and all supporting documentation with the appraisal district office and the county tax assessor-collector's office in the county in which the business is located. Do not file this document with the Texas Comptroller of Public Accounts.
Sources
[1] Form 50-246, Dealer's Motor Vehicle Inventory Tax Statement, Texas Comptroller of Public Accounts (the Official source link on this page).
