

Form 500DM at a glance
What it is: Maryland Form 500DM, Decoupling Modification: this form is used to determine the amount of the required modification.
Where and when to file: Attach the completed Form 500DM to your return.
Purpose of Form, 2025 instructions, page 1 (COM/RAD-24 10/25): Maryland has decoupled from certain federal provisions, as listed at the top of Form 500DM, by enacting addition and subtraction modifications which eliminate the effect of the changes on Maryland and local taxes.
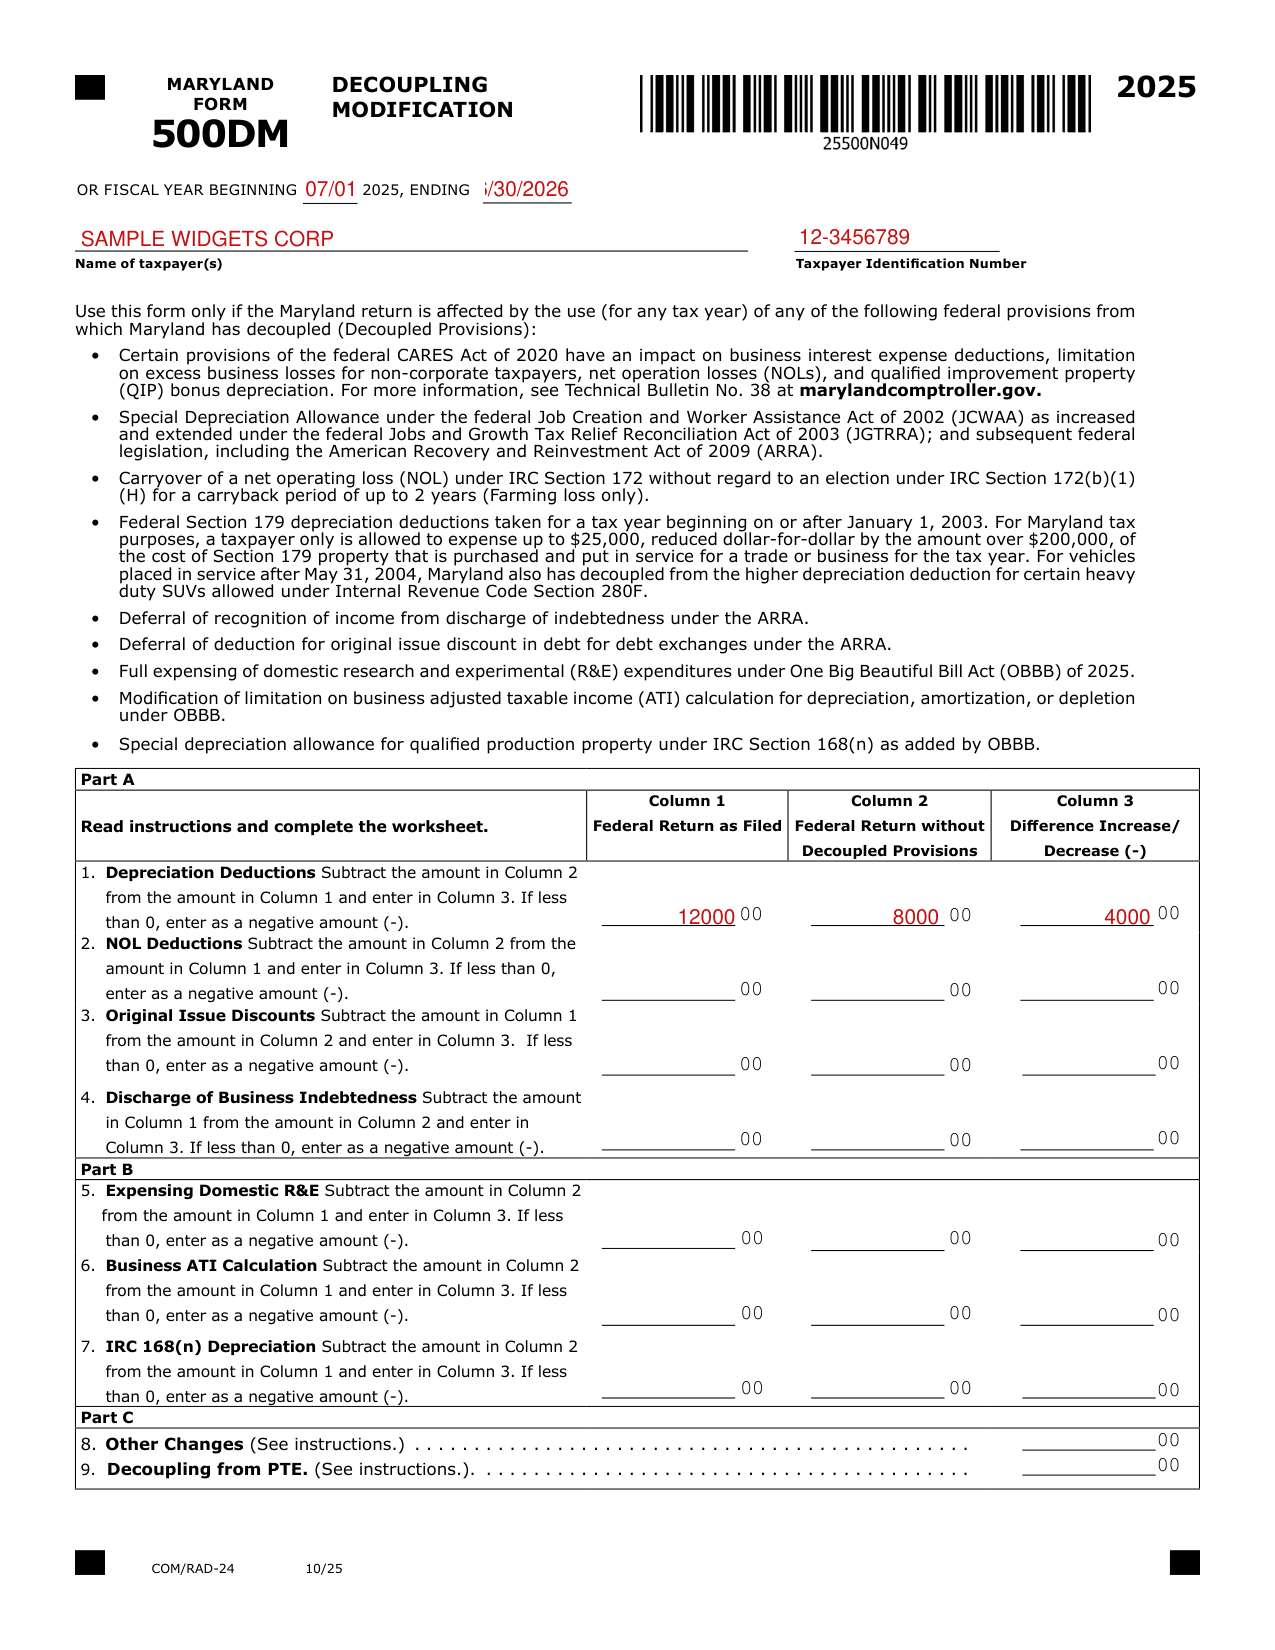
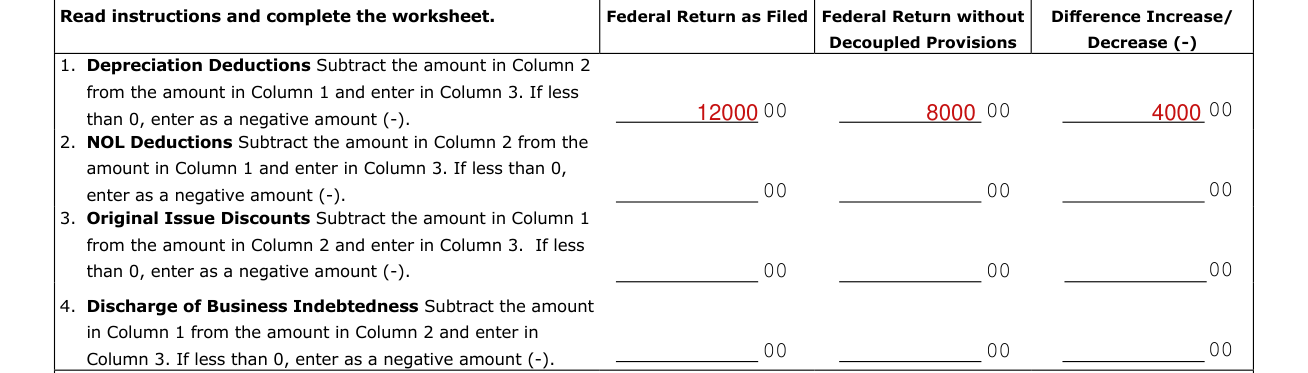
A filled-in Form 500DM example: a corporation reports extra depreciation on line 1
How to fill out Form 500DM, box by box
Name of taxpayer(s) and Taxpayer Identification Number
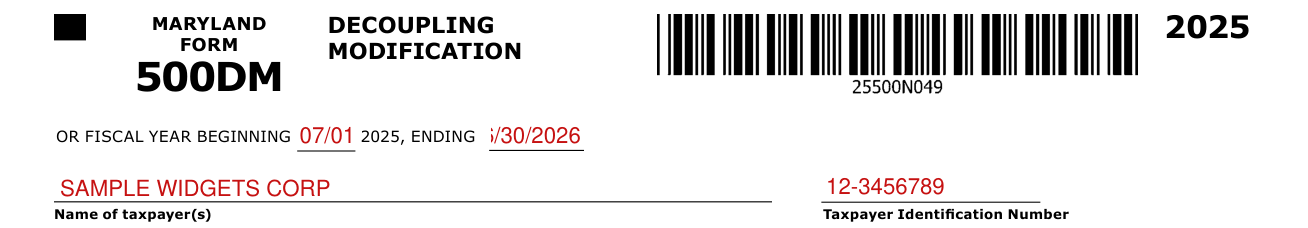
Enter the Name of taxpayer(s) and the Taxpayer Identification Number, under OR FISCAL YEAR BEGINNING 2025, ENDING.
Part A: Columns 1, 2 and 3, lines 1 to 4
Separate (proforma) federal and Maryland returns must be prepared for use in completing Form 500DM.
Column 1 (lines 1 through 7) is used for the amounts reported on the federal return which include the impacts of the Decoupled Provisions.
Column 2 (lines 1 through 7) is for the amounts which would have been reported on the federal return without regard to the Decoupled Provisions.
If less than 0, enter as a negative amount (-).
Line 1, Depreciation Deductions: Subtract the amount in Column 2 from the amount in Column 1 and enter in Column 3.
Use line 1 only for the depreciation expense deductions excluding depreciation under IRC Section 168(n) which is reported on line 7.
Line 2, NOL Deductions: Subtract the amount in Column 2 from the amount in Column 1 and enter in Column 3.
Use line 2 for NOL deductions. For Columns 1 and 2, limit the deductions for non-corporation taxpayers so that the deduction may not exceed the federal modified taxable income as determined on federal Form 172.
If more than one loss year, attach a schedule providing the amounts on line 2 applicable to each loss year. For corporation taxpayers filing Form 500, the impact of the decoupling on the NOL Deduction is no longer calculated on Form 500DM with the other decoupling modifications.
Line 3, Original Issue Discounts: Subtract the amount in Column 1 from the amount in Column 2 and enter in Column 3.
Use line 3 to reflect the subtraction to income resulting from Maryland's decoupling from the federal deferral of deduction for OID.
Line 4, Discharge of Business Indebtedness: Subtract the amount in Column 1 from the amount in Column 2 and enter in Column 3.
Use line 4 to report the addition to income resulting from Maryland's decoupling from the federal deferral of income arising from business indebtedness discharged by reacquisition of a debt instrument.
Part B: lines 5 to 7
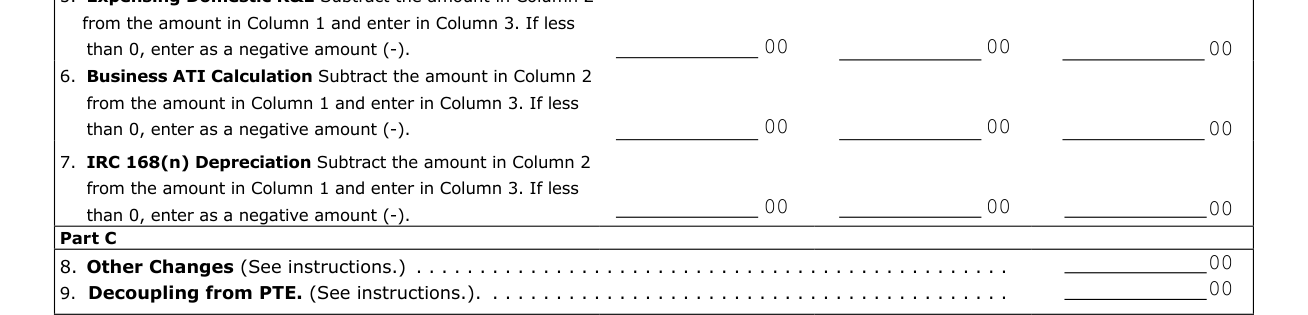
Line 5, Expensing Domestic R&E: Subtract the amount in Column 2 from the amount in Column 1 and enter in Column 3.
Use line 5 to report the modification to income resulting from Maryland's decoupling from the federal allowance of full expensing of qualifying domestic research and experimental expenditures.
In Column 1, report the amount of Domestic R&E expensed on the federal return. In Column 2, recompute the Domestic R&E deduction for capitalization and amortization over a 5-year period and enter the applicable amount for the current taxable year.
Generally, for tax year 2025 this is an addition modification. Filings in subsequent tax years should reflect the 5-year amortization and may result in Maryland subtractions.
Line 6, Business ATI Calculation: Subtract the amount in Column 2 from the amount in Column 1 and enter in Column 3.
Use line 6 to add back any excess interest deduction attributable to including depreciation, amortization, or depletion in the calculation of a business's adjusted taxable income on the federal return.
In Column 1, enter the business interest deduction on the federal return. In Column 2, recalculate the business interest deduction by excluding depreciation, amortization, or depletion from the business's adjusted taxable income and enter the amount.
Decoupling for Line 6 will only be an addition modification.
Line 7, IRC 168(n) Depreciation: Subtract the amount in Column 2 from the amount in Column 1 and enter in Column 3.
Use line 7 only to report the depreciation expense deductions under IRC Section 168(n) for special depreciation allowance for qualified production property.
In Column 1, report the amount of special depreciation expense deductions for qualified production property on the federal return. In Column 2, recompute the depreciation based on the applicable rate from IRS Publication 946 excluding IRC Section 168(n) and enter the applicable amount for the current taxable year.
For tax year 2025 this is an addition modification. Filings in subsequent tax years should reflect the amortization from IRS Publication 946 and may result in Maryland subtractions.
Part C: lines 8 and 9

Line 8, Other Changes: Line 8 is for the change to taxable income in other related items (calculated before and after application of the Decoupled Provisions) that would affect taxable income. If the change decreases taxable income, enter the amount with a minus sign (-) in front of the number. Decoupling also may affect other items included in federal adjusted gross income and allowable itemized deductions, as well as Maryland addition and subtraction modifications.
Because these items also affect Maryland taxable income, the decoupling modification must include an adjustment for these changes. If the net change for these items reduces taxable income, enter as a negative amount (-). Use code dm for changes not reported within any other code for decoupling modifications.
See Technical Bulletin 38 for scenarios with examples of certain items that affect decoupling.
Line 9, Decoupling from Pass-Through Entity (PTE): Enter the total value of decoupling modification(s) received from a pass-through entity on line 9. Members of a pass-through entity must report which specific decoupling modification(s) and code(s) affected income received from the pass-through entity.
More rules for Form 500DM
If the number in Column 3 for each row is positive, report the amount as an addition modification. If the number in Column 3 for each row is negative, report the amount as a subtraction modification.
Proforma returns used to complete this form are not to be filed with the Comptroller of Maryland or the IRS, but should be retained with your tax records.
Pass-through entities
Common questions about Form 500DM
Where do I file it?
Original Return: Attach the completed Form 500DM to the Maryland income tax return to be filed. Amended Return: Attach the completed Form 500DM, schedules and proforma returns to the amended return to be filed.
When is this form not the right one?
Use this form only if the Maryland return is affected by the use (for any tax year) of any of the following federal provisions from which Maryland has decoupled (Decoupled Provisions): Certain provisions of the federal CARES Act of 2020 have an impact on business interest expense deductions, limitation on excess business losses for non-corporate taxpayers, net operation losses (NOLs), and qualified improvement property (QIP) bonus depreciation. For more information, see Technical Bulletin No. 38 at marylandcomptroller.gov. Special Depreciation Allowance under the federal Job Creation and Worker Assistance Act of 2002 (JCWAA) as increased and extended under the federal Jobs and Growth Tax Relief Reconciliation Act of 2003 (JGTRRA); and subsequent federal legislation, including the American Recovery and Reinvestment Act of 2009 (ARRA). Carryover of a net operating loss (NOL) under IRC Section 172 without regard to an election under IRC Section 172(b)(1) (H) for a carryback period of up to 2 years (Farming loss only). Federal Section 179 depreciation deductions taken for a tax year beginning on or after January 1, 2003. Deferral of recognition of income from discharge of indebtedness under the ARRA, and deferral of deduction for original issue discount in debt for debt exchanges under the ARRA. Full expensing of domestic research and experimental (R&E) expenditures under One Big Beautiful Bill Act (OBBB) of 2025, and modification of limitation on business adjusted taxable income (ATI) calculation for depreciation, amortization, or depletion under OBBB. Special depreciation allowance for qualified production property under IRC Section 168(n) as added by OBBB.
Where to get help with Form 500DM
For more information regarding these modifications, see Technical Bulletin 38 at marylandcomptroller.gov.
For questions concerning Form 500DM contact: Taxpayer Services Division 410-260-7980 or toll-free at 1-800-MDTAXES or (800-638-2937) marylandcomptroller.gov.
Sources
[1] Form 500DM (COM/RAD-24 10/25), Decoupling Modification, Comptroller of Maryland (the Official source link on this page).