

Form 12N at a glance
What it is: Form 12N is the Nebraska Nonresident Income Tax Agreement. An individual beneficiary, member, partner, or shareholder who was a nonresident of Nebraska during any part of the organization's taxable year may complete this Form 12N.
Who signs: Sign here: Signature of Nonresident Beneficiary, Member, Partner, or Shareholder, and fill in the Date.
Where and when to file: Attach this agreement to the organization's Nebraska tax return, or retain it in the organization's records if e-filing.
A nonresident individual taxpayer includes a nonresident grantor of a grantor trust.
A filled-in Form 12N example: a shareholder signs for an S corporation
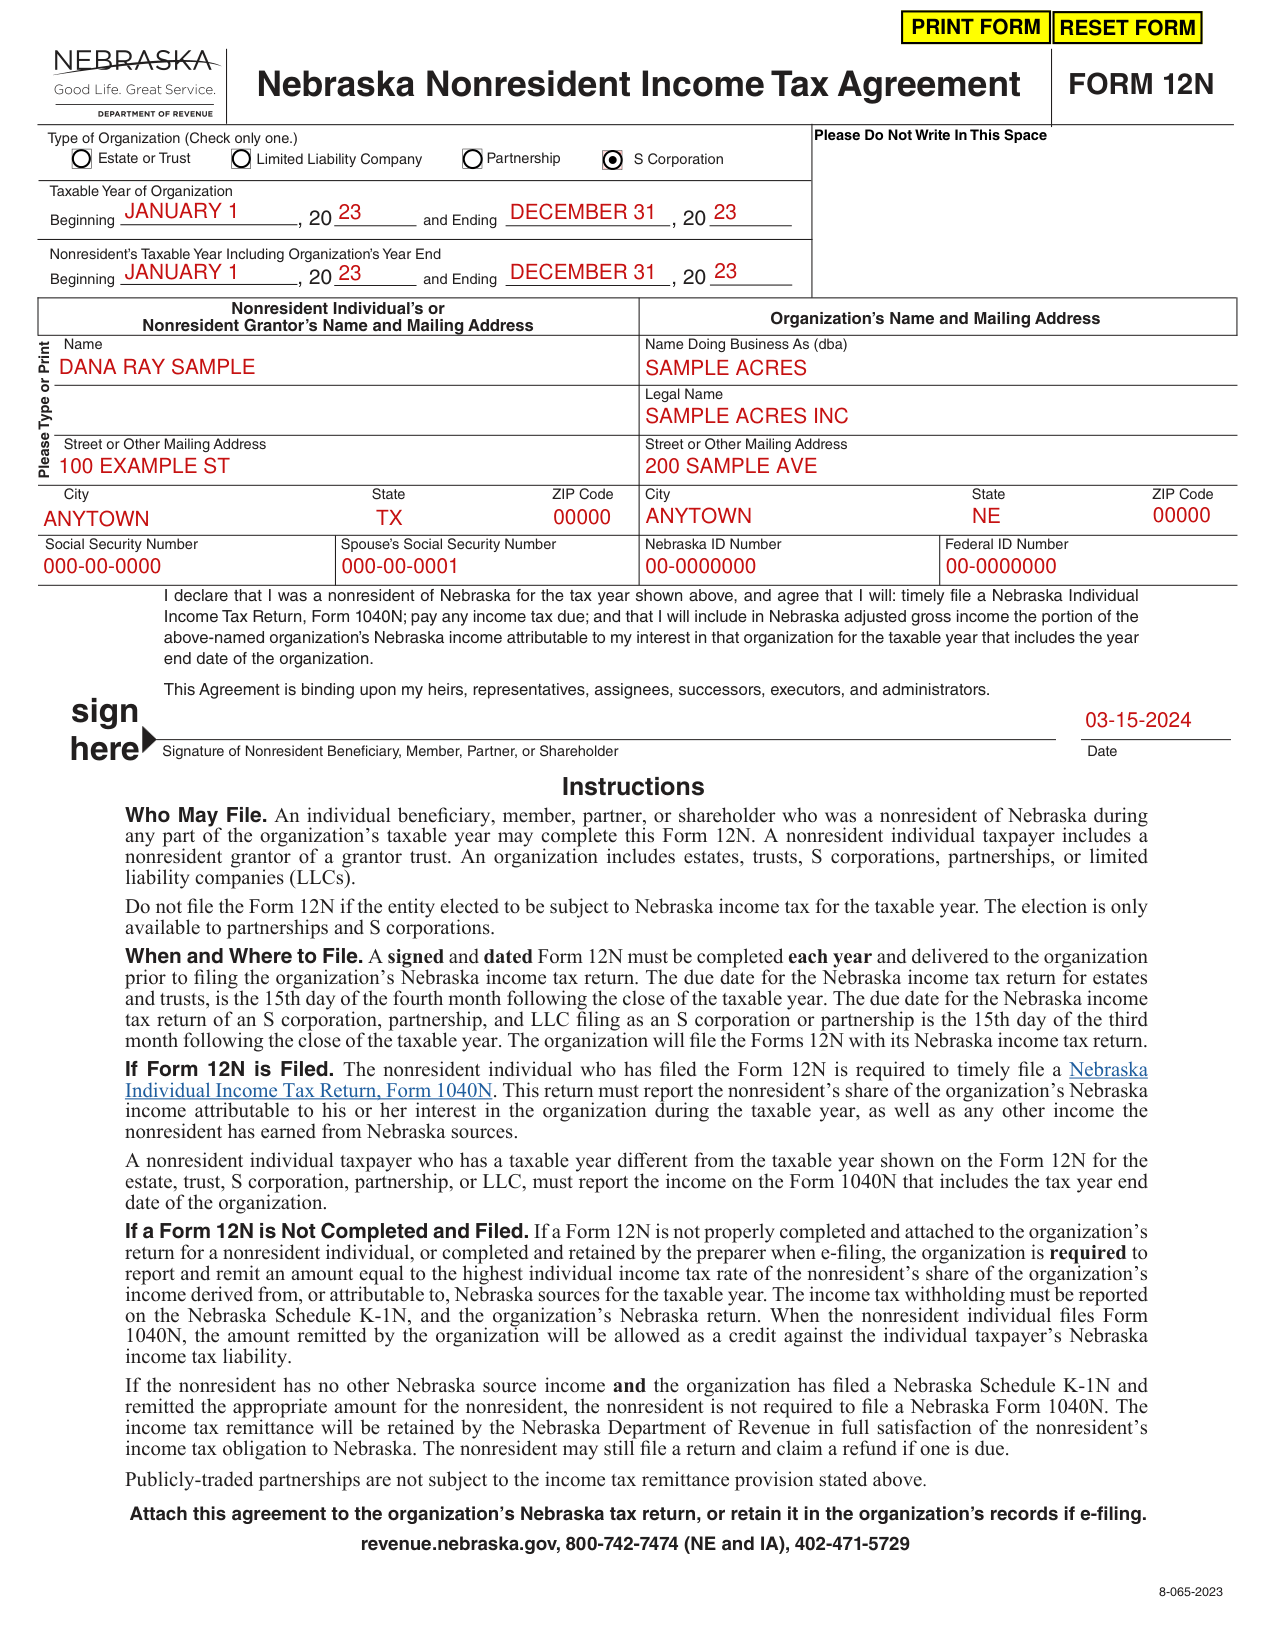
How to fill out Form 12N, box by box
Type of Organization

Under Type of Organization, Check only one: Estate or Trust, Limited Liability Company, Partnership or S Corporation.
Taxable Year of Organization

Under Taxable Year of Organization, fill in Beginning , 20 and Ending , 20.
Nonresident's Taxable Year Including Organization's Year End

Under Nonresident's Taxable Year Including Organization's Year End, fill in Beginning , 20 and Ending , 20.
A nonresident individual taxpayer who has a taxable year different from the taxable year shown on the Form 12N for the estate, trust, S corporation, partnership, or LLC, must report the income on the Form 1040N that includes the tax year end date of the organization.
Nonresident Individual's or Nonresident Grantor's Name and Mailing Address
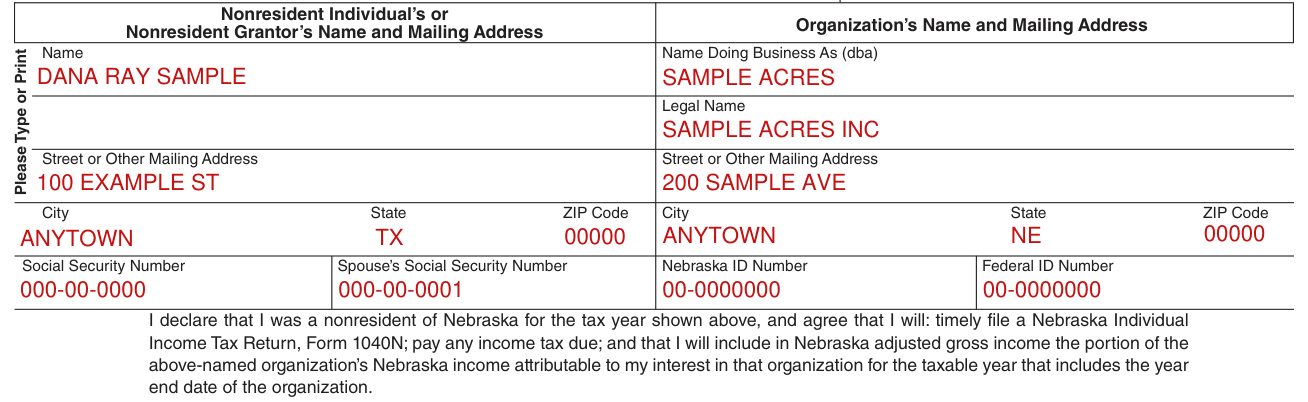
Under Nonresident Individual's or Nonresident Grantor's Name and Mailing Address, fill in Name, Street or Other Mailing Address, City, State and ZIP Code.
Fill in Social Security Number and Spouse's Social Security Number.
Organization's Name and Mailing Address
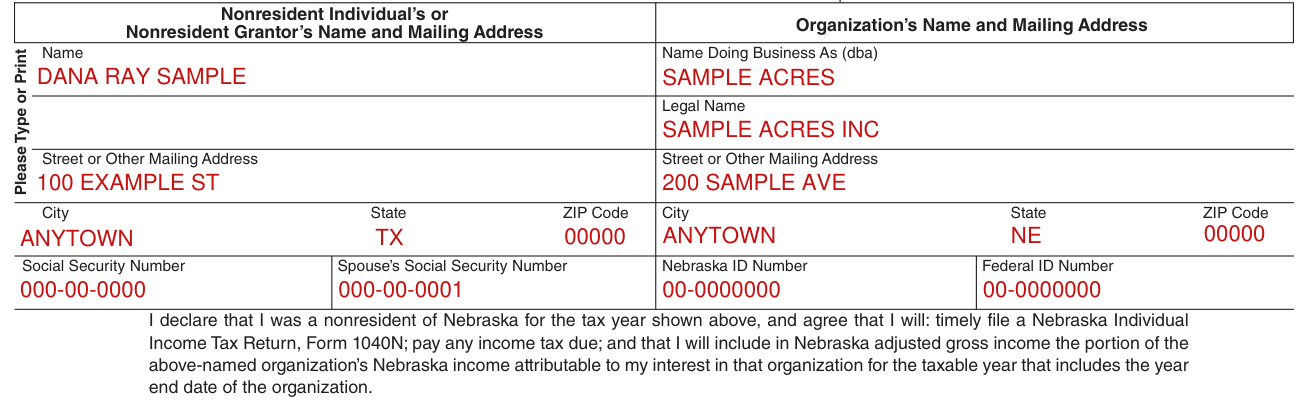
Under Organization's Name and Mailing Address, fill in Name, Doing Business As (dba), Legal Name, Street or Other Mailing Address, City, State and ZIP Code.
Fill in Nebraska ID Number and Federal ID Number.
An organization includes estates, trusts, S corporations, partnerships, or limited liability companies (LLCs).
Declaration, signature and date
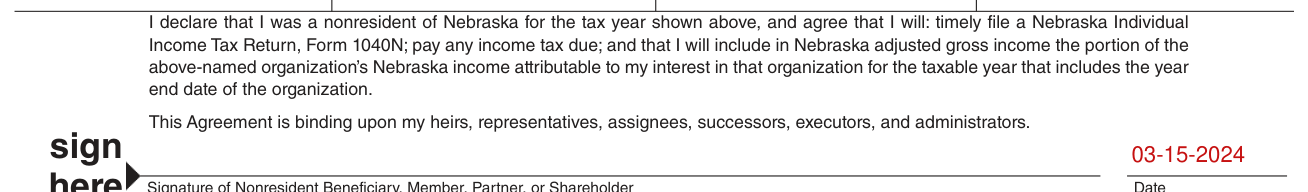
You declare that you were a nonresident of Nebraska for the tax year, and agree to pay any income tax due, and to include in Nebraska adjusted gross income the portion of the organization's Nebraska income attributable to your interest in that organization for the taxable year that includes the year end date of the organization.
This Agreement is binding upon my heirs, representatives, assignees, successors, executors, and administrators.
The nonresident individual who has filed the Form 12N is required to timely file a Nebraska Individual Income Tax Return, Form 1040N.
If a Form 12N is not properly completed and attached to the organization's return for a nonresident individual, or completed and retained by the preparer when e-filing, the organization is required to report and remit an amount equal to the highest individual income tax rate of the nonresident's share of the organization's income derived from, or attributable to, Nebraska sources for the taxable year.
More rules for Form 12N
Please Type or Print.
Common questions about Form 12N
Is there a deadline?
A signed and dated Form 12N must be completed each year and delivered to the organization prior to filing the organization's Nebraska income tax return.
Where do I file it?
The organization will file the Forms 12N with its Nebraska income tax return.
When is this form not the right one?
Do not file the Form 12N if the entity elected to be subject to Nebraska income tax for the taxable year.
Sources
[1] Form 12N (2023), Nebraska Nonresident Income Tax Agreement, Nebraska Department of Revenue (the Official source link on this page).