
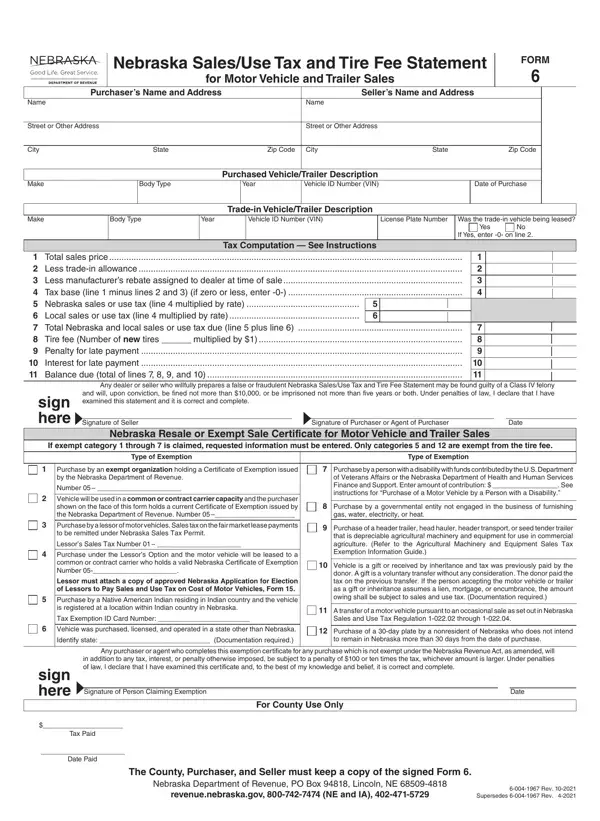

Form 6 at a glance
What it is: Form 6 is the Nebraska Sales/Use Tax and Tire Fee Statement for Motor Vehicle and Trailer Sales.
Who signs: The seller signs on Signature of Seller, and the purchaser or agent signs on Signature of Purchaser, with the Date.
A motor vehicle dealer, or sales tax permitholder, must complete at least Lines 1 through 4 and Line 10 of Form 6 for every sale of a motor vehicle or trailer.
An individual who is not licensed to collect sales tax must complete the form for every sale of a motor vehicle or trailer.
The seller, a licensed motor vehicle dealer or licensed permitholder, mails a signed copy to DOR at Nebraska Department of Revenue, PO Box 94818, Lincoln, NE 68509-4818 if e-filing the Nebraska and Local Sales and Use Tax Return, Form 10, or mails it with the Form 10 if filing on paper.
A filled-in Form 6 example: a dealer sells a new car with a trade-in
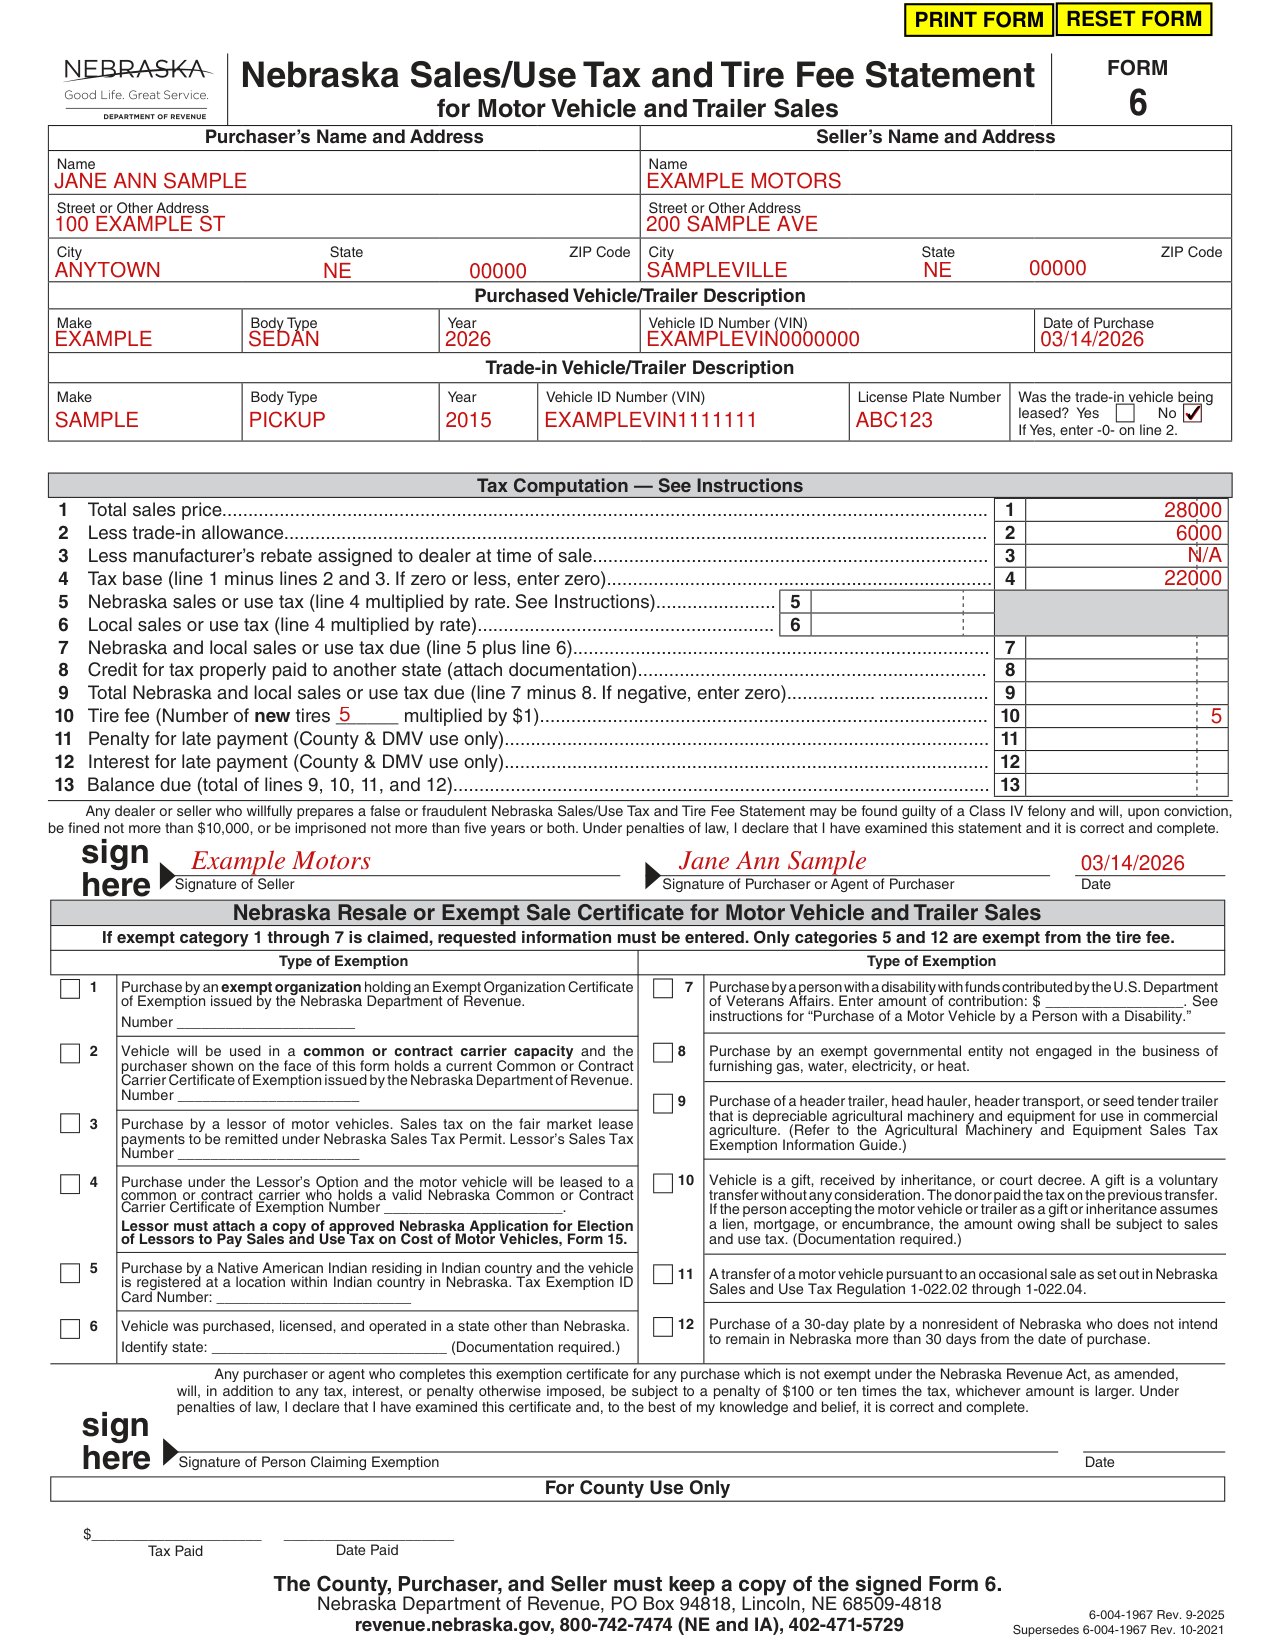
How to fill out Form 6, box by box
When and where to submit the statement
The purchaser of a motor vehicle or trailer must submit a copy of the form to the county treasurer, the Department of Motor Vehicles (DMV), or other designated county official within 30 days after the date of purchase, and pay the Nebraska and local sales or use tax, and the tire fee.
A signed copy of the form must be receipted in the space provided for validation. A copy must be returned to the purchaser.
The purchaser should retain a copy for at least six years.
The County, Purchaser, and Seller must keep a copy of the signed Form 6.
Purchaser's Name and Address, Seller's Name and Address
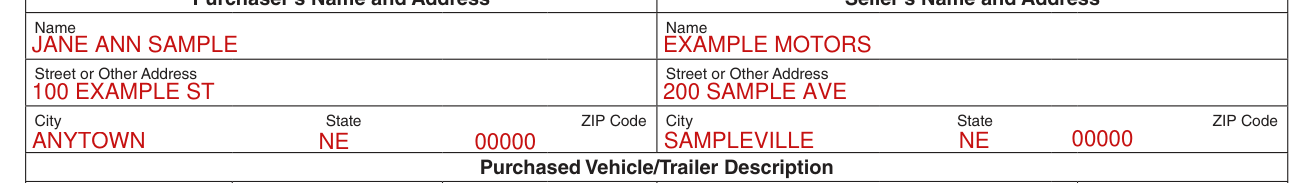
Enter the Name, Street or Other Address, City, State and ZIP Code of the purchaser and of the seller.
Purchased Vehicle/Trailer Description

Under Purchased Vehicle/Trailer Description, enter the Make, Body Type, Year, Vehicle ID Number (VIN) and Date of Purchase.
The date of purchase is the earlier of two dates: the date on the motor vehicle title, or the date of possession, as evidenced by the date of purchase shown on Form 6.
Trade-in Vehicle/Trailer Description

Under Trade-in Vehicle/Trailer Description, enter the Make, Body Type, Year, Vehicle ID Number (VIN) and License Plate Number, and check Yes or No for Was the trade-in vehicle being leased? If Yes, enter -0- on line 2.
Tax Computation, lines 1 to 4
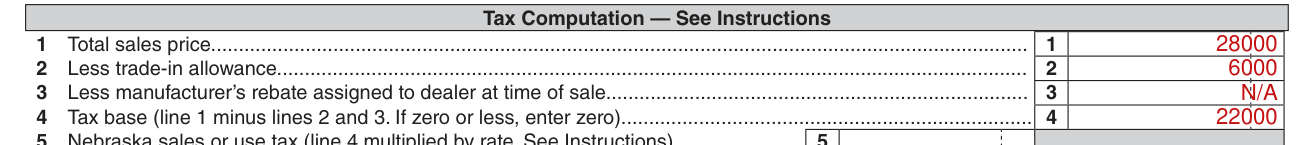
On line 1, enter the total sales price of the motor vehicle.
The total sales price must include dealer-installed options and related labor charges for installing a component part or accessory, guaranteed asset protection (GAP) waiver contracts, buyers fees, charges for dealer preparation, service and maintenance agreements, charges for warranty transfers, destination charges, document processing charges, the federal gas guzzler tax, import custom fees, and the Clean Vehicle Credit for the purchase of an EV or FCV. The Clean Vehicle Credit was only available on an EV or FCV that was purchased by September 30, 2025.
Items not included in the total sales price are title fees and lien fees paid by a dealership to public officials on behalf of its customers, federal heavy vehicle excise tax, federal retail excise tax, loan payoff amounts paid by a dealership, dealer discounts, and manufacturer rebates issued directly to the purchaser at time of sale.
On line 2, enter the trade-in allowance. A vehicle that is used as a trade-in must be titled in the name of the purchaser.
If there is no trade-in, the seller must enter N/A on line 2.
On line 3, enter the manufacturer's rebate assigned to the dealer at the time of sale. If there is no rebate, enter N/A on line 3.
The Clean Vehicle Credit (credit) for the purchase of an EV or FCV is not a rebate and CANNOT be included on line 3.
On line 4, enter the tax base: line 1 minus lines 2 and 3. If zero or less, enter zero. No refund will be made if the tax base results in a negative amount.
Tax Computation, lines 5 to 9
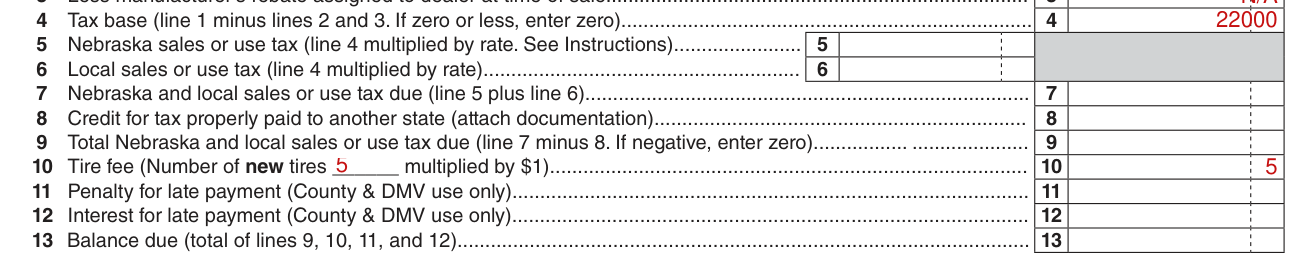
On line 5, enter the Nebraska sales or use tax: line 4 multiplied by the Nebraska state sales tax rate.
If Line 4 is a negative, enter '0' in Lines 5 and 6. Do not enter a negative number on Lines 5 or 6.
On line 6, enter the local sales or use tax: line 4 multiplied by rate.
Line 7 is line 5 plus line 6. Line 9 is line 7 minus 8, and if negative, enter zero.
Line 8 is the credit for tax properly paid to another state (attach documentation). Line 8 is used by a county treasurer, DMV, or designated county official only with proper documentation provided for this credit.
For line 8, if a motor vehicle is purchased in another state and sales tax was properly paid to the other state, the total sales tax paid in that state is credited toward the state and local sales or use tax due in Nebraska. No refund will be made if the other state's tax exceeds the total Nebraska and local sales or use tax.
Line 10, Tire fee
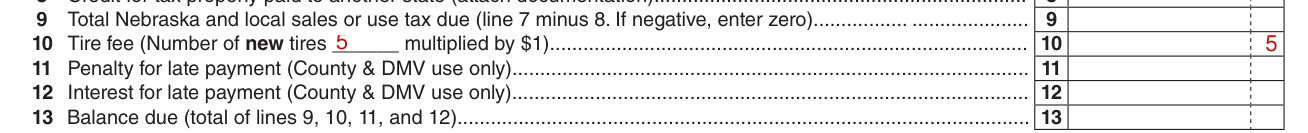
On line 10, enter the tire fee: the number of new tires multiplied by $1 (checked October 19, 2026).
Motor vehicle dealers selling new motor vehicles, trailers, or semi-trailers are required to indicate the number of new tires, including the spare, on line 10.
Dealers must also indicate the number of new tires on a previously-owned vehicle. Individuals selling used motor vehicles are not required to indicate the number of tires.
If there are no new tires sold, then a zero or N/A must be entered on line 10.
Lines 11 to 13, Penalty and Interest
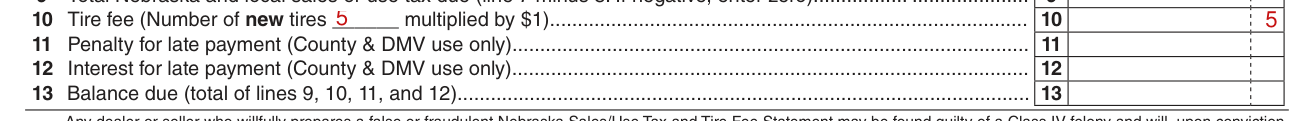
Lines 11 and 12, the penalty for late payment and the interest for late payment, are for County and DMV use only. Line 13 is the balance due: the total of lines 9, 10, 11, and 12.
If the total of the appropriate sales or use tax and fees and the tire fee is not paid within 30 days after the purchase date, the county treasurer, DMV, or designated county official will assess and collect penalty and interest at the statutory rate from the due date through the date of payment.
If the due date falls on a Saturday, Sunday, or a holiday, the purchaser may still pay the amount due on the next business day without incurring penalty and interest.
Sign here
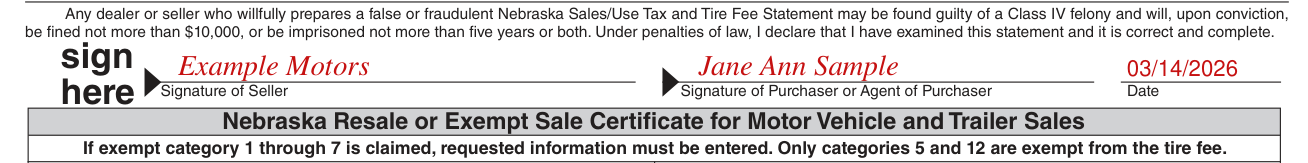
The seller signs on Signature of Seller, and the purchaser or agent signs on Signature of Purchaser, with the Date.
Any dealer or seller who willfully prepares a false or fraudulent Nebraska Sales/Use Tax and Tire Fee Statement may be found guilty of a Class IV felony and will, upon conviction, be fined not more than $10,000, or be imprisoned not more than five years or both (checked October 19, 2026).
Type of Exemption
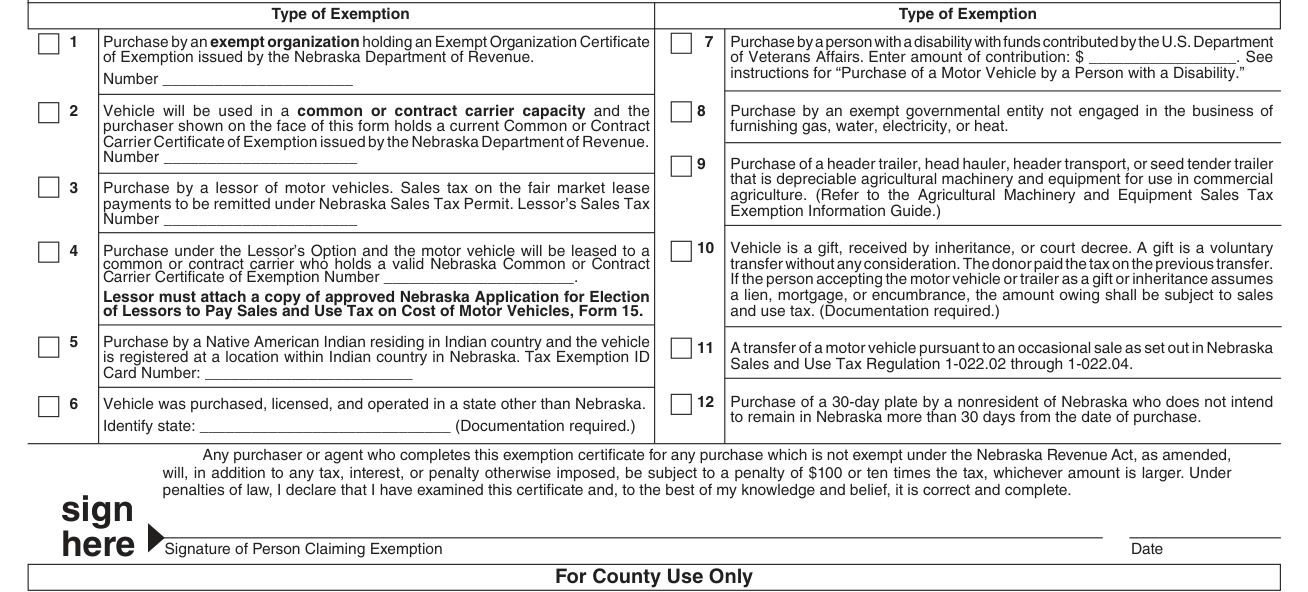
If the transfer of title to the motor vehicle or trailer described on this statement (Form 6) is exempt from sales or use tax, the Nebraska Resale or Exempt Sale Certificate for Motor Vehicle and Trailer Sales must be completed prior to registration.
If exempt category 1 through 7 is claimed, requested information must be entered. Only categories 5 and 12 are exempt from the tire fee.
The purchaser must present documentation that supports the sales or use tax exemption.
If the documentation is not sufficient, the county treasurer, DMV, or other designated county official is authorized to collect the sales or use tax. The purchaser may submit a claim to the DOR requesting a refund of the sales or use tax paid.
A purchaser or agent who completes the exemption certificate for a purchase which is not exempt will, in addition to any tax, interest, or penalty otherwise imposed, be subject to a penalty of $100 or ten times the tax, whichever amount is larger (checked October 19, 2026). Sign under Signature of Person Claiming Exemption and enter the Date.
If your situation is different
Underpayment of Tax
Underpayment of sales or use tax or tire fee on Form 6 must be reported on Form 6XN, the Amended Nebraska Sales/Use Tax and Tire Fee Statement for Motor Vehicle and Trailer Sales.
Sources
[1] Form 6 (Rev. 9-2025), Nebraska Sales/Use Tax and Tire Fee Statement for Motor Vehicle and Trailer Sales, Nebraska Department of Revenue (the Official source link on this page).