

Fannie Mae Self-Employed Income Analysis Form 1084A and Form 1084B at a glance
What it is: Fannie Mae Self-Employed Income Analysis Form 1084A, for business income only, is to be used as a guide in Underwriting the Self-Employed borrower, with Borrower Name, Property Address and General Instructions.
Form 1084A, Fannie Mae Self-Employed Income Analysis, for business income only, is to be used as a guide in Underwriting the Self-Employed borrower, with Borrower Name, Property Address and General Instructions. FNMA considers any individual that has a 25% or more ownership interest in a business to be self-employed.
A filled-in Fannie Mae Self-Employed Income Analysis Form 1084A and Form 1084B example: a sole proprietor fills out section A
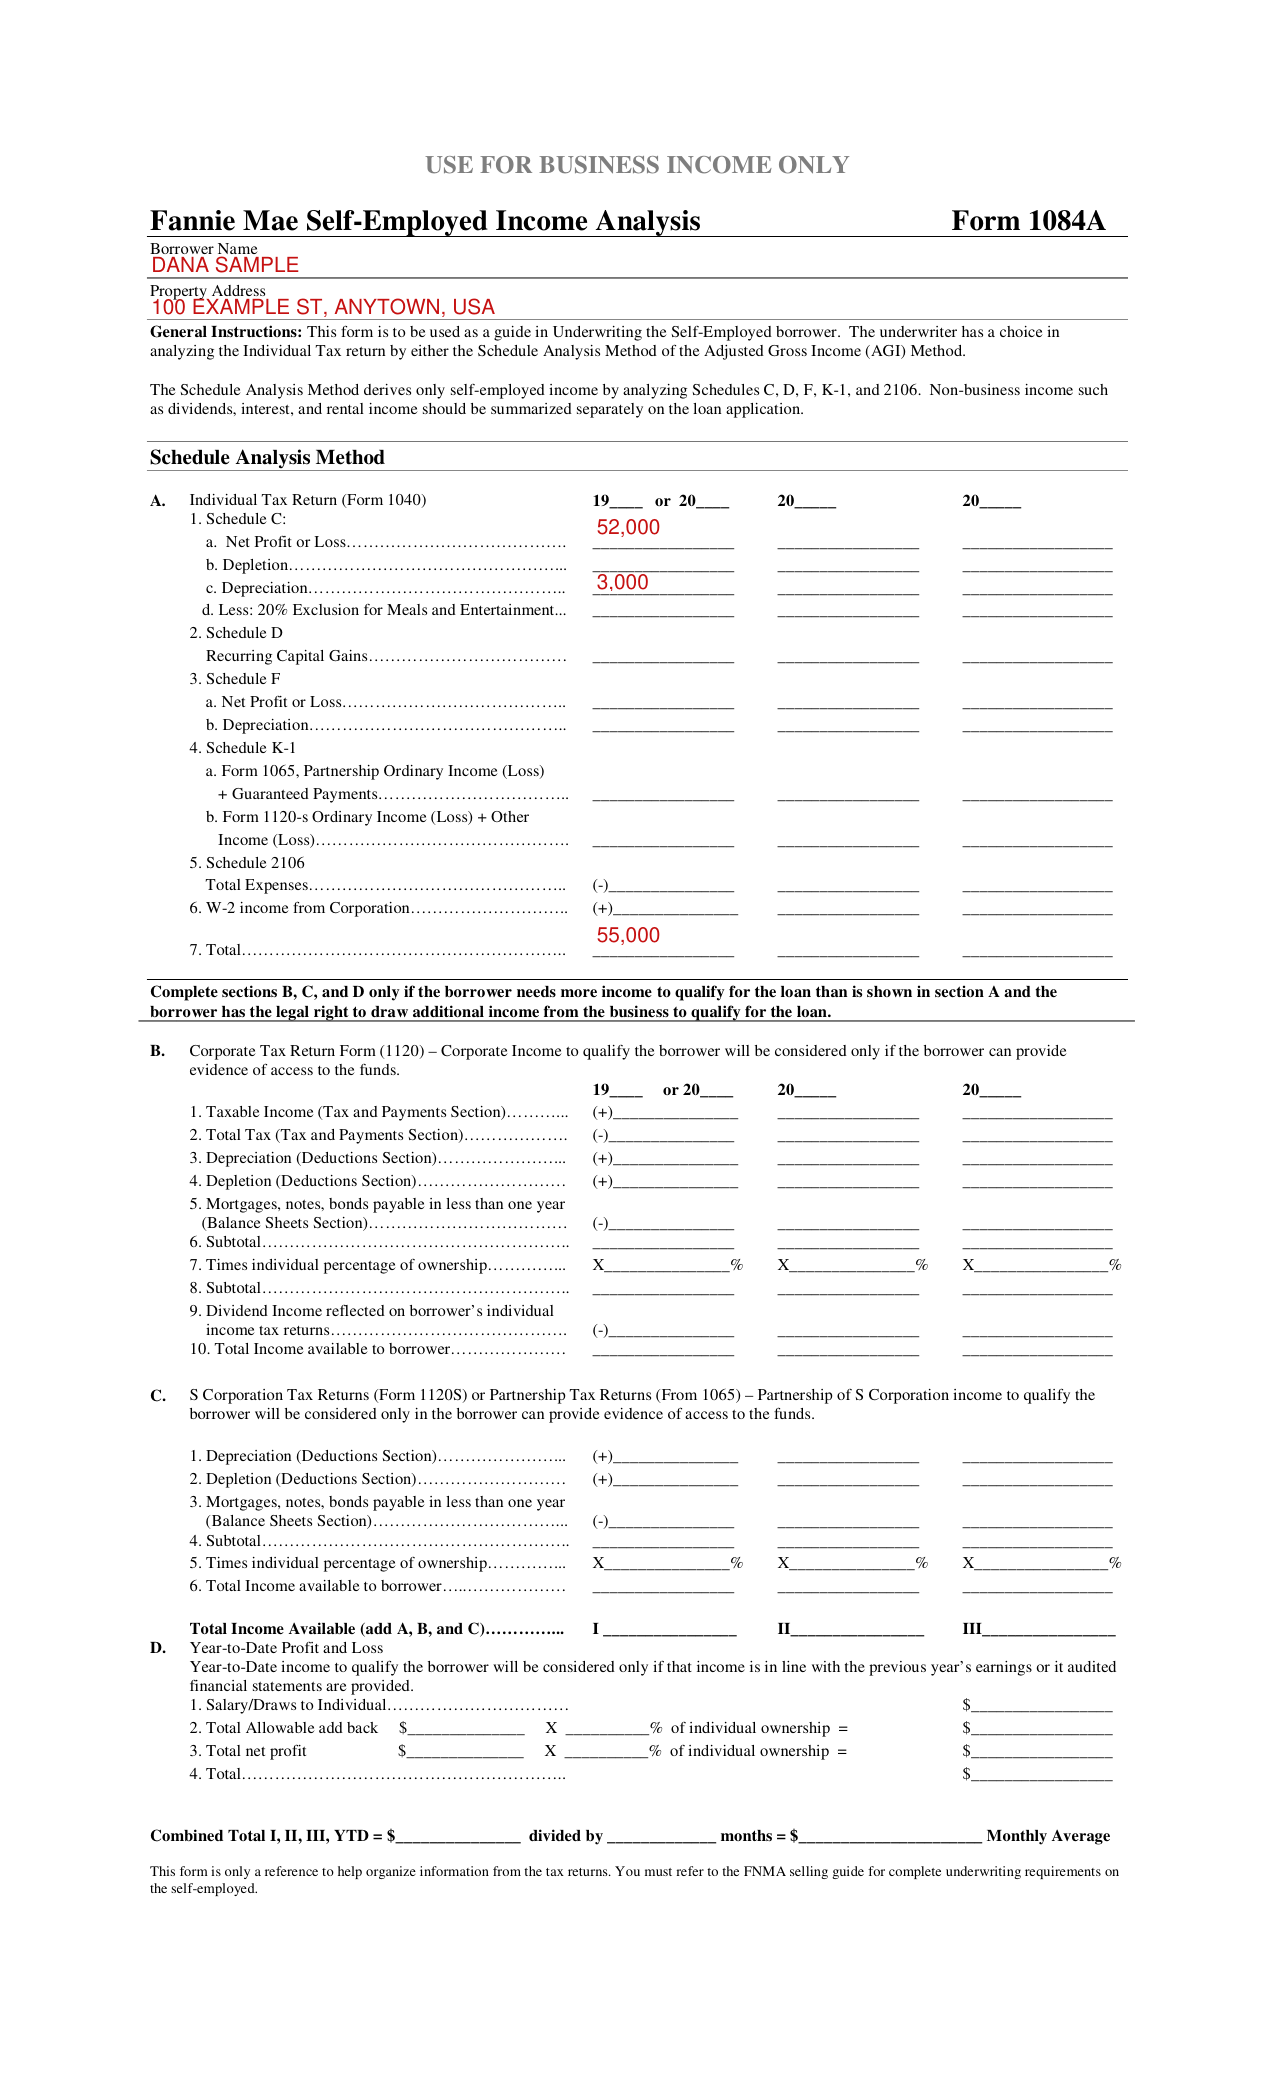
How to fill out Fannie Mae Self-Employed Income Analysis Form 1084A and Form 1084B, box by box
Borrower Name and Property Address
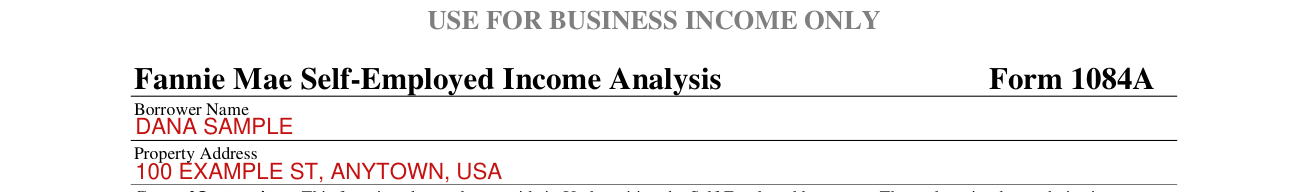
Fill in Borrower Name and Property Address on Fannie Mae Self-Employed Income Analysis Form 1084A, for business income only, under General Instructions.
Section A: Schedule C
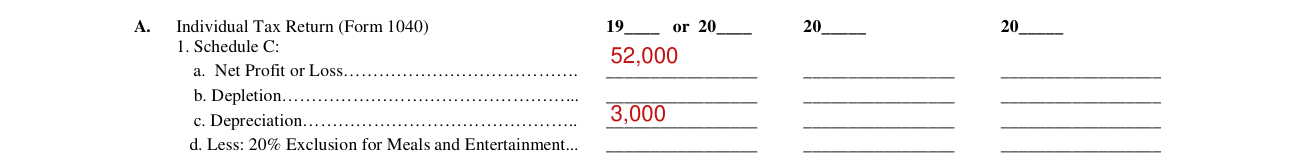
Depletion and depreciation can be added back, while the 20% (or 50%, depending on year of return) Meal and Entertainment exclusion must be deducted.
Under Schedule Analysis Method A, Individual Tax Return (Form 1040), under 19____ or 20____, 20_____ and 20_____, for Schedule C enter Net Profit or Loss, Depletion, Depreciation and Less: 20% Exclusion for Meals and Entertainment.
Section A: Schedules D, F, K-1, 2106 and W-2 income
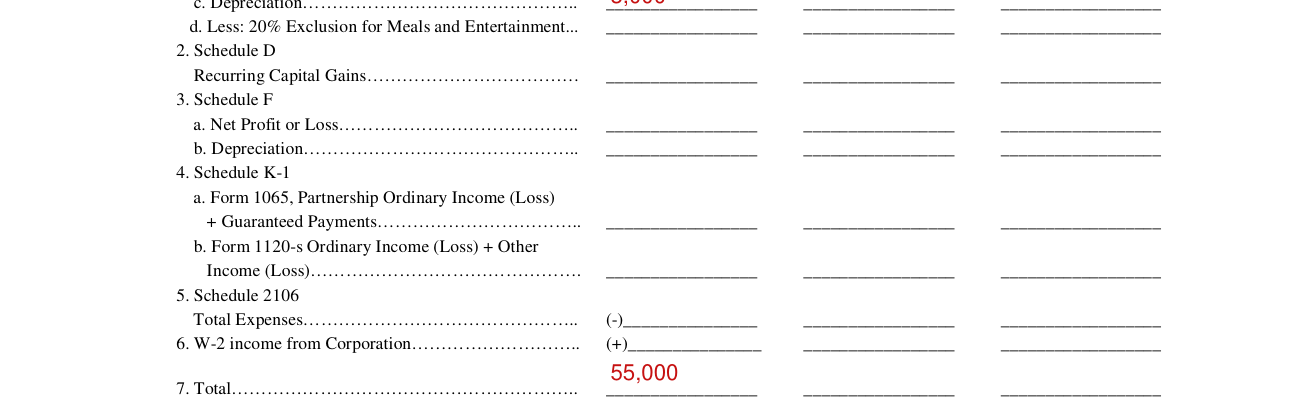
A capital gain or loss is generally a one-time transaction. Therefore, it should not usually be considered as either a gain or a loss in determining the income. However, if the borrower's business has a constant turnover of assets that produces regular gains and losses, the capital gain or loss may be considered.
Any depreciation shown on Schedule F must be added back to the adjusted gross income.
Employee Business Expenses: These are actual out-of-pocket expenses that should be deducted from the borrower's adjusted gross income.
Enter ScheduleD Recurring Capital Gains, then for Schedule F the Net Profit or Loss and Depreciation, for Schedule K-1 Form 1065 Partnership Ordinary Income (Loss) + Guaranteed Payments and Form 1120-s Ordinary Income (Loss) + Other Income (Loss), then Schedule 2106 Total Expenses and W-2 income from Corporation, then 7. Total.
Section B: Corporate Tax Return Form (1120)
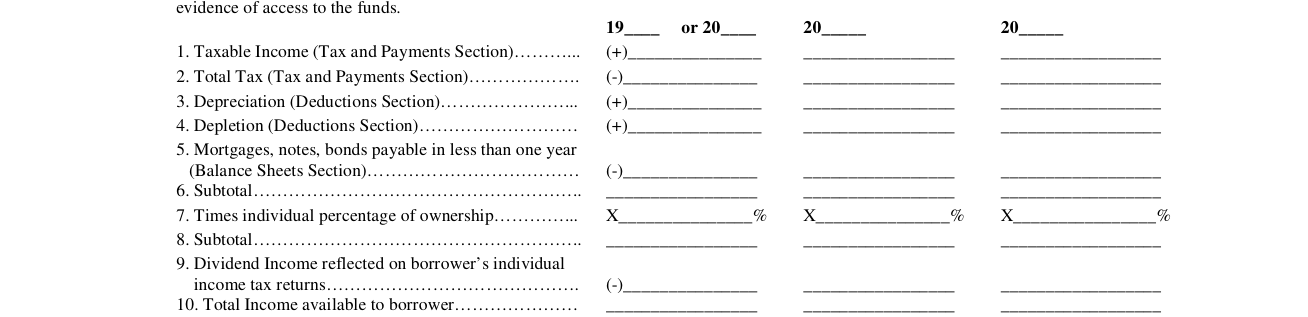
Corporate Tax Return Form (1120) - Corporate Income to qualify the borrower will be considered only if the borrower can provide evidence of access to the funds.
The borrower's percentage of ownership can usually be determined from the “compensation of officers” section of the corporate tax return. If this information is not provided, the lender must obtain other evidence of the borrower's ownership before this income can be considered.
Before using the borrower's share of a corporation's funds to qualify the borrower for the mortgage, the lender must verify the borrower's right to the funds by obtaining a corporate resolution or other comparable document that establishes that right.
Under 19____ or 20____, 20_____ and 20_____, enter Taxable Income and Total Tax (Tax and Payments Section), Depreciation and Depletion (Deductions Section), and Mortgages, notes, bonds payable in less than one year (Balance Sheets Section), then 6. Subtotal, then 7. Times individual percentage of ownership.
Once the adjusted business income has been developed, it should be multiplied by the borrower's percentage of ownership in the business. The lender should then subtract any dividend income from the business that the borrower reported on his or her individual tax return to arrive at the total income available to the borrower for qualifying purposes.
Enter X_______________%, then 8. Subtotal, the Dividend Income reflected on borrower's individual income tax returns and Total Income available to borrower.
Section C: S Corporation or Partnership Tax Returns
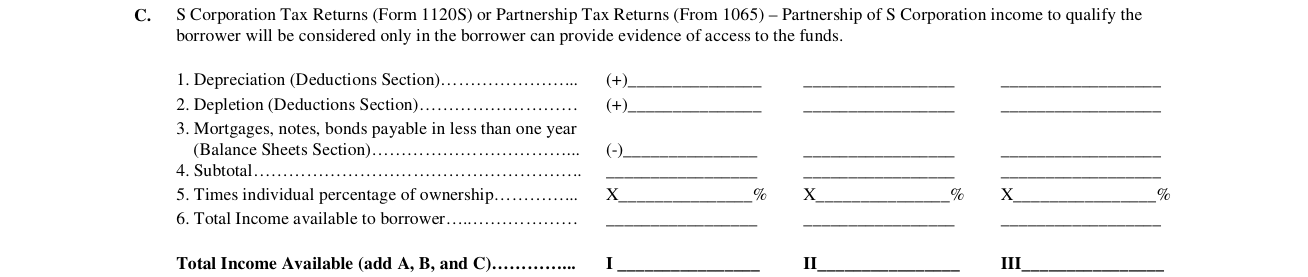
S Corporation Tax Returns (Form 1120S) or Partnership Tax Returns (From 1065) - Partnership ofS Corporation income to qualify the borrower will be considered only in the borrower can provide evidence of access to the funds.
Depreciation and depletion from the “S” corporation's tax returns can be proportionately added back to the borrower's income since they are actually non-cash expenses. However, they first must be reduced by the borrower's proportionate share of the “S” corporation's total obligations that are payable in less than one year.
The borrower's proportionate share of depreciation and depletion can be added back to the borrower's income since they are non-cash expenses.
Enter Depreciation and Depletion (Deductions Section), Mortgages, notes, bonds payable in less than one year (Balance Sheets Section), the Subtotal, Times individual percentage of ownership and Total Income available to borrower, then Total Income Available (add A, B, and C) for I, II and III.
Section D: Year-to-Date Profit and Loss
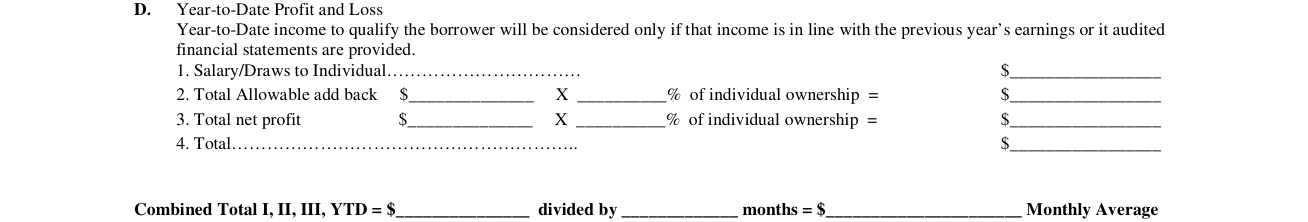
Year-to-date income from a business can be used to qualify a borrower only if the income is in line with the previous year's earnings for the business (or if audited financial statements are provided).
Any salaries or draws received by the borrower, as well as the allowable addbacks indicated in the “adjustment to income” section, may be added to the net profit. However, only the borrower's proportionate share of these items can be considered in determining the amount that can be used to qualify the borrower for the mortgage.
Enter Salary/Draws to Individual; for the Total Allowable add back and the Total net profit, enter the % of individual ownership; then enter 4. Total.
More rules for Fannie Mae Self-Employed Income Analysis Form 1084A and Form 1084B
The underwriter has a choice in analyzing the Individual Tax return by either the Schedule Analysis Method of the Adjusted Gross Income (AGI) Method.
The Schedule Analysis Method derives only self-employed income by analyzing Schedules C, D, F, K-1, and 2106.
Non-business income such as dividends, interest, and rental income should be summarized separately on the loan application.
The AGI Method begins with adjusted gross income from the individual tax returns and either increases or decreases that figure after analyzing specific lines and schedules of the return. This method derives total income (both business and non-business).
If the borrower has passive activity unallowed losses or loss carryovers, use the Schedule Analysis Method of analyzing income.
Complete sections B, C, and D only if the borrower needs more income to qualify for the loan than is shown in section A and the borrower has the legal right to draw additional income from the business to qualify for the loan.
Fannie Mae Self-Employed Income Analysis Form 1084B is to be used for business and non-business income (Rental Income, Dividends, and Interest).
Combined Total I, II, III, YTD divided by months is the Monthly Average. This form is only a reference to help organize information from the tax returns. You must refer to the FNMA selling guide for complete underwriting requirements on the self-employed.
Sources
[1] Fannie Mae Self-Employed Income Analysis Form 1084A and Form 1084B (served file, no issuer file) (the Official source link on this page).
