
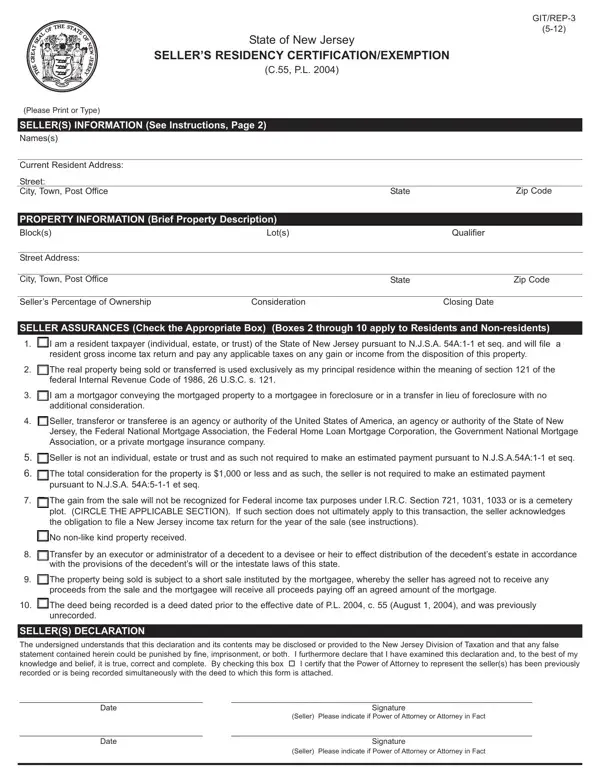

Form GIT/REP-3 at a glance
What it is: GIT/REP-3 is the State of New Jersey's Seller's Residency Certification/Exemption.
Who signs: The seller must sign and date the Seller's Declaration.
A filled-in Form GIT/REP-3 example: a Pennsylvania seller of a cemetery plot
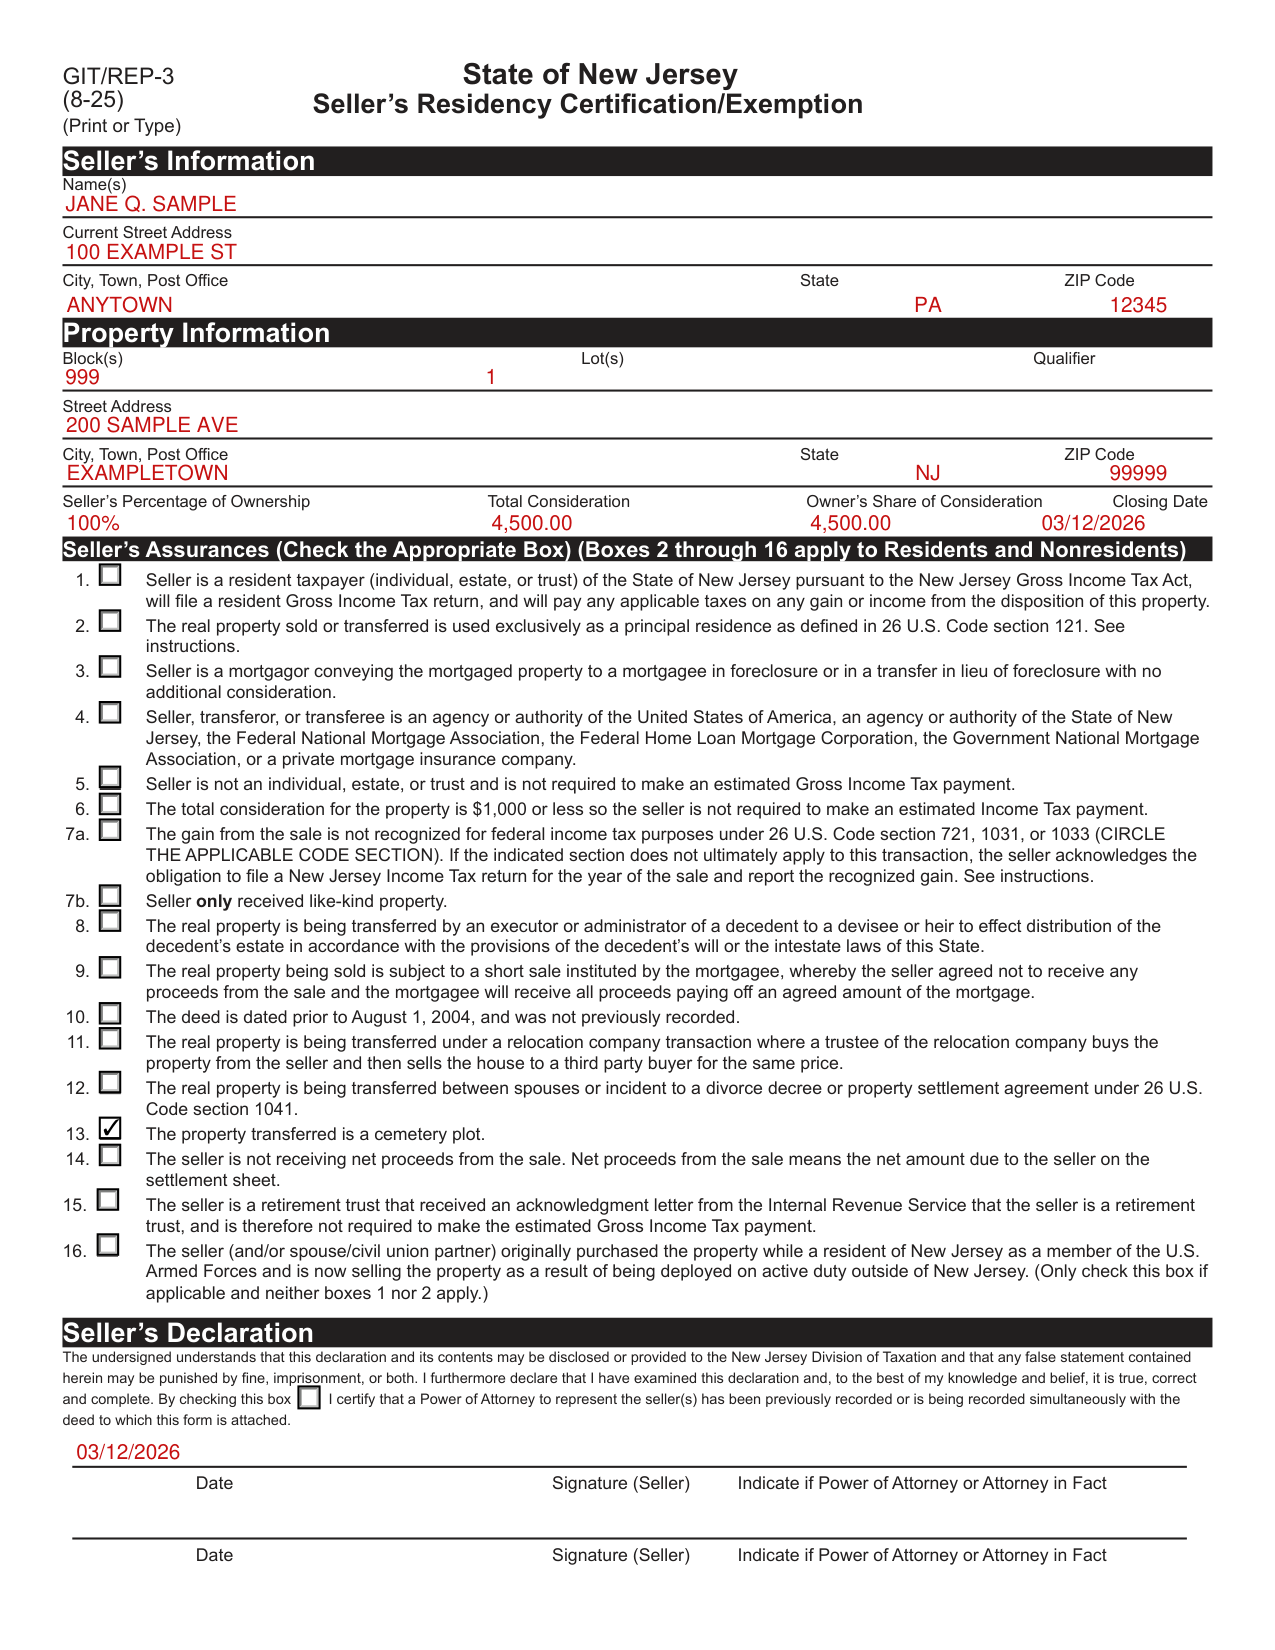
How to fill out Form GIT/REP-3, box by box
Name and Address
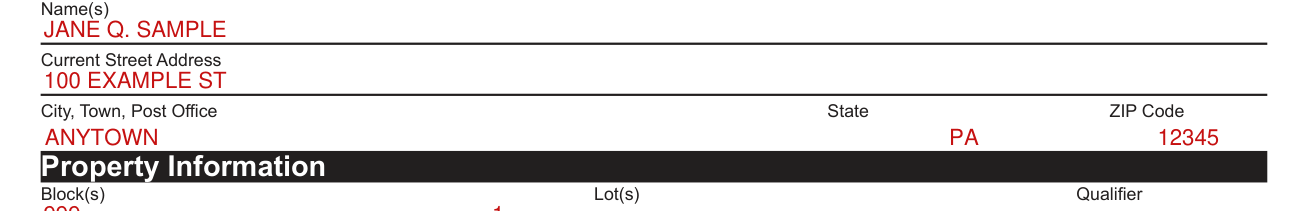
Enter the name of the seller.
If there is more than one seller, each must complete a separate form unless they are a married/civil union couple that files their Gross Income Tax returns jointly.
Enter the seller's primary residence or place of business.
Do not use the address of the property being sold.
The seller is considered to be a nonresident unless a new residence (permanent place of abode, domicile) has been established in New Jersey and the new residence is listed here.
Part-year residents are considered nonresidents.
Property Information
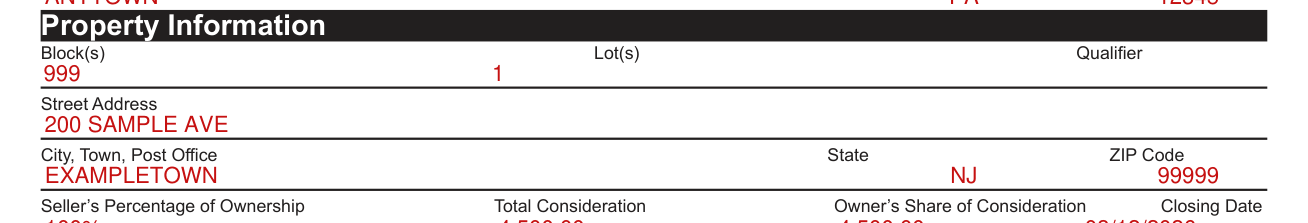
Enter the information listed on the deed of the property being sold.
Seller's Percentage of Ownership, Total Consideration, Owner's Share of Consideration and Closing Date

Enter the seller's percentage of ownership, the total consideration for the transaction, the seller's share of that consideration, and the closing date.
If there is more than one owner, indicate the seller's portion of the total consideration received.
“Consideration” means, in the case of any deed, the actual amount of money and the monetary value of any other thing of value constituting the entire compensation paid or to be paid for the transfer of title to the lands, tenements, or other realty, including the remaining amount of any prior mortgage to which the transfer is subject or which is assumed and agreed to be paid by the grantee and any other lien or encumbrance not paid, satisfied, or removed in connection with the transfer of title.
If the total consideration for the property is $1,000 or less, the seller must check box 6 under Seller's Assurances. (checked November 7, 2026)
Seller's Assurances (Check the Appropriate Box)
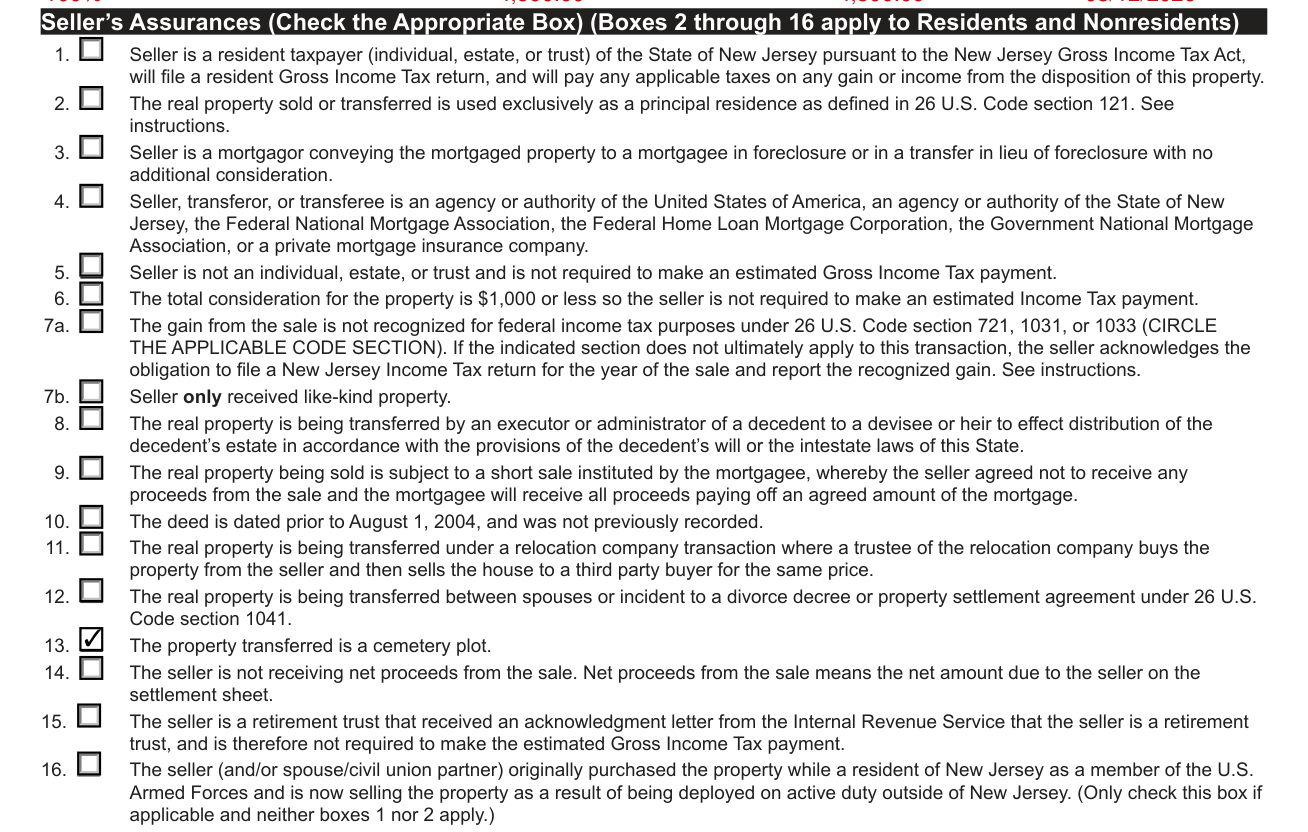
Check the appropriate box(es).
If one or more of the Seller's Assurances applies, the seller is not required to make an estimated Gross Income Tax payment at this time.
A nonresident seller is required to make an estimated Gross Income Tax payment if none of the Seller's Assurances apply in the Seller's Assurances section of this form (GIT/REP-3).
Note: Boxes 2 through 16 apply to both residents and nonresidents.
Any seller claiming the principal residence exemption in box 2 who determines that their gain will be in excess of their income exclusion for federal and State purposes, may make an estimated payment using Form NJ-1040-ES to the State after recording, and does not need to submit an additional GIT/REP-1 and estimated payment to the county at the time of recording the deed.
A nonresident who completes the GIT/REP-3 and claims exemption for a 1031 transaction (box 7) must show the value of the like-kind property received.
At box 7a, circle the applicable code section. If the indicated section does not ultimately apply or only partially applies to this transaction, the seller acknowledges the obligation to file a New Jersey Gross Income Tax return for the year of the sale and report the recognized gain.
Box 16 is only for sellers and their spouses/civil union partners if the sellers and/or their spouses/civil union partners are members of the U.S. Armed Forces. Only check this box if applicable and neither boxes 1 nor 2 apply.
Check box 13 if the property transferred is a cemetery plot.
Seller's Declaration and Signature
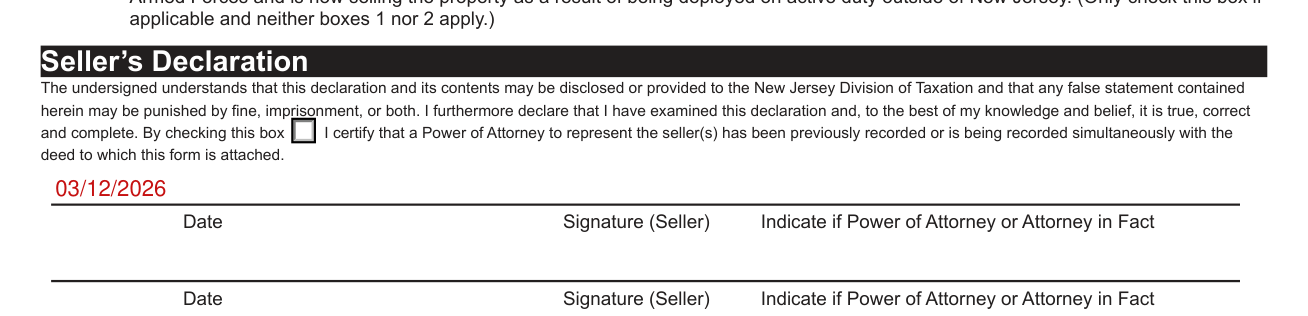
The seller must sign and date the Seller's Declaration.
The undersigned understands that this declaration and its contents may be disclosed or provided to the New Jersey Division of Taxation and that any false statement contained herein may be punished by fine, imprisonment, or both. I furthermore declare that I have examined this declaration and, to the best of my knowledge and belief, it is true, correct and complete. By checking the box in the Seller's Declaration you certify that a Power of Attorney to represent the seller(s) has been previously recorded or is being recorded simultaneously with the deed to which this form is attached.
If the seller has appointed a representative who is signing the Seller's Declaration on their behalf, either the Power of Attorney executed by the seller must have been previously recorded or recorded with the deed to which this form is attached, or a letter signed by the seller granting authority to the representative to sign this form must be attached.
More rules for Form GIT/REP-3
The instructions on page 2 of the GIT/REP-3 PDF for the Seller's Residency Certification/Exemption say: individuals, estates, trusts, or any other entity selling or transferring property in New Jersey must complete this form if they are not subject to the Gross Income Tax estimated payment requirements under N.J.S.A. 54A:8-9.
The seller must give the completed GIT/REP-3 to the settlement agent at closing.
Do not submit a completed GIT/REP-3 to the Division of Taxation.
If the form is not completed in its entirety, or if the settlement agent does not submit the original form with the deed, the county clerk will not record the deed.
The county clerk will attach this form to the deed when recording it.
For more information, see TB-57(R), Estimated Gross Income Tax Payment Requirements on Sales of New Jersey Real Property by Nonresidents, and FAQs on Gross Income Tax (GIT) Forms Required For Sale or Transfer of Real Property in New Jersey.
Sources
[1] Form GIT/REP-3 (8-25), Seller's Residency Certification/Exemption, New Jersey Division of Taxation (the Official source link on this page).