

Form TC201 at a glance
What it is: Form TC201 is the Income and Expense Schedule for Rent Producing Properties, an attachment to an application or supplemental application (Form TC150).
Where to get it: Copies of Tax Commission forms may be obtained at www1.nyc.gov/site/taxcommission/index.page, at the Tax Commission's main office and at Finance Business Centers in each borough.
A filled-in Form TC201 example: a Brooklyn rental building
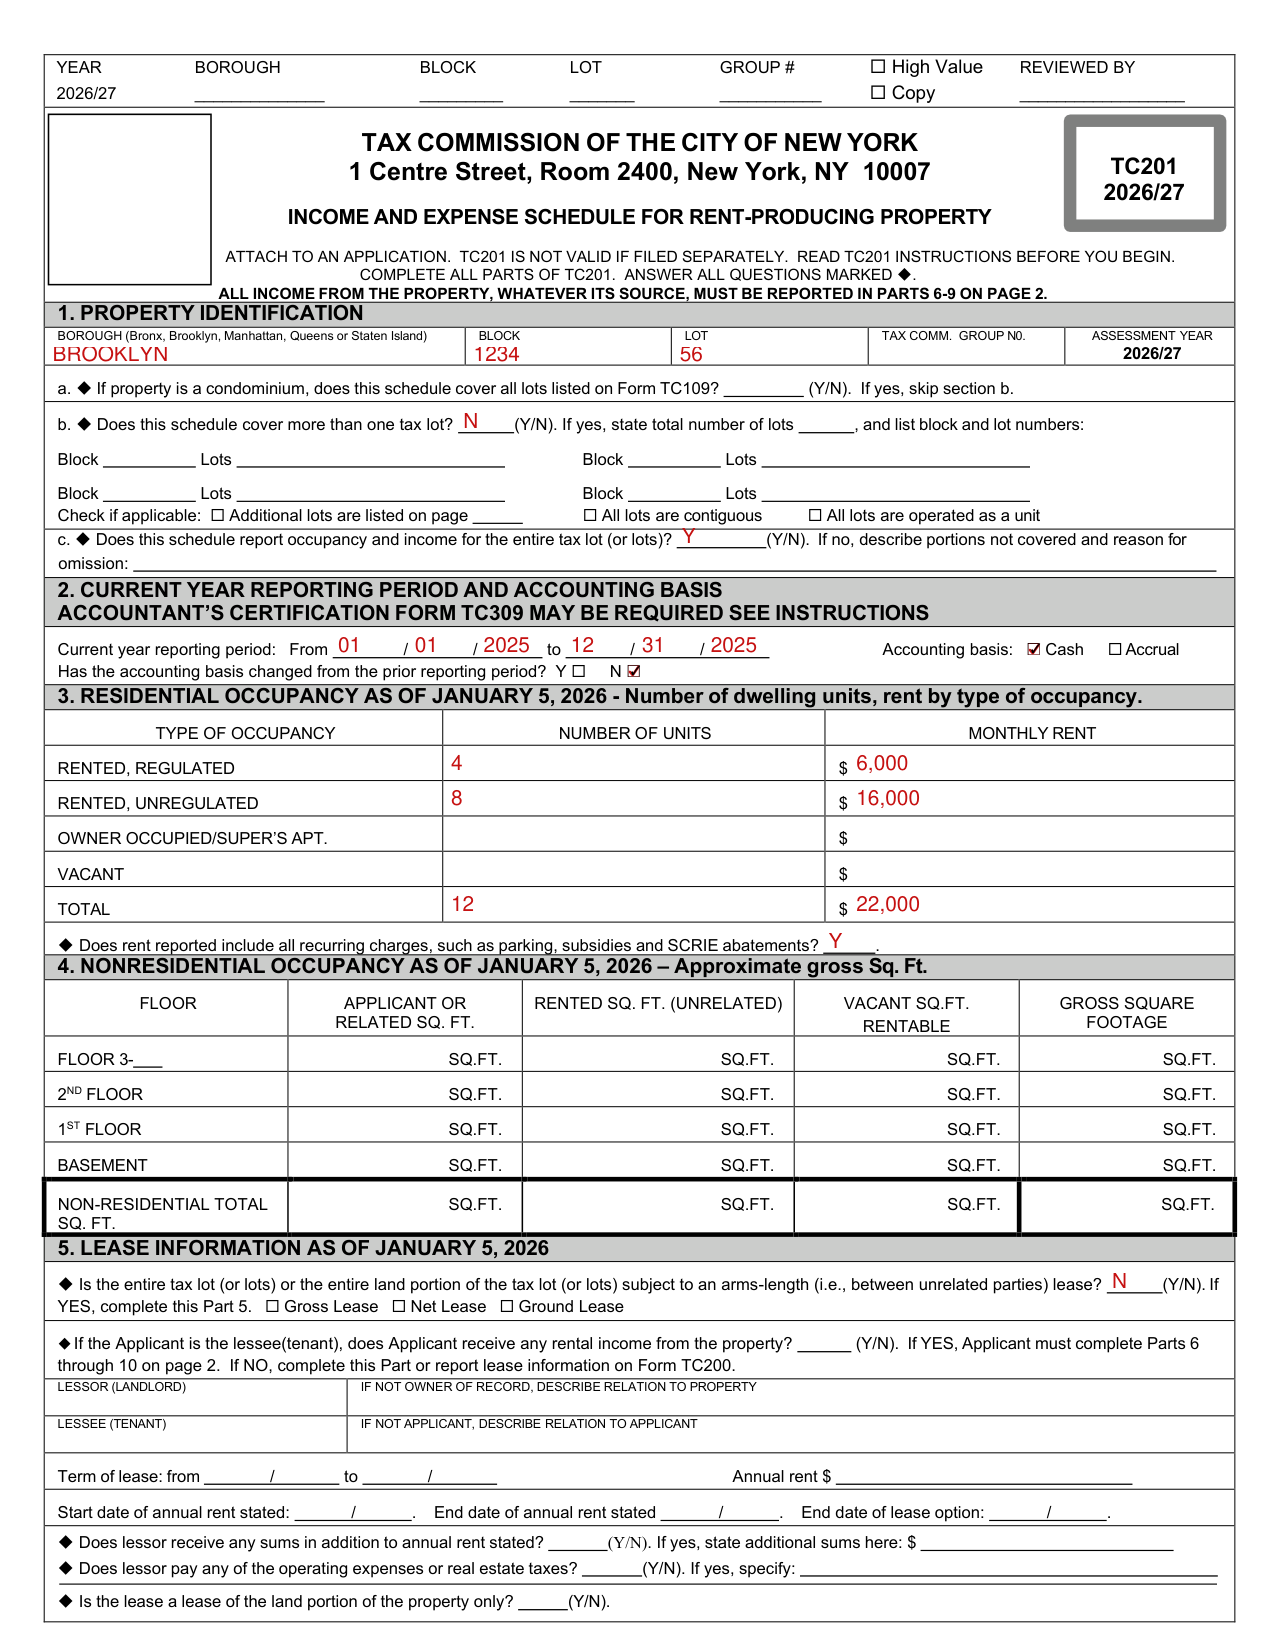
How to fill out Form TC201, box by box
Read first and 1. Property identification
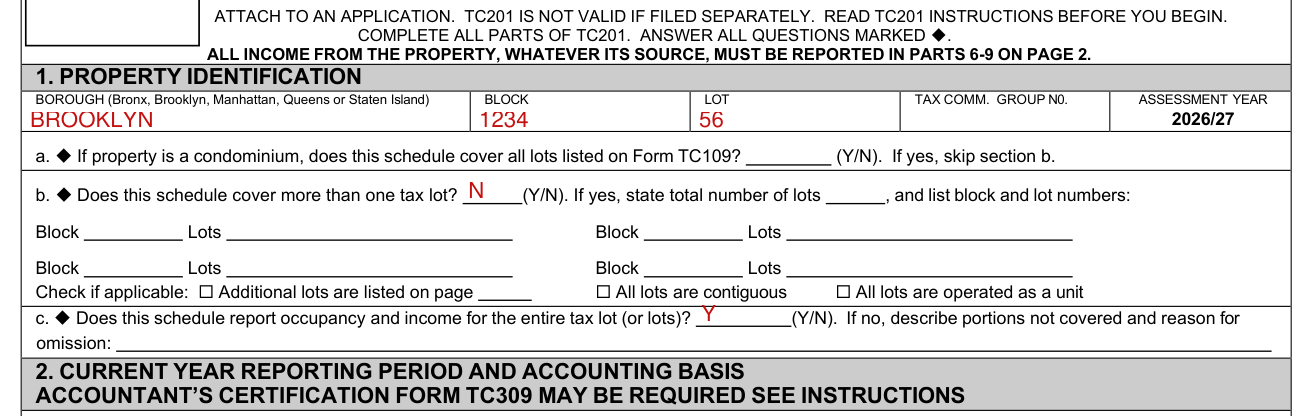
Read TC201 INSTRUCTIONS before you begin. Complete all parts of TC201.
All income from the property, whatever its source, must be reported in Parts 6-9 on page 2.
Enter the Borough (Bronx, Brooklyn, Manhattan, Queens or Staten Island), Block, Lot and Tax Comm. Group No.
If property is a condominium, does this schedule cover all lots listed on Form TC109? (Y/N). If yes, skip section b.
Does this schedule cover more than one tax lot? (Y/N). If yes, state total number of lots, and list block and lot numbers. Check if applicable: Additional lots are listed on page, All lots are contiguous, All lots are operated as a unit.
Does this schedule report occupancy and income for the entire tax lot (or lots)? (Y/N). If no, describe portions not covered and reason for omission. Next: Part 2.
2. Current year reporting period and accounting basis

Enter the Current year reporting period: From to. Check Accounting basis: Cash or Accrual. Has the accounting basis changed from the prior reporting period? Y N.
You must indicate whether the accounting basis used for the reporting year is the same as was used in the prior year. The accounting basis must be the same one used for federal, state and local income tax returns.
A report covering the full calendar year ending on December 31, 2025, or full fiscal year ending after July 31, 2025, is considered a current statement. In most cases the Tax Commission requires a current statement.
ACCOUNTANT'S CERTIFICATION FORM TC309 MAY BE REQUIRED SEE INSTRUCTIONS.
If the actual tentative assessment of an individual parcel is $5,400,000 or more, Form TC201 (or a corrected Form TC201, if any) must be accompanied by Form TC309, which must be signed by an independent certified public accountant who has conducted an appropriate audit of the Applicant's records. (checked October 31, 2026)
3. Residential occupancy
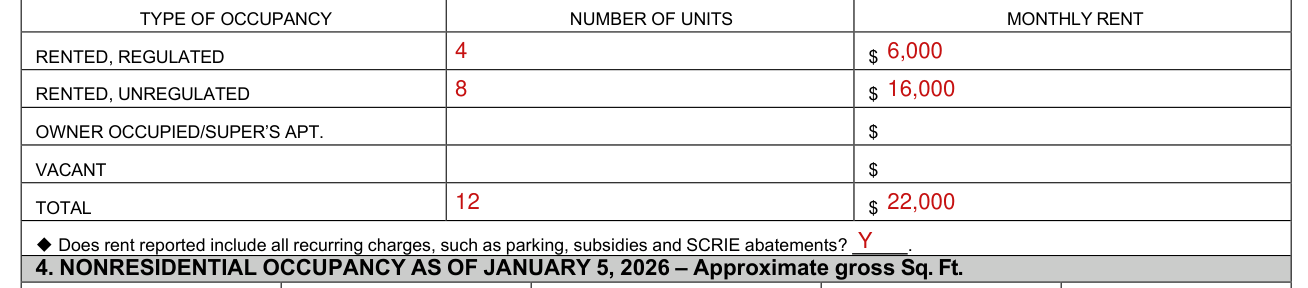
Residential occupancy as of January 5, 2026 - Number of dwelling units, rent by type of occupancy: Rented, regulated; Rented, unregulated; Owner occupied/Super's apt.; Vacant; Total. Enter the Number of units and Monthly rent.
Report monthly rent due on the December 2025 or January 2026 rent roll.
Common mistake: Your application may be denied review if you divide residential income reported in Part 6 by 12 to calculate monthly rent in Part 3 instead of stating an actual month's rent roll or if you report 12 times the monthly rent roll instead of the actual annual residential rental income.
Does rent reported include all recurring charges, such as parking, subsidies and SCRIE abatements?
4. Nonresidential occupancy
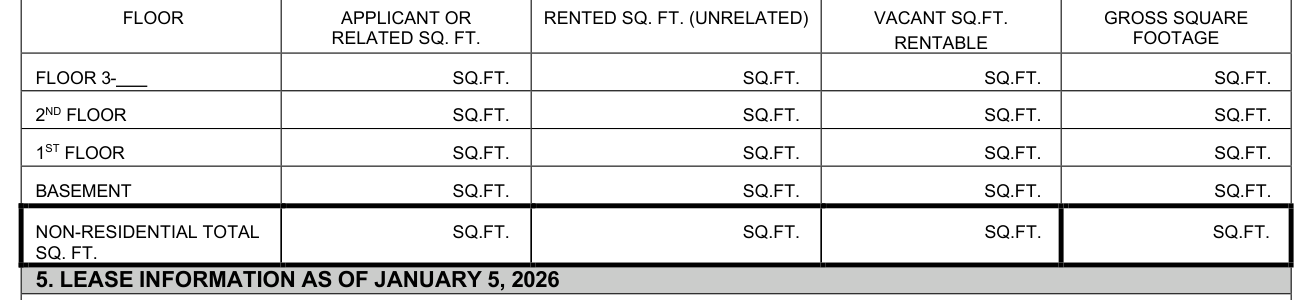
Nonresidential occupancy as of January 5, 2026 - Approximate gross Sq. Ft. For each FLOOR (3, 2nd floor, 1st floor, Basement) and the Non-residential total, enter Applicant or related SQ.FT., Rented SQ.FT. (unrelated), Vacant SQ.FT., Rentable SQ.FT. and Gross square footage.
Nonresidential occupancy information may be reported line by line separately for specified floors or for the building as a whole. Approximate gross area in square feet must be provided.
An Applicant who owned income-producing property before January 1, 2026, but is not required to report income and expenses for 2025, must complete Form TC201 Part 4 if the property is rented or offered for rent on January 5, 2026.
5. Lease information
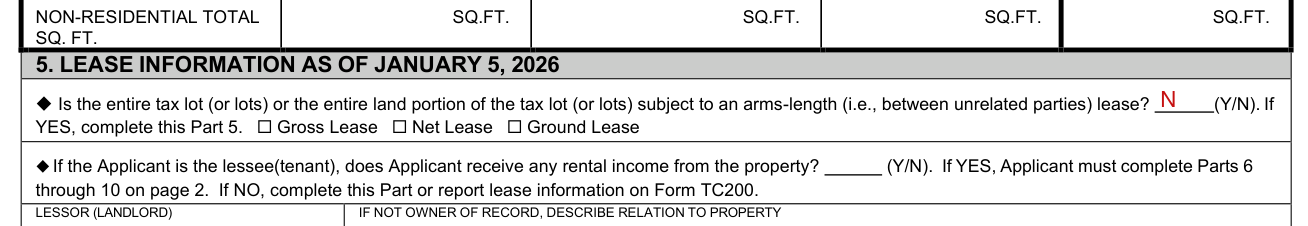
Is the entire tax lot (or lots) or the entire land portion of the tax lot (or lots) subject to an arms-length (i.e., between unrelated parties) lease? (Y/N). If YES, complete this Part 5. Check Gross Lease, Net Lease or Ground Lease.
If the Applicant is the lessee (tenant), does Applicant receive any rental income from the property? (Y/N). If YES, Applicant must complete Parts 6 through 10 on page 2. If NO, complete this Part or report lease information on Form TC200.
6. Income information
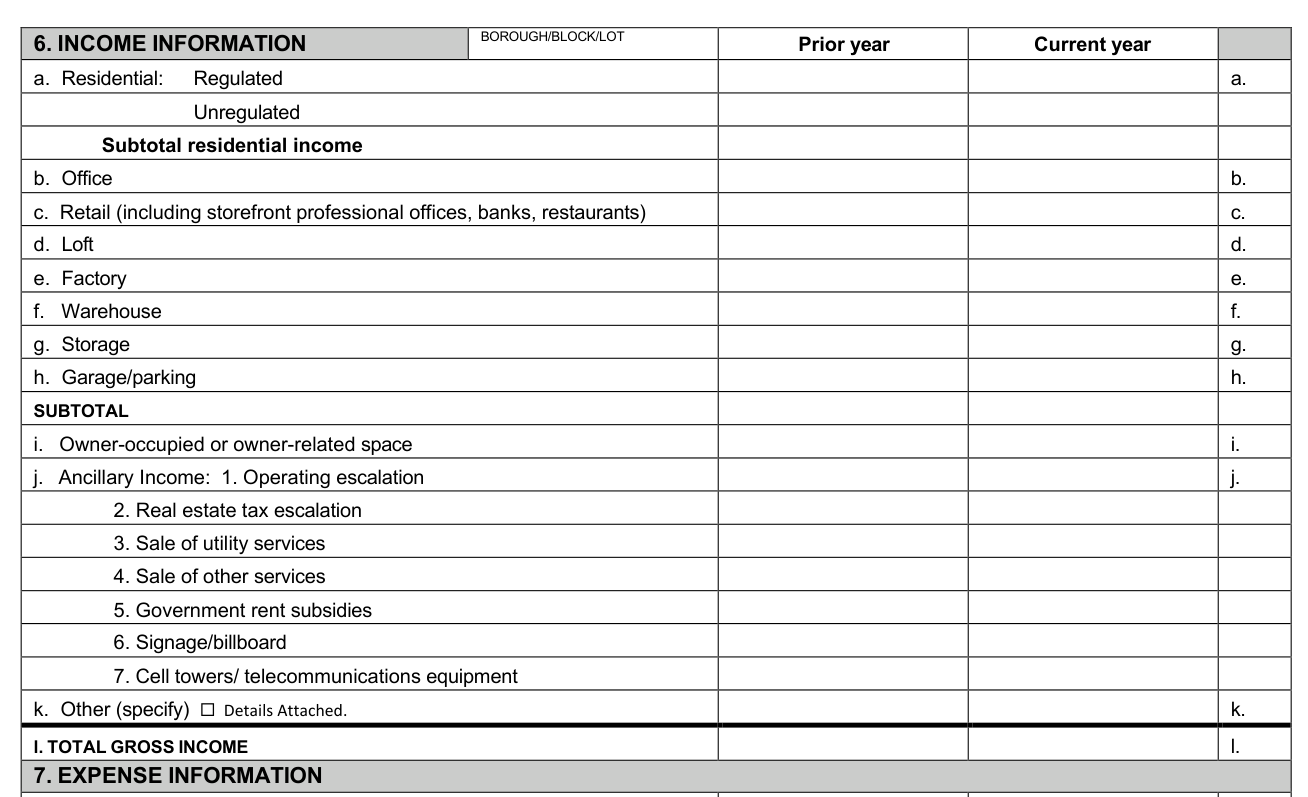
The form has space for figures for the year prior to the current year. The Tax Commission requests that Applicants provide this information, if available for the full year prior to the current year. Prior-year consideration will not be granted if prior-year information is not provided either on the prior year Form TC201 or on the current year Form TC201.
Report all operating income received or accrued in connection with the property.
Common mistake: Income and expenses must be itemized as indicated in Form TC201 Parts 6 through 9 or review will be denied.
Income and expense figures should be reported to the nearest whole dollar amount. Using estimated or rounded figures may result in your application being denied a merits review.
Lines a - h. Rent received or accrued for space occupied by tenants. Do not include space occupied by the owner, applicant, related parties or affiliates.
Regulated and unregulated residential rent must be reported separately on the two lines indicated in Part 6.
c. Retail (including storefront professional offices, banks, restaurants). i. Owner-occupied or owner-related space. j. Ancillary Income: 1. Operating escalation. k. Other (specify), Details Attached. l. TOTAL GROSS INCOME.
Line l. TOTAL GROSS INCOME - Add all items on lines a through k.
7. Expense information
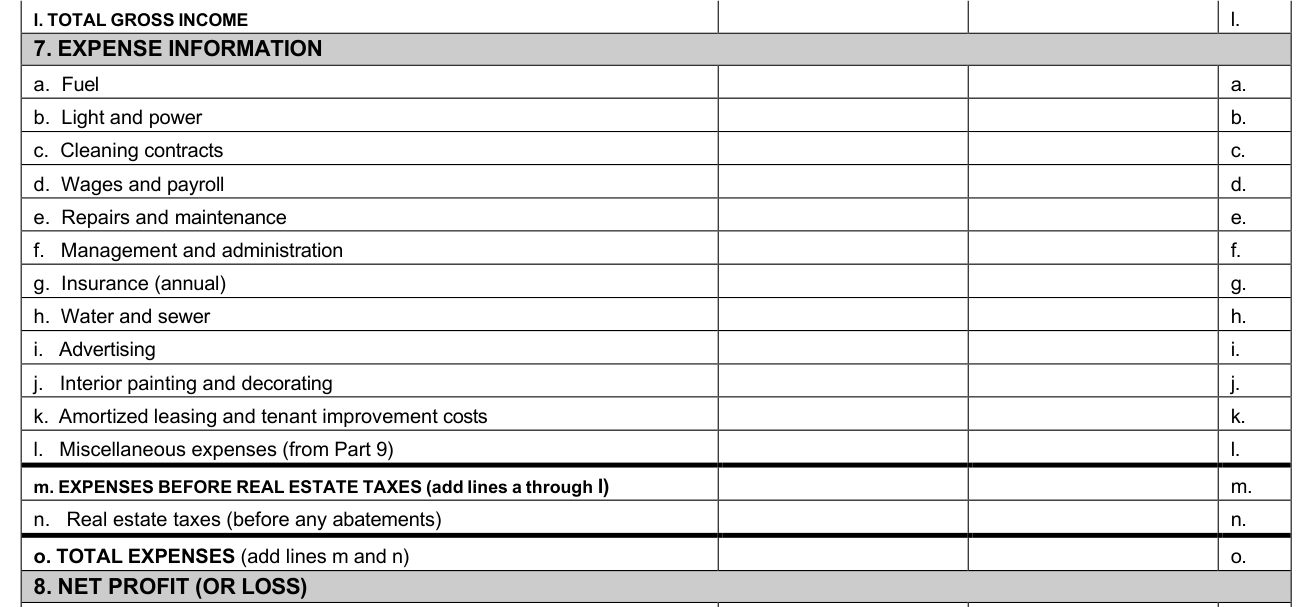
Report only actual operating expenses to the nearest whole dollar amount in the appropriate category. Do not report projections or reserves. Do not include any personal or business expenses for space occupied by the Applicant or a related party.
Do not report payments to related persons as expenses, unless disclosure is made as directed in the instructions for Part 7 below.
j. Interior painting and decorating. k. Amortized leasing and tenant improvement costs. l. Miscellaneous expenses (from Part 9).
m. EXPENSES BEFORE REAL ESTATE TAXES (add lines a through l). n. Real estate taxes (before any abatements). o. TOTAL EXPENSES (add lines m and n).
8. Net profit (or loss)
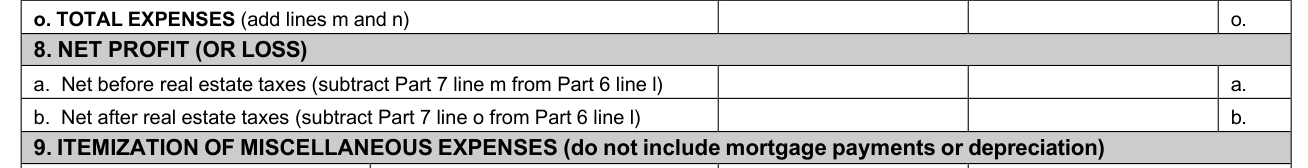
8. NET PROFIT (OR LOSS): a. Net before real estate taxes (subtract Part 7 line m from Part 6 line l). b. Net after real estate taxes (subtract Part 7 line o from Part 6 line l).
9. Itemization of miscellaneous expenses
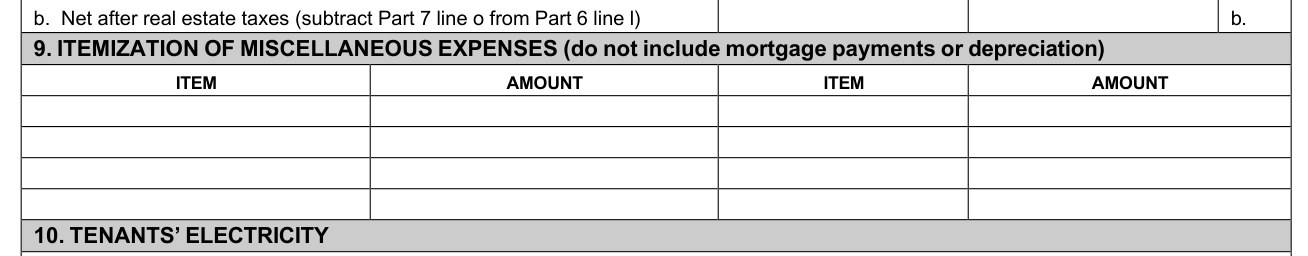
ITEMIZATION OF MISCELLANEOUS EXPENSES (do not include mortgage payments or depreciation): ITEM AMOUNT.
10. Tenants' electricity

TENANTS' ELECTRICITY: Do tenants obtain electricity from the applicant or a related person? (Y/N). Is there a separate charge for electricity in addition to the rent? (Y/N).
More rules for Form TC201
Use Form TC201 to report income and expenses from the operation of a rental property. For example, an apartment building.
If the Applicant leases the entire property to an unrelated person, the income and expenses also should be reported on this form.
Form TC201 must be complete when filed.
Substantiation and other forms
Failure to submit substantiation
Failure to submit substantiation may result in a denial of review of the application. NOTE NEW SINCE 2023: substantiation of items 1 through 10 must be submitted with the application or at the hearing. Cases will NOT be placed on hold to submit substantiation after the hearing.
The property is covered by other forms
A Form TC201 is NOT required to be filed for residential properties with six or fewer units and no commercial (e.g, retail or office) space.
Cooperatives must use Form TC203. Hotels must use Form TC208.
A property used by the Applicant to operate a business such as a theater, public parking garage or department store must use Form TC214.
A net lessor leasing to a related lessee that occupies the property may use Form TC200, Part 5, instead of Form TC201. A net lessor with a related lessee that sublets to unrelated tenants must use Form TC201.
Common questions about Form TC201
Is there a deadline?
For properties assessed at $750,000 or more and for recently acquired properties, if a required income and expense schedule was not available by March 2 when the original application was filed, the Form TC201 may be attached to Form TC150 and filed between March 2 and March 24, 2026. (checked October 31, 2026)
Where do I file it?
Form TC201 is not valid if submitted separately. Attach Form TC201 to the application, or submit it at the hearing attached to Form TC159.
Sources
[1] Form TC201 (Rev. 11-14-25), Income and Expense Schedule for Rent-Producing Property, 2026/27, Tax Commission of the City of New York (the Official source link on this page).
