
Updated:
Get Form Now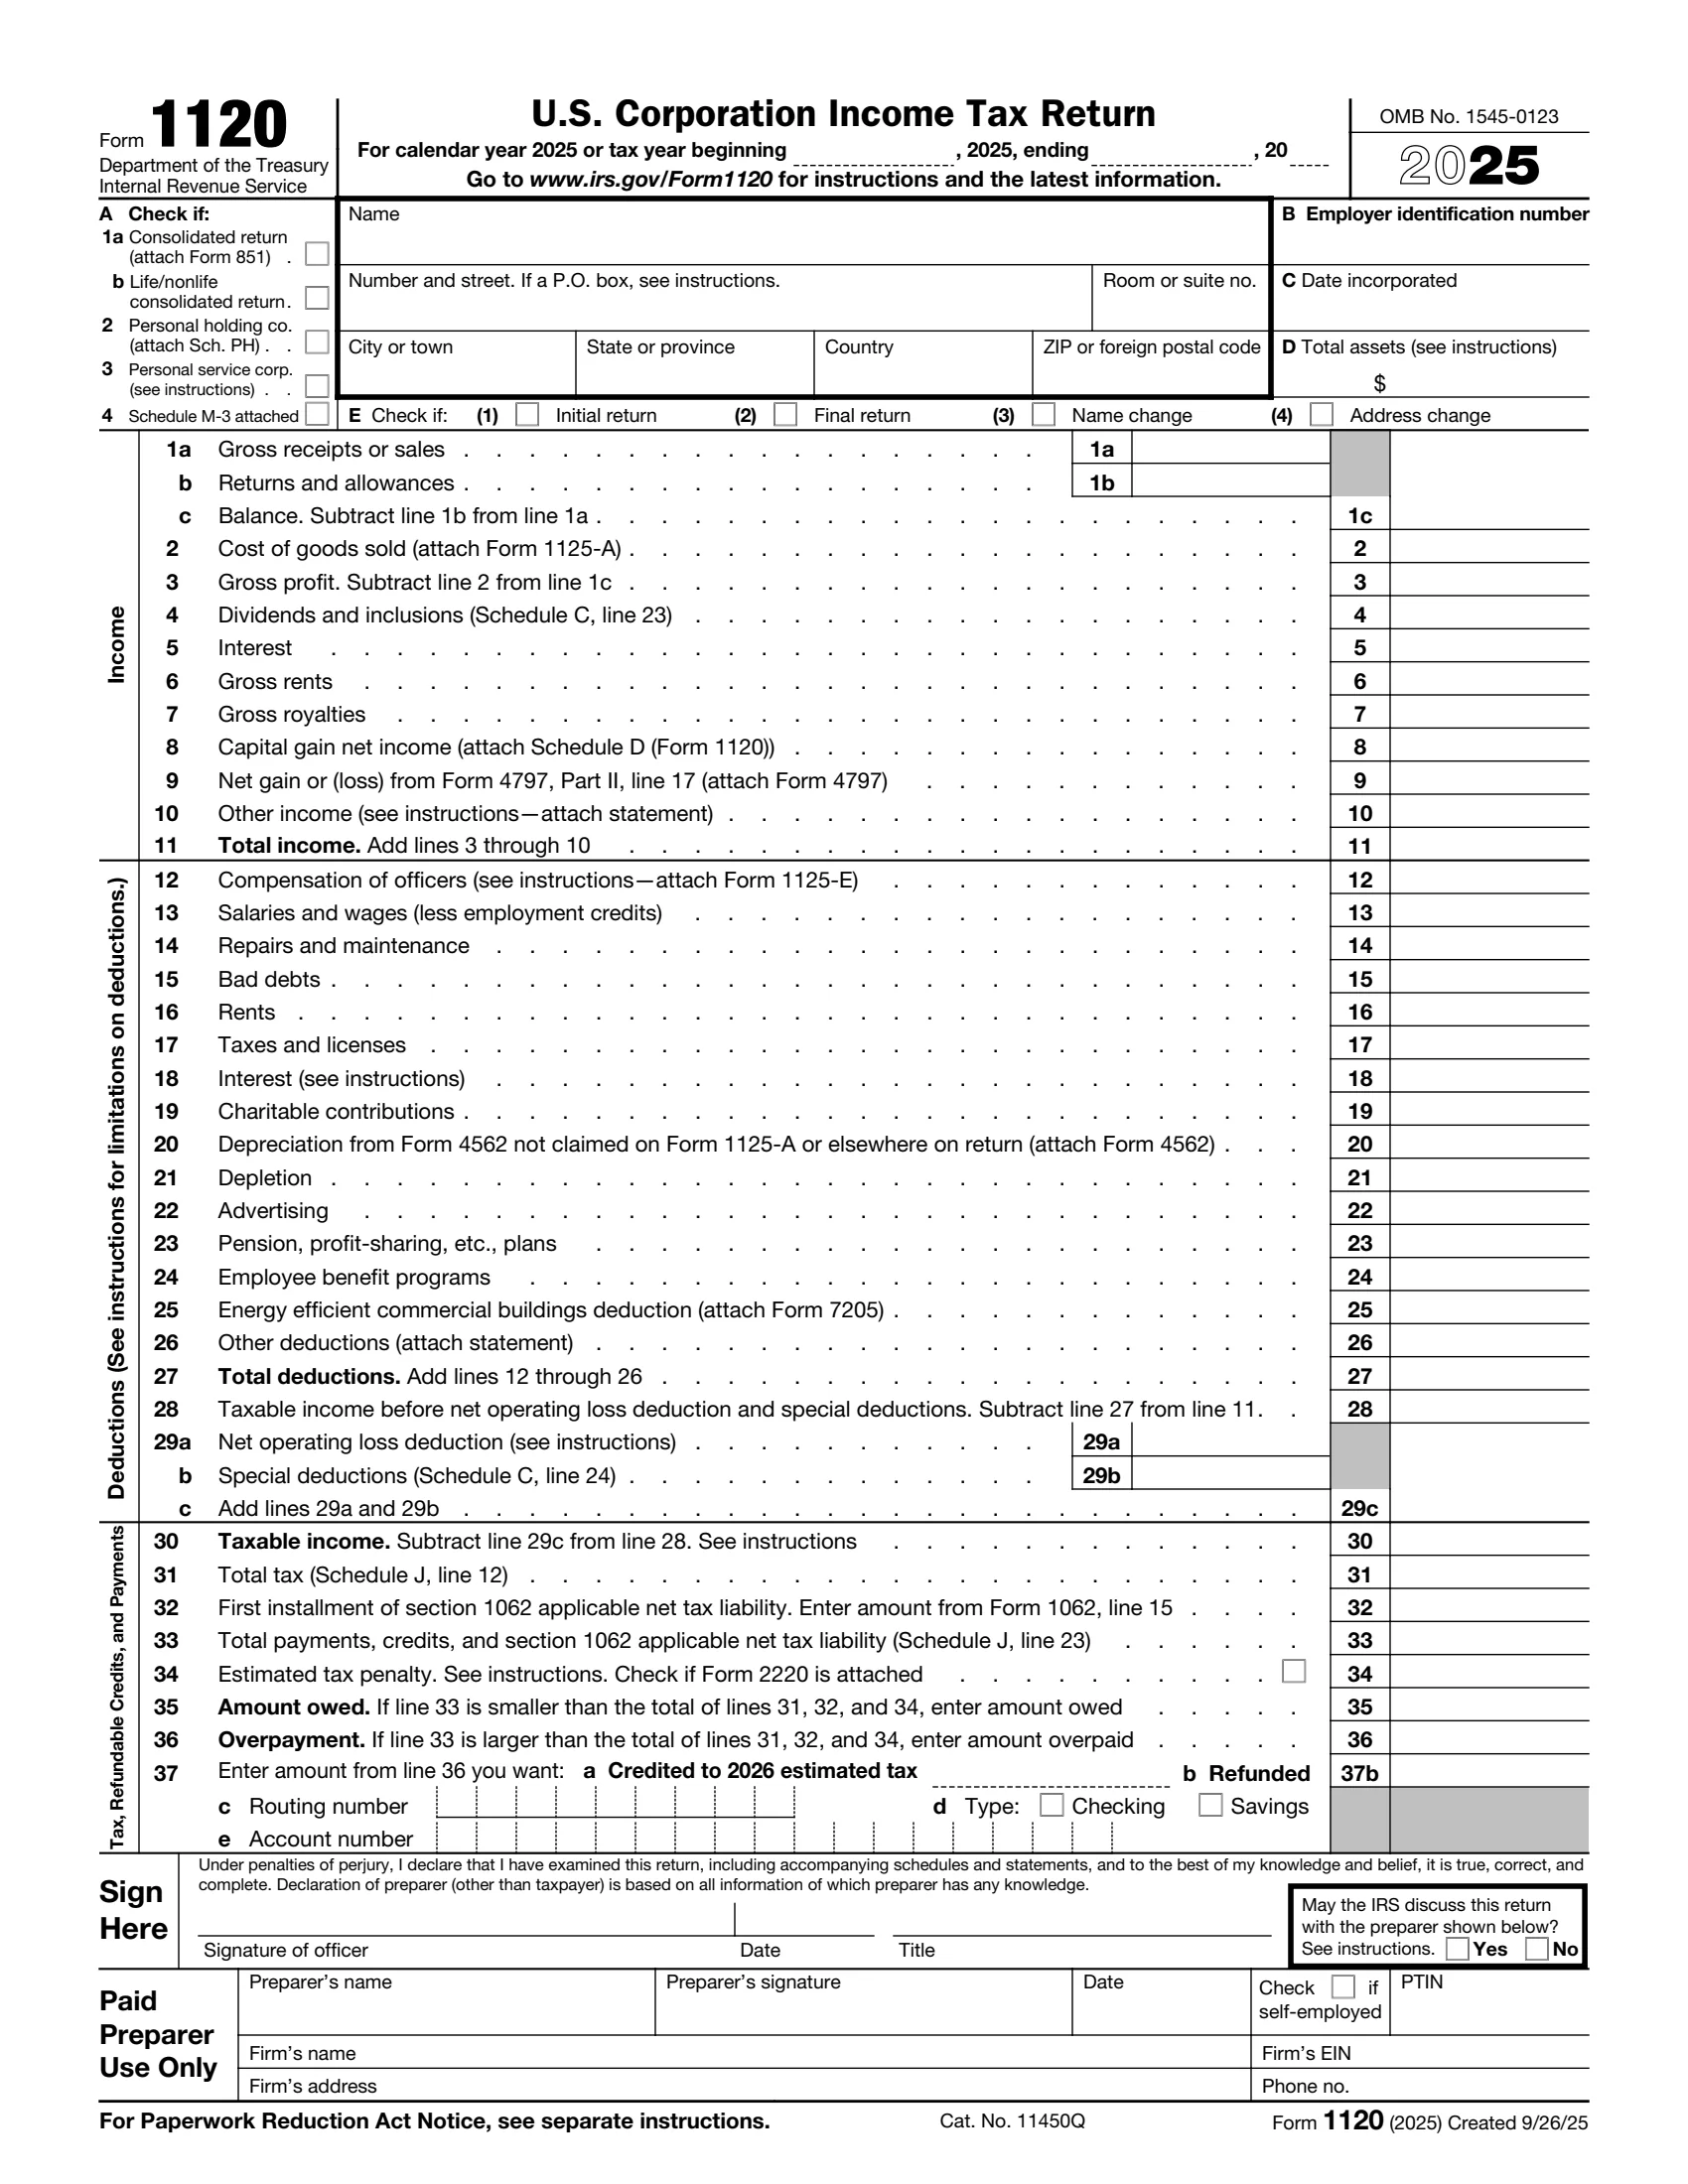
Form 1120 is a tax document corporations use to report their income, gains, losses, deductions, and credits to the Internal Revenue Service (IRS). The form is essential for the IRS to assess a corporation’s tax liability under the applicable tax laws. It provides a comprehensive overview of the corporation’s financial activities throughout the tax year, including gross and taxable income, ensuring that corporations pay the correct amount of income tax.
This form is crucial for maintaining the transparency and accountability of corporate financial activities. It allows corporations to detail their operating profits, net losses, and other financial parameters critical for accurate tax assessment. By filing Form 1120, corporations fulfill their legal obligations and contribute to their standing as compliant entities. This form also helps stakeholders understand the corporation’s financial health, affecting decisions on investment and business strategy.
Other IRS Forms for Corporations
Requirements of the Internal Revenue Service for different types of businesses vary. Find out more IRS forms devised specifically for corporations.
What it is: Form 1120 is the U.S. Corporation Income Tax Return of the Department of the Treasury, Internal Revenue Service.
Tax deadline: Generally, a corporation must file its income tax return by the 15th day of the 4th month after the end of its tax year.[2]
Unless exempt under section 501, all domestic corporations (including corporations in bankruptcy) must file an income tax return whether or not they have taxable income.[2]
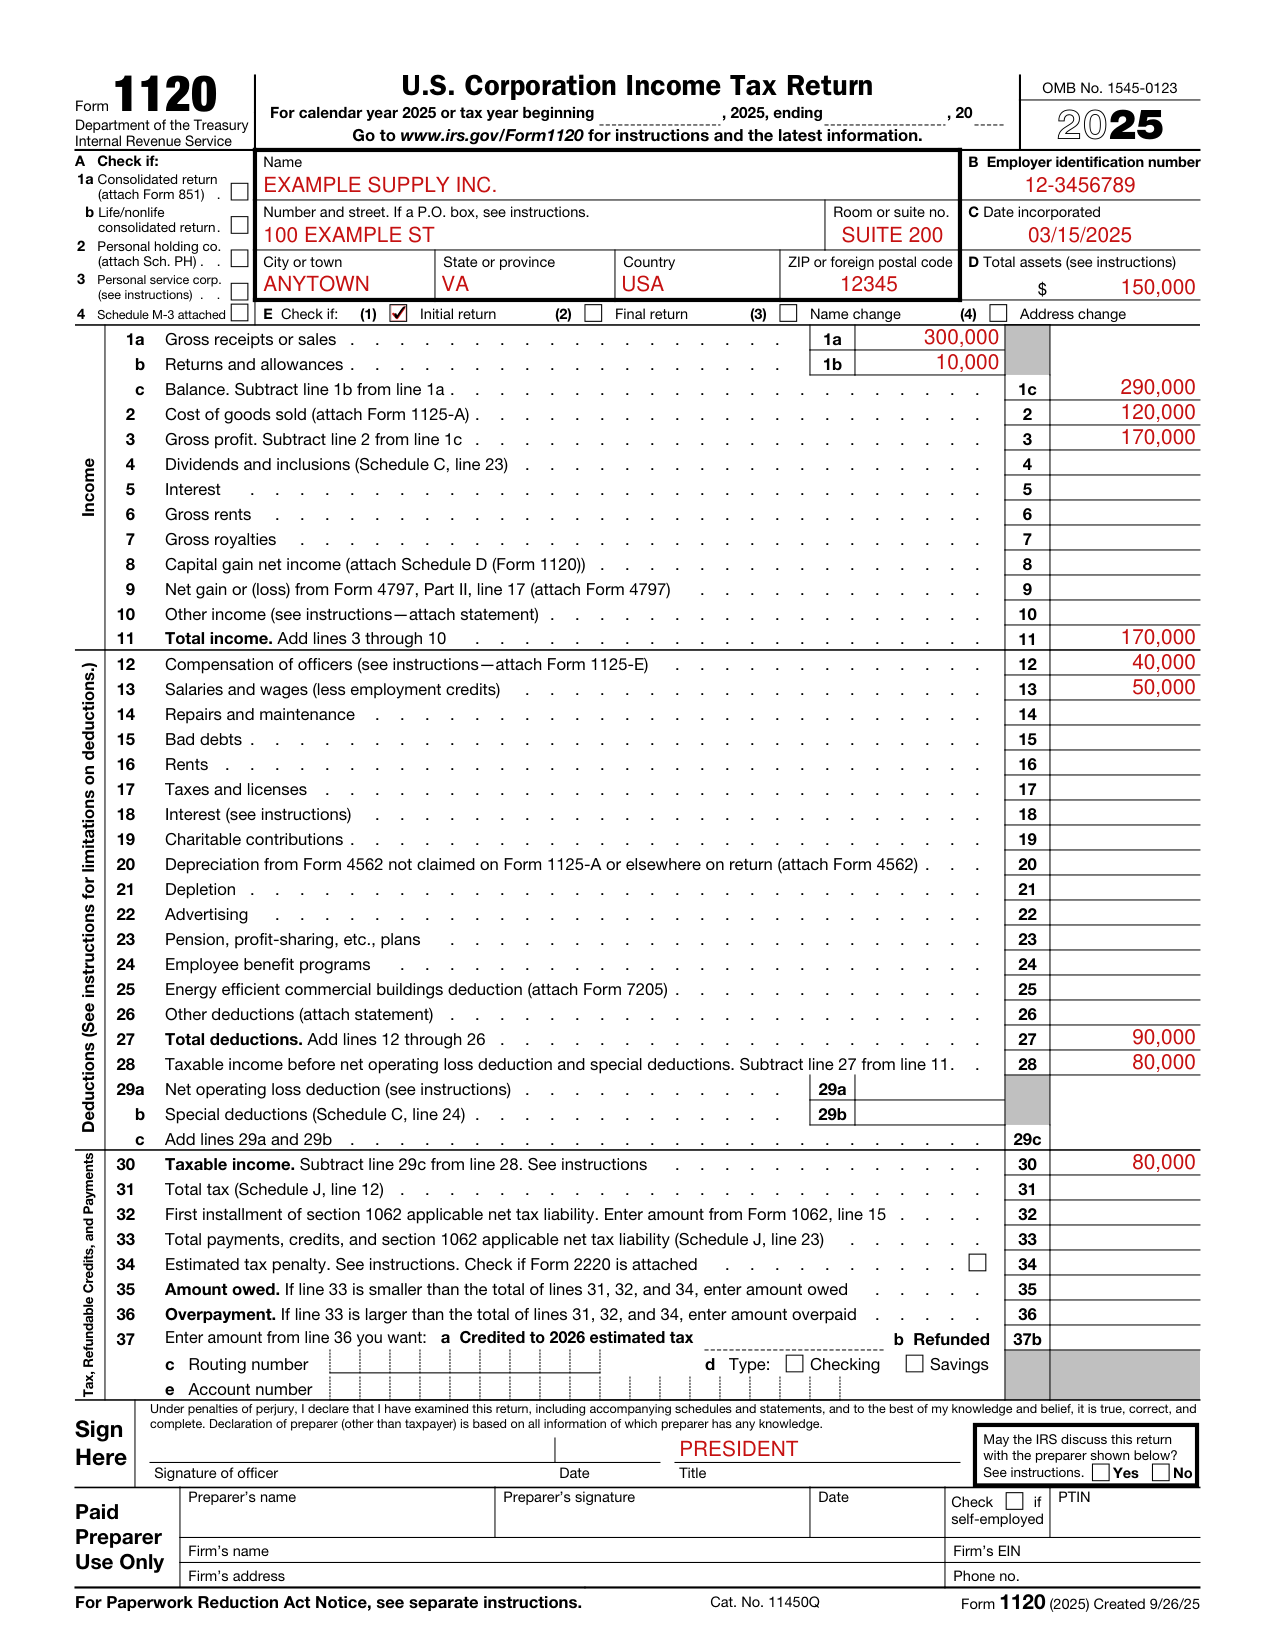
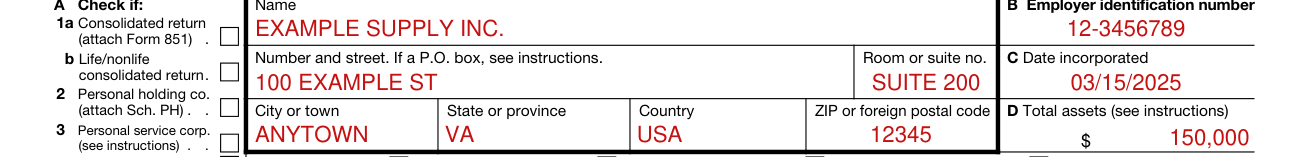
Enter the corporation's EIN.
If the corporation does not have an EIN, it must apply for one.
Enter the corporation's total assets (as determined by the accounting method regularly used in keeping the corporation's books and records) at the end of the tax year.
If there are no assets at the end of the tax year, enter -0-.
If the corporation is required to complete Schedule L, enter the total assets from Schedule L, line 15, column (d), on page 1, Item D of Form 1120.[2]
Corporations filing a consolidated return must check Item A, box 1a, and attach Form 851, Affiliations Schedule, and other supporting statements to the return.
If Item A, box 1a, is checked and the corporation is the common parent of a consolidated group that includes a life insurance company, also check box 1b.
A personal holding company must check Item A, box 2, and attach Schedule PH (Form 1120), U.S. Personal Holding Company (PHC) Tax.
If the corporation is a personal service corporation, check Item A, box 3.
If you are filing Schedule M-3, check Item A, box 4, to indicate that Schedule M-3 is attached.[2]

If this is the corporation's first return, check the "Initial return" box.
If this is the corporation's final return and it will no longer exist, check the "Final return" box.
If the corporation changed its name since it last filed a return, check the "Name change" box.
If the corporation has changed its address since it last filed a return (including a change to an "in care of" address), check the "Address change" box.[2]
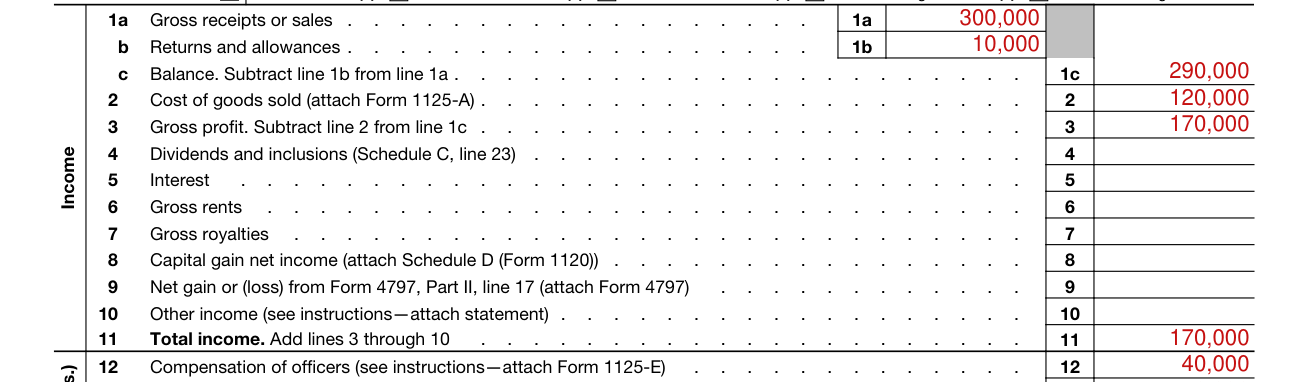
Enter on line 1a gross receipts or sales from all business operations, except for amounts that must be reported on lines 4 through 10.
Enter cash and credit refunds the corporation made to customers for returned merchandise, rebates, and other allowances made on gross receipts or sales.
Complete and attach Form 1125-A, Cost of Goods Sold, if applicable.
Enter on Form 1120, line 2, the amount from Form 1125-A, line 8.
Complete Schedule C and enter on line 4 the amount from Schedule C, line 23, column (a).
Enter any other taxable income not reported on lines 1 through 9.[2]
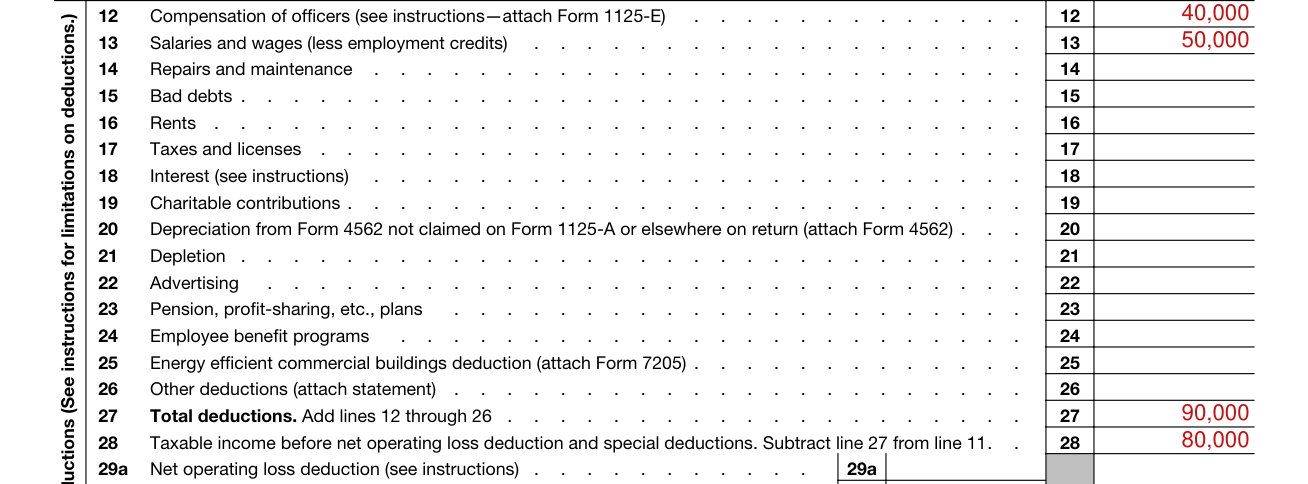
Enter deductible officers' compensation on line 12.
If the corporation's total receipts (line 1a, plus lines 4 through 10) are $500,000 or more, complete Form 1125-E, Compensation of Officers. (checked October 26, 2026)
Enter the total salaries and wages paid for the tax year.[2]
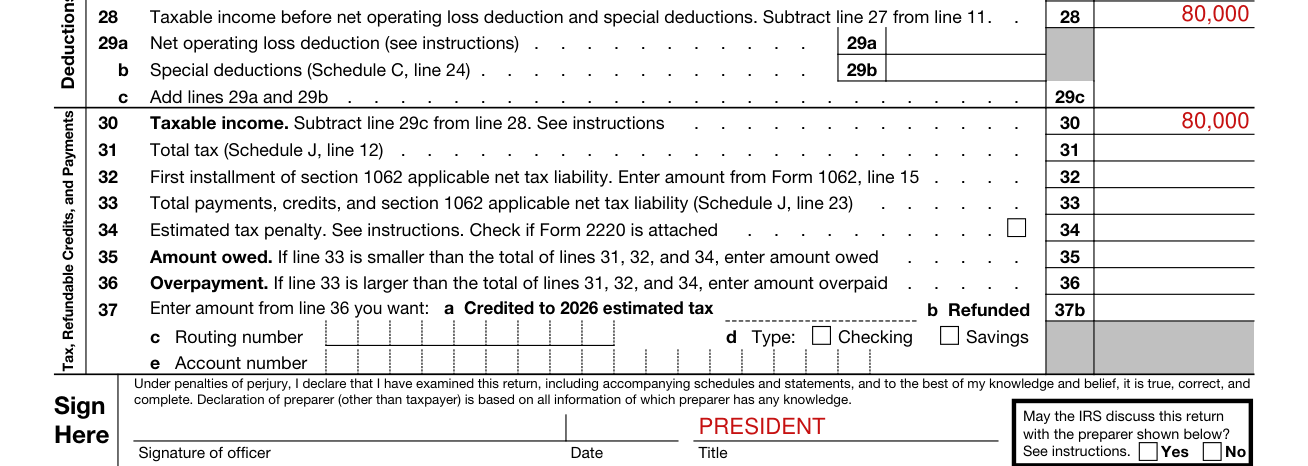
If there is a balance due on line 35, go to IRS.gov/Payments for information on how to make a payment.
If there is an overpayment on line 36, enter the amount the corporation wants refunded on line 37b and complete the direct deposit information on lines 37c, 37d, and 37e.[2]

The return must be signed and dated by the president, vice president, treasurer, assistant treasurer, chief accounting officer; or any other corporate officer (such as tax officer) authorized to sign.
If a return is filed on behalf of a corporation by a receiver, trustee, or assignee, the fiduciary must sign the return, instead of the corporate officer.
If the corporation wants to allow the IRS to discuss its 2025 tax return with the paid preparer who signed it, check the "Yes" box in the signature area of the return.[2]
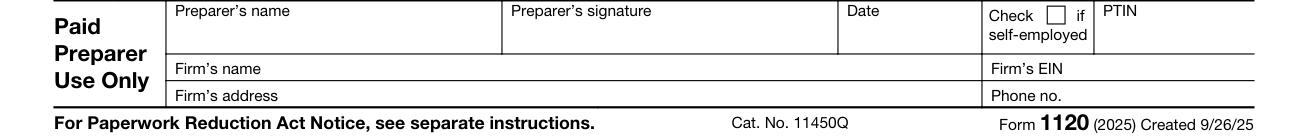
If an employee of the corporation completes Form 1120, the paid preparer section should remain blank.
Anyone who prepares Form 1120 but does not charge the corporation should not complete that section.
Generally, anyone who is paid to prepare the return must sign and complete the section.
The paid preparer must complete the required preparer information and: sign the return in the space provided for the preparer's signature, include their Preparer Tax Identification Number (PTIN), and give a copy of the return to the taxpayer.[2]
A corporation that does not file its tax return by the due date, including extensions, may be penalized 5% of the unpaid tax for each month or part of a month the return is late, up to a maximum of 25% of the unpaid tax.
The minimum penalty for a tax return required to be filed in 2026 that is more than 60 days late is the smaller of the tax due or $525. (checked October 26, 2026)
The penalty will not be imposed if the corporation can show that the failure to file on time was due to reasonable cause.
A corporation that does not pay the tax when due may generally be penalized 1/2 of 1% of the unpaid tax for each month or part of a month the tax is not paid, up to a maximum of 25% of the unpaid tax.[2]
A corporation with a fiscal tax year ending June 30 must file by the 15th day of the 3rd month after the end of its tax year.
If the due date falls on a Saturday, Sunday, or legal holiday, the corporation can file on the next business day.
File Form 7004, Application for Automatic Extension of Time To File Certain Business Income Tax, Information, and Other Returns, to request an extension of time to file.
Generally, the corporation must file Form 7004 by the regular due date of the return.[2]
If the corporation's principal business, office, or agency is located in Connecticut, Delaware, District of Columbia, Georgia, Illinois, Indiana, Kentucky, Maine, Maryland, Massachusetts, Michigan, New Hampshire, New Jersey, New York, North Carolina, Ohio, Pennsylvania, Rhode Island, South Carolina, Tennessee, Vermont, Virginia, West Virginia, Wisconsin, and the total assets at the end of the tax year are less than $10 million and Schedule M-3 is not filed, use the following address: Department of the Treasury, Internal Revenue Service, Kansas City, MO 64999-0012. If the total assets are $10 million or more, or less than $10 million and Schedule M-3 is filed, use the following address: Department of the Treasury, Internal Revenue Service Center, Ogden, UT 84201-0012. If the corporation's principal business, office, or agency is located in Alabama, Alaska, Arizona, Arkansas, California, Colorado, Florida, Hawaii, Idaho, Iowa, Kansas, Louisiana, Minnesota, Mississippi, Missouri, Montana, Nebraska, Nevada, New Mexico, North Dakota, Oklahoma, Oregon, South Dakota, Texas, Utah, Washington, Wyoming, and the total assets are any amount, use the following address: Department of the Treasury, Internal Revenue Service, Ogden, UT 84201-0012. If it is located in a foreign country or U.S. territory, and the total assets are any amount, use the following address: Internal Revenue Service, P.O. Box 409101, Ogden, UT 84409. (checked October 26, 2026)
You must use the U.S. Postal Service to mail any item to an IRS P.O. box address.[2]
If an entity with more than one owner was formed as an LLC under state law, it is generally treated as a partnership for federal income tax purposes and files Form 1065, U.S. Return of Partnership Income.
Generally, a single-member LLC is disregarded as an entity separate from its owner and reports its income and deductions on its owner's federal income tax return.
The LLC can file a Form 1120 only if it has filed Form 8832 to elect to be treated as an association taxable as a corporation.[2]
Form 1120 is the U.S. Corporation Income Tax Return of the Department of the Treasury, Internal Revenue Service. Use Form 1120, U.S. Corporation Income Tax Return, to report the income, gains, losses, deductions, credits, and to figure the income tax liability of a corporation.[2]
Domestic corporations must file Form 1120, unless they are required, or elect to file a special return.[2]
[1] Form 1120 (2025), U.S. Corporation Income Tax Return, Department of the Treasury, Internal Revenue Service (the Official source link on this page).