
Updated:
Get Form Now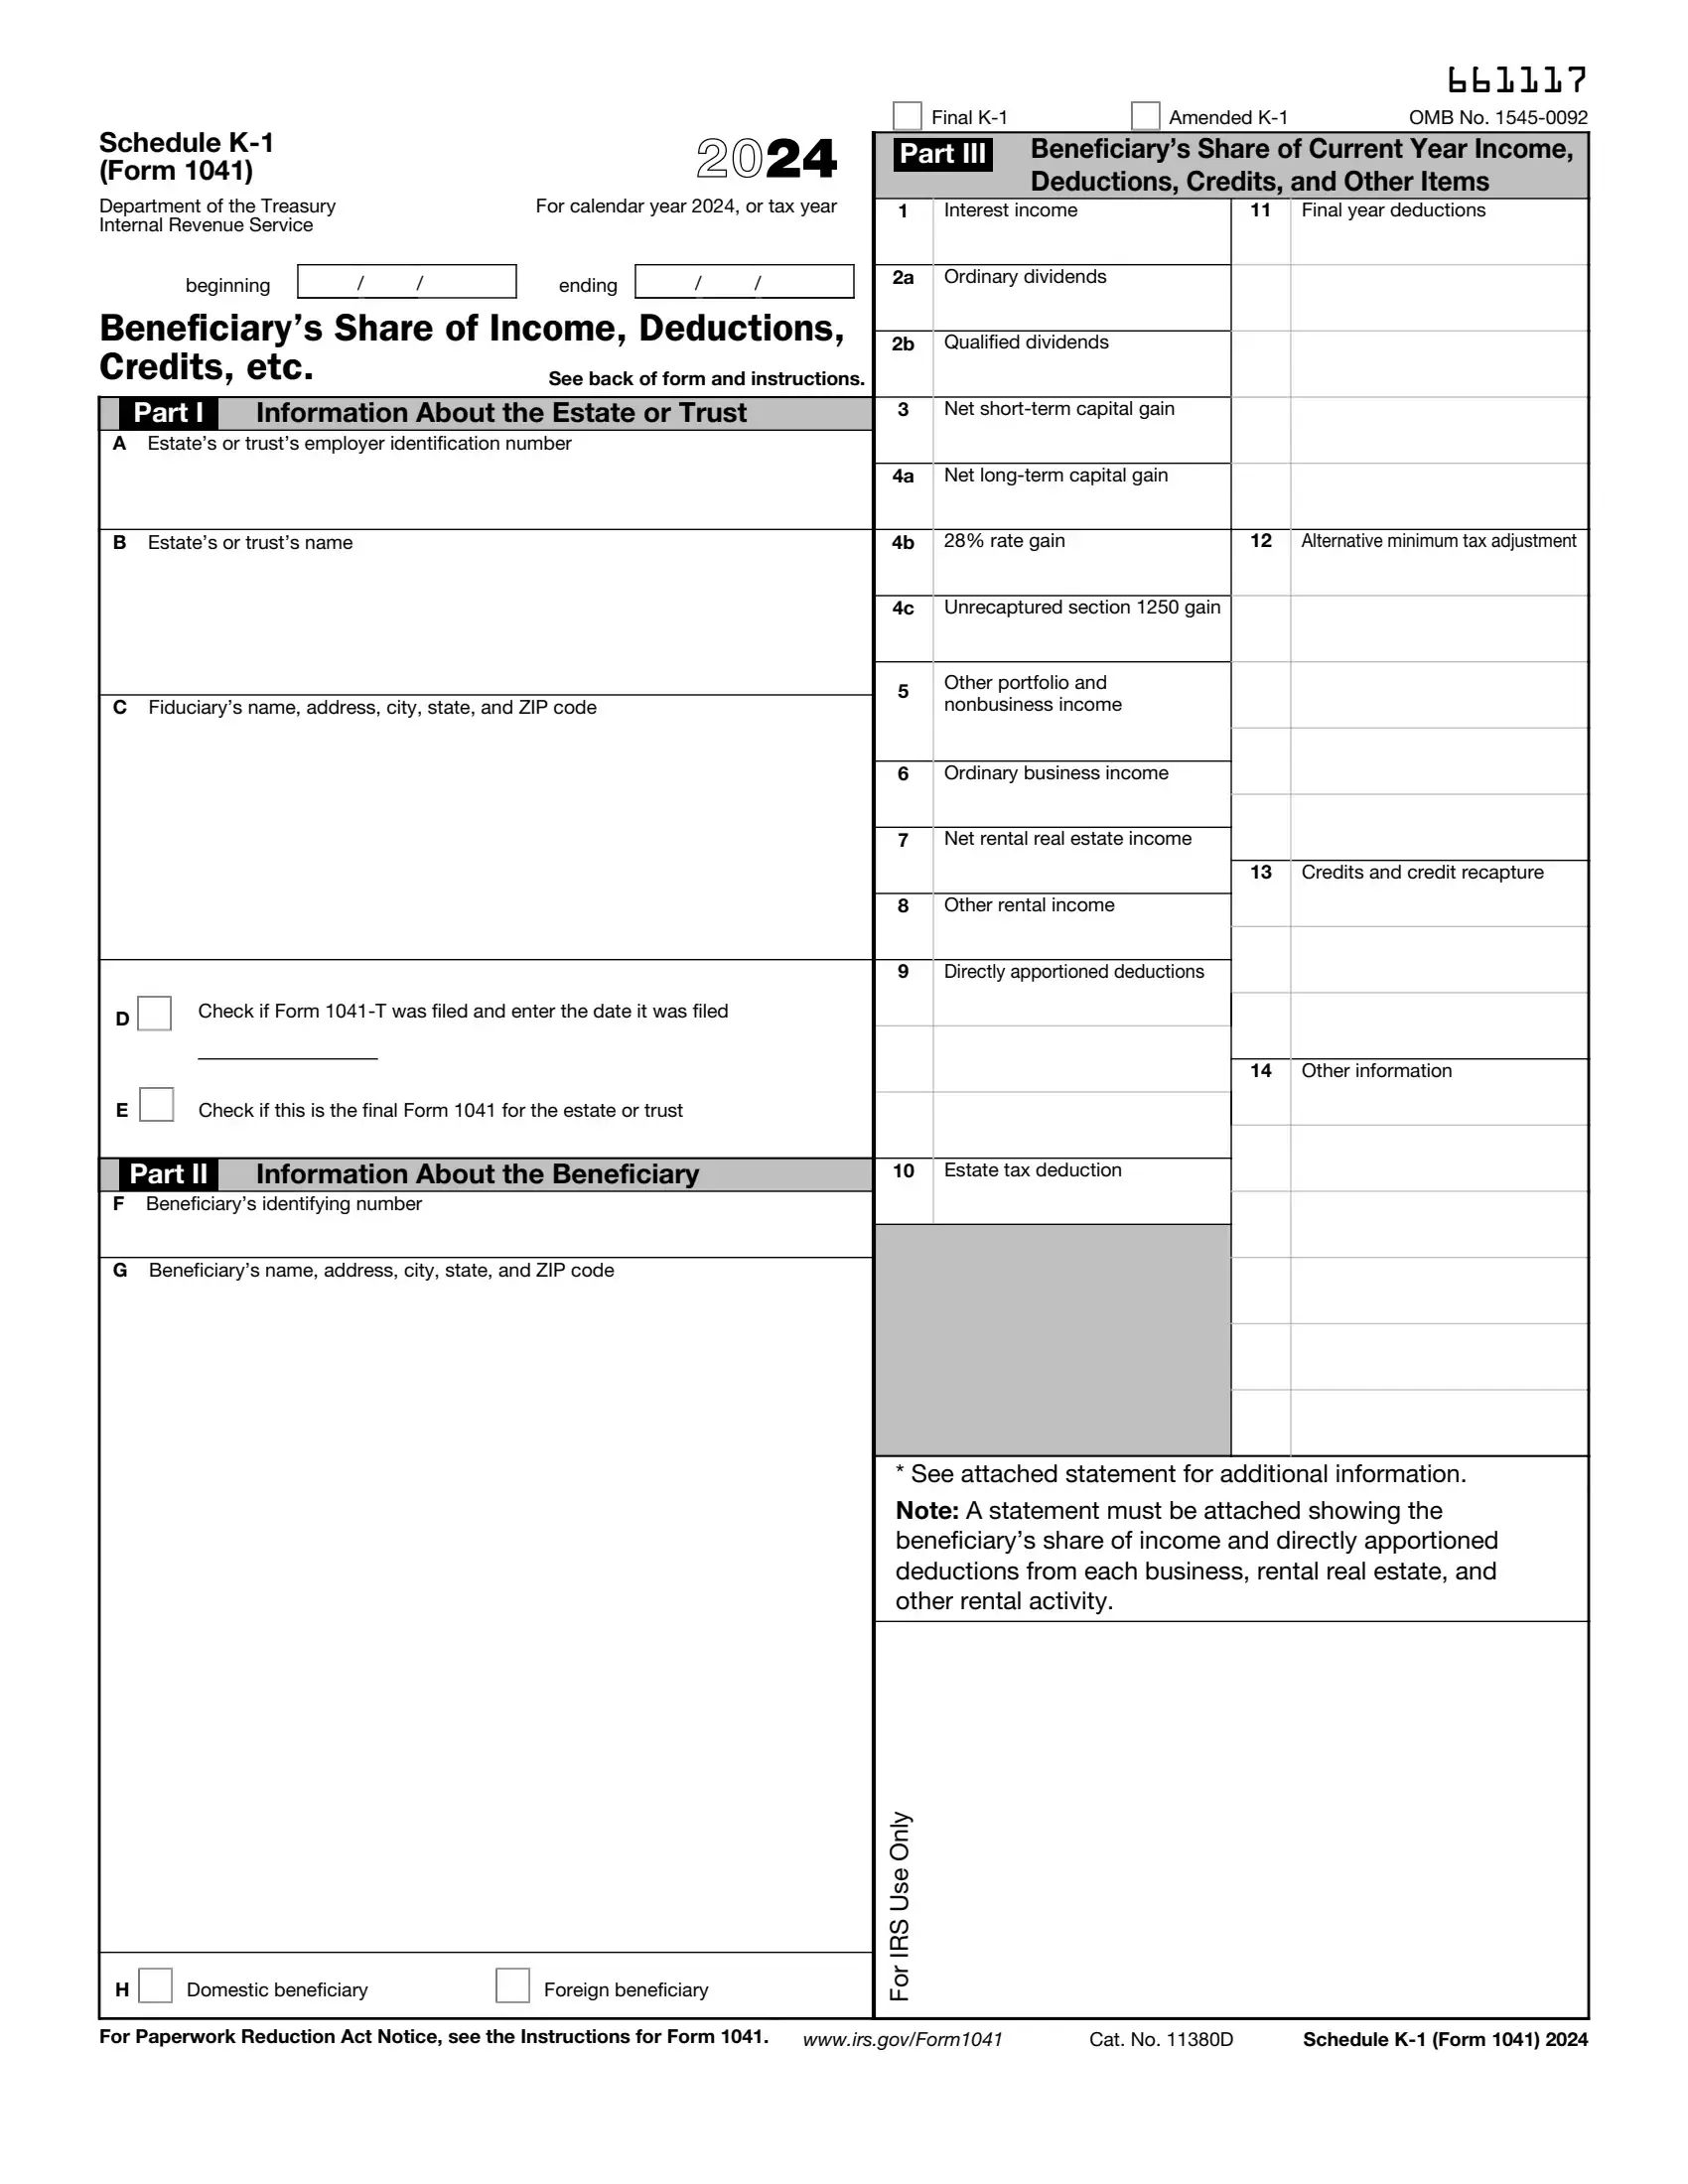
IRS Schedule K-1 (Form 1041) is a document used to report income distributions, deductions, and credits to beneficiaries of estates and trusts. The Schedule K-1 is part of Form 1041, “U.S. Income Tax Return for Estates and Trusts,” which trustees and executors use to report the entity’s income tax liability. Key details included on Schedule K-1 (Form 1041) are:
Filing Schedule K-1 for each beneficiary is crucial as it allows them to accurately report their share of the estate or trust’s income and deductions on their tax returns. It ensures proper tax reporting and compliance with IRS requirements, helping beneficiaries understand their tax liabilities related to distributions received from estates and trusts.
Other IRS Forms for Trusts and Estates
Look through some other important IRS forms for beneficiaries.
What it is: Schedule K-1 (Form 1041) 2025: Beneficiary's Share of Current Year Income, Deductions, Credits, and Other Items.
Where and when to file: Keep it for your records. Don’t file it with your tax return, unless backup withholding was reported in box 13, code B.[3]
Use Schedule K-1 to report a beneficiary's share of the estate's or trust's income, credits, deductions, etc., on your Form 1040 or 1040-SR.[2]
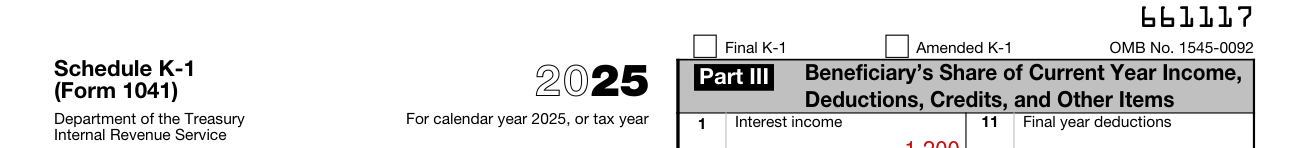
If the “Final K-1” box at the top of Schedule K-1 is checked, this is the final return for the beneficiary.[2]
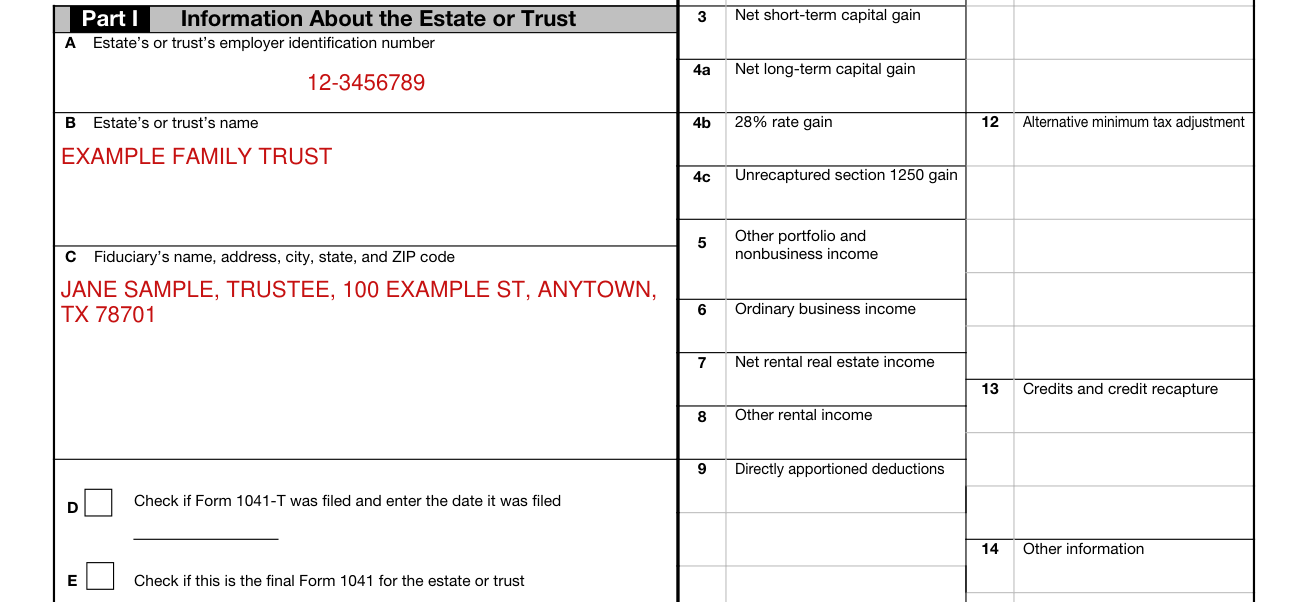
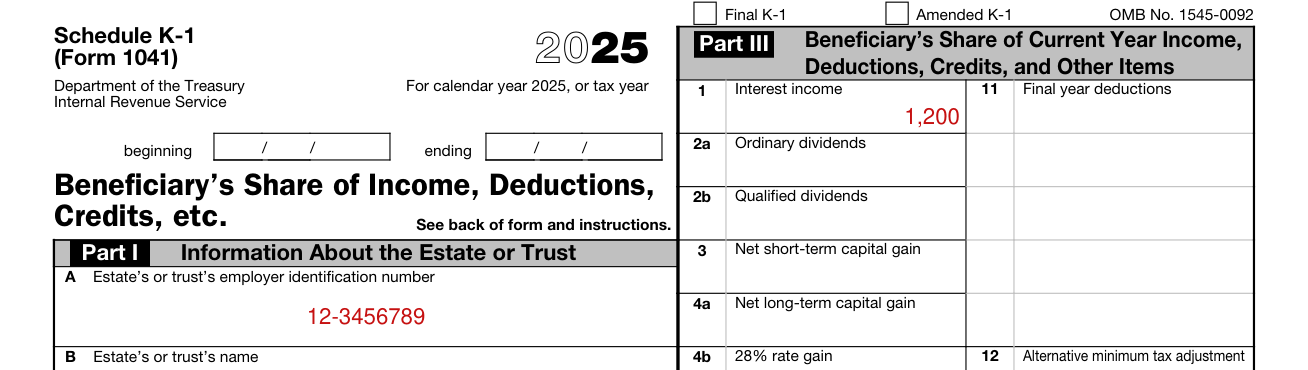
At A, enter the estate's or trust's employer identification number.
At B, enter the estate's or trust's name.
At C, enter the fiduciary's name, address, city, state, and ZIP code.
At D, check if Form 1041-T was filed and enter the date it was filed.
At E, check if this is the final Form 1041 for the estate or trust. If the item E box is checked, this is the final year of the estate or trust.[2]
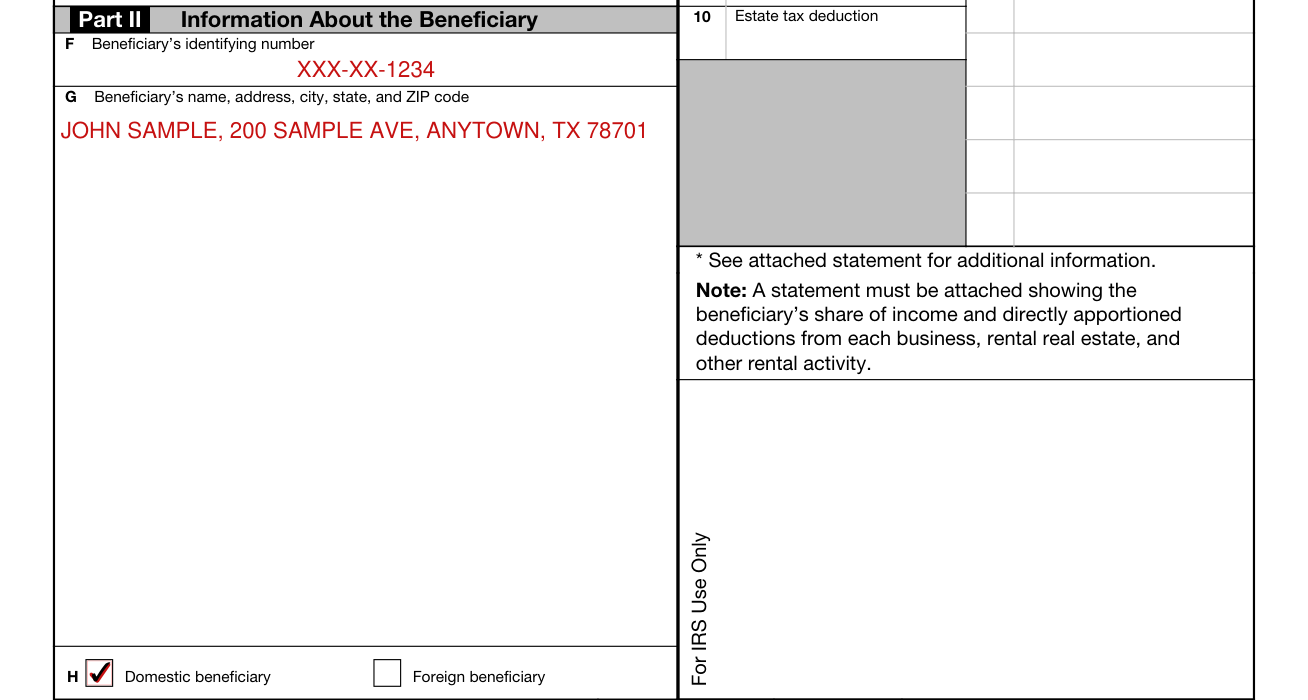
At F, enter the beneficiary's identifying number.
For your protection, Schedule K-1 may show only the last four digits of your identifying number (social security number (SSN), etc.). However, the estate or trust has reported your complete identifying number to the IRS.
At G, enter the beneficiary's name, address, city, state, and ZIP code.
At H, check Domestic beneficiary or Foreign beneficiary.[2]
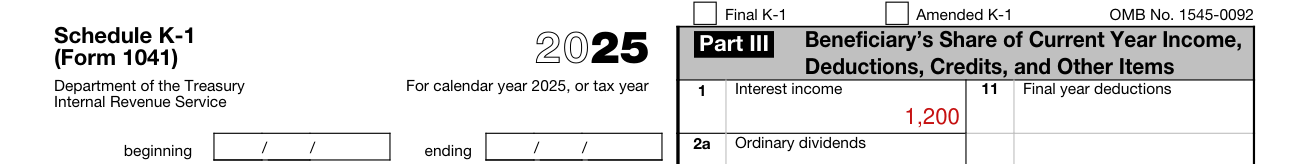
This box reports the beneficiary’s share of the taxable interest income. This amount is reported on line 2b of Form 1040 or 1040-SR and Schedule B (Form 1040), Part I, line 1, if applicable.[3]

This box reports the beneficiary’s share of ordinary dividends. This amount is reported on line 3b of Form 1040 or 1040-SR and Schedule B (Form 1040), Part II, line 5, if applicable.[3]

This box reports the beneficiary’s share of qualified dividends. This amount is reported on line 3a of Form 1040 or 1040-SR.[3]
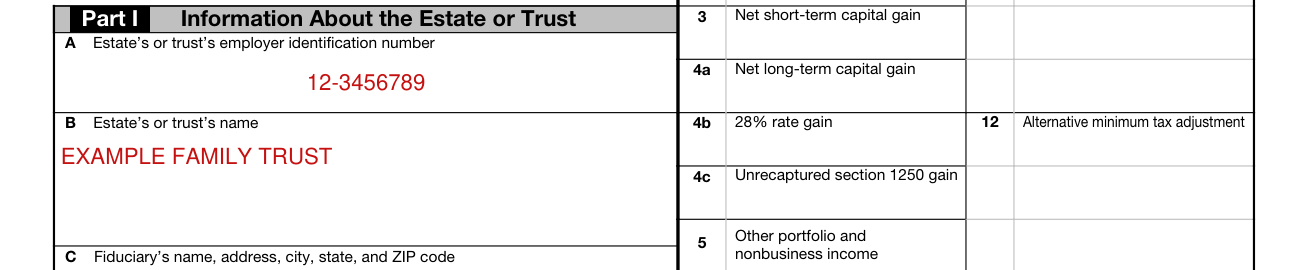
For boxes 3 and 4a, net short-term capital gains are reported on line 5 of Schedule D (Form 1040) and net long-term capital gains are reported on line 12 of Schedule D (Form 1040).[2]
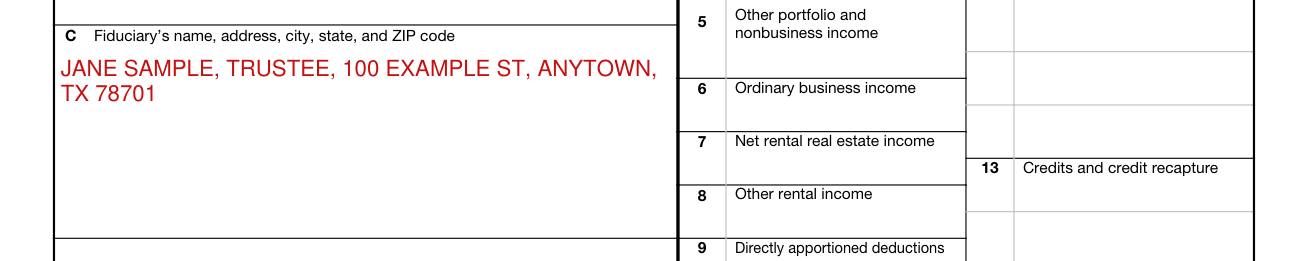
In Box 5, the amount reported is your distributive share of royalties, annuities, and other income that isn't subject to the passive activity rules. It also includes income in respect of a decedent (IRD), which isn't included in box 1, 2a, 3, 4a, 6, 7, or 8.
For boxes 6 through 8, the fiduciary will provide you with a separate schedule showing your distributive share of income from each trade or business, net rental real estate, or other rental activity.[2]
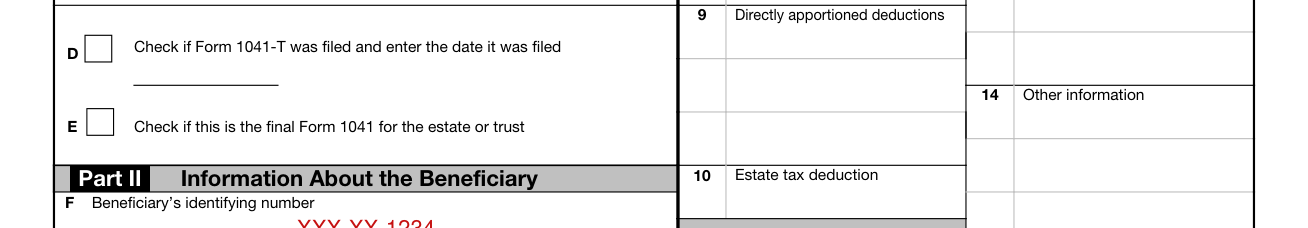
For box 9, the fiduciary must attach a statement showing depreciation, depletion, and amortization directly apportioned to you, if any, for each activity reported in boxes 5 through 8.
For box 10, if an estate or trust distributes IRD to a beneficiary, the beneficiary is entitled to deduct the portion of the estate tax imposed on the decedent's estate which is attributable to the IRD distributed to the beneficiary. You may claim this amount on line 16 of Schedule A (Form 1040).[2]
For box 11, code A, if this is the final return of the estate or trust, and there are excess deductions on termination that are section 67(e) expenses reported to you as a beneficiary, you may deduct the excess deductions shown in box 11, code A, as an adjustment to income. Report this amount on Schedule 1 (Form 1040), Part II, line 24k. A beneficiary who doesn't have enough income in that year to absorb the entire deduction can't carry the balance over to any succeeding year.[2]
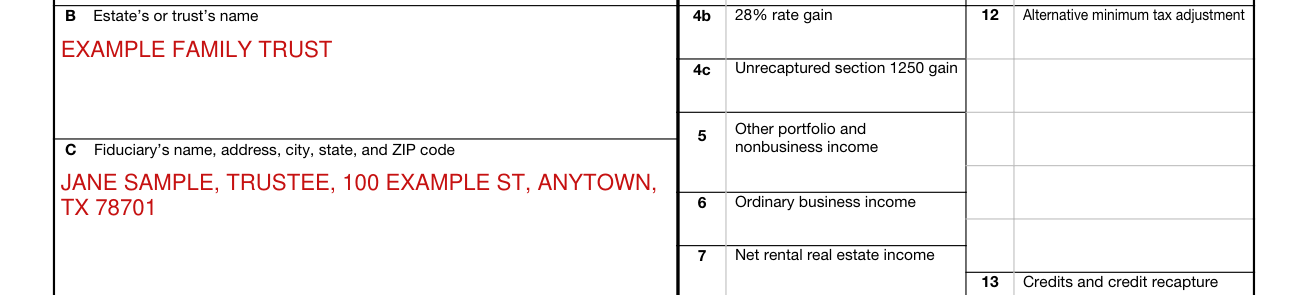
The information reported in box 12, codes A through I, is used to prepare your Form 6251. Code A, Adjustment for minimum tax purposes, is the total amount reported on Form 6251, line 2j. Codes B through F represent the portion, if any, of the amount included in code A.[2]
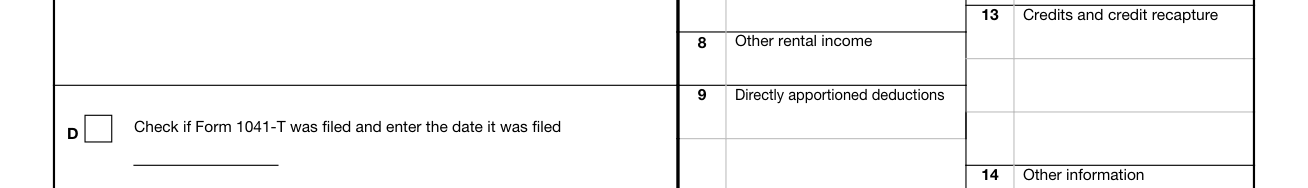
Box 13, codes A through Q, S, T, and ZZ, list all the credits that may be allocated to you as a beneficiary. Code A, Credit for estimated taxes: the beneficiary treats this amount as a payment of estimated tax.
If Schedule K-1 shows backup withholding in box 13, code B, attach a copy to your return.
Include this amount on line 25c of your Form 1040 or 1040-SR and attach a copy of Schedule K-1 (Form 1041) to your return.[2][3]
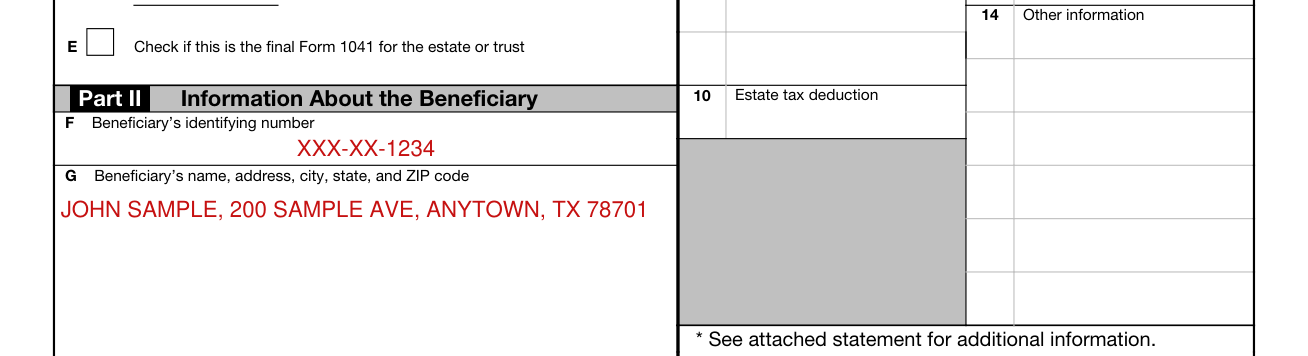
For code ZZ, Other information: if this code is used, the fiduciary will provide you with any additional information you may need to file your return that isn't shown elsewhere on this Schedule K-1.[2]
If the treatment of an item on your original or amended return is inconsistent with the estate's or trust's treatment (or if the estate or trust was required to but hasn't filed a return), you must file Form 8082, Notice of Inconsistent Treatment or Administrative Adjustment Request (AAR), with your original or amended return to identify and explain any inconsistency (or to note that an estate or trust return hasn't been filed).
If you are required to file Form 8082 but fail to do so, you may be subject to the accuracy-related penalty.[2]
If you are not an individual, report the amounts in each box as instructed on your tax return.[2]
For Form 1040 or 1040-SR filers, page 2 of Schedule K-1 provides summarized reporting information.[2]
Schedule K-1 (Form 1041) 2025: Beneficiary's Share of Current Year Income, Deductions, Credits, and Other Items. The amounts shown in boxes 1 through 14 reflect your share of income, loss, deductions, credits, etc., from an estate or trust.[2]
[1] Schedule K-1 (Form 1041) 2025, Beneficiary's Share of Current Year Income, Deductions, Credits, and Other Items, Internal Revenue Service (the Official source link on this page).
[3] irs.gov, item_e_final_year. Accessed October 20, 2026.