
Form 1099-NEC at a glance
What it is: Form 1099-NEC, Nonemployee Compensation, is a form of the Department of the Treasury, Internal Revenue Service.
Where to get it: To order official IRS information returns, which include a scannable Copy A for filing with the IRS and all other applicable copies of the form, go to IRS.gov/EmployerForms.
What to bring and attach to Form 1099-NEC
If you must file any Form 1097, 1098, 1099, 3921, 3922, 5498, or W-2G with the IRS and you are filing paper forms, you must send a Form 1096 with each type of form as the transmittal document.[3]
A filled-in Form 1099-NEC example: a studio reports a freelancer's pay
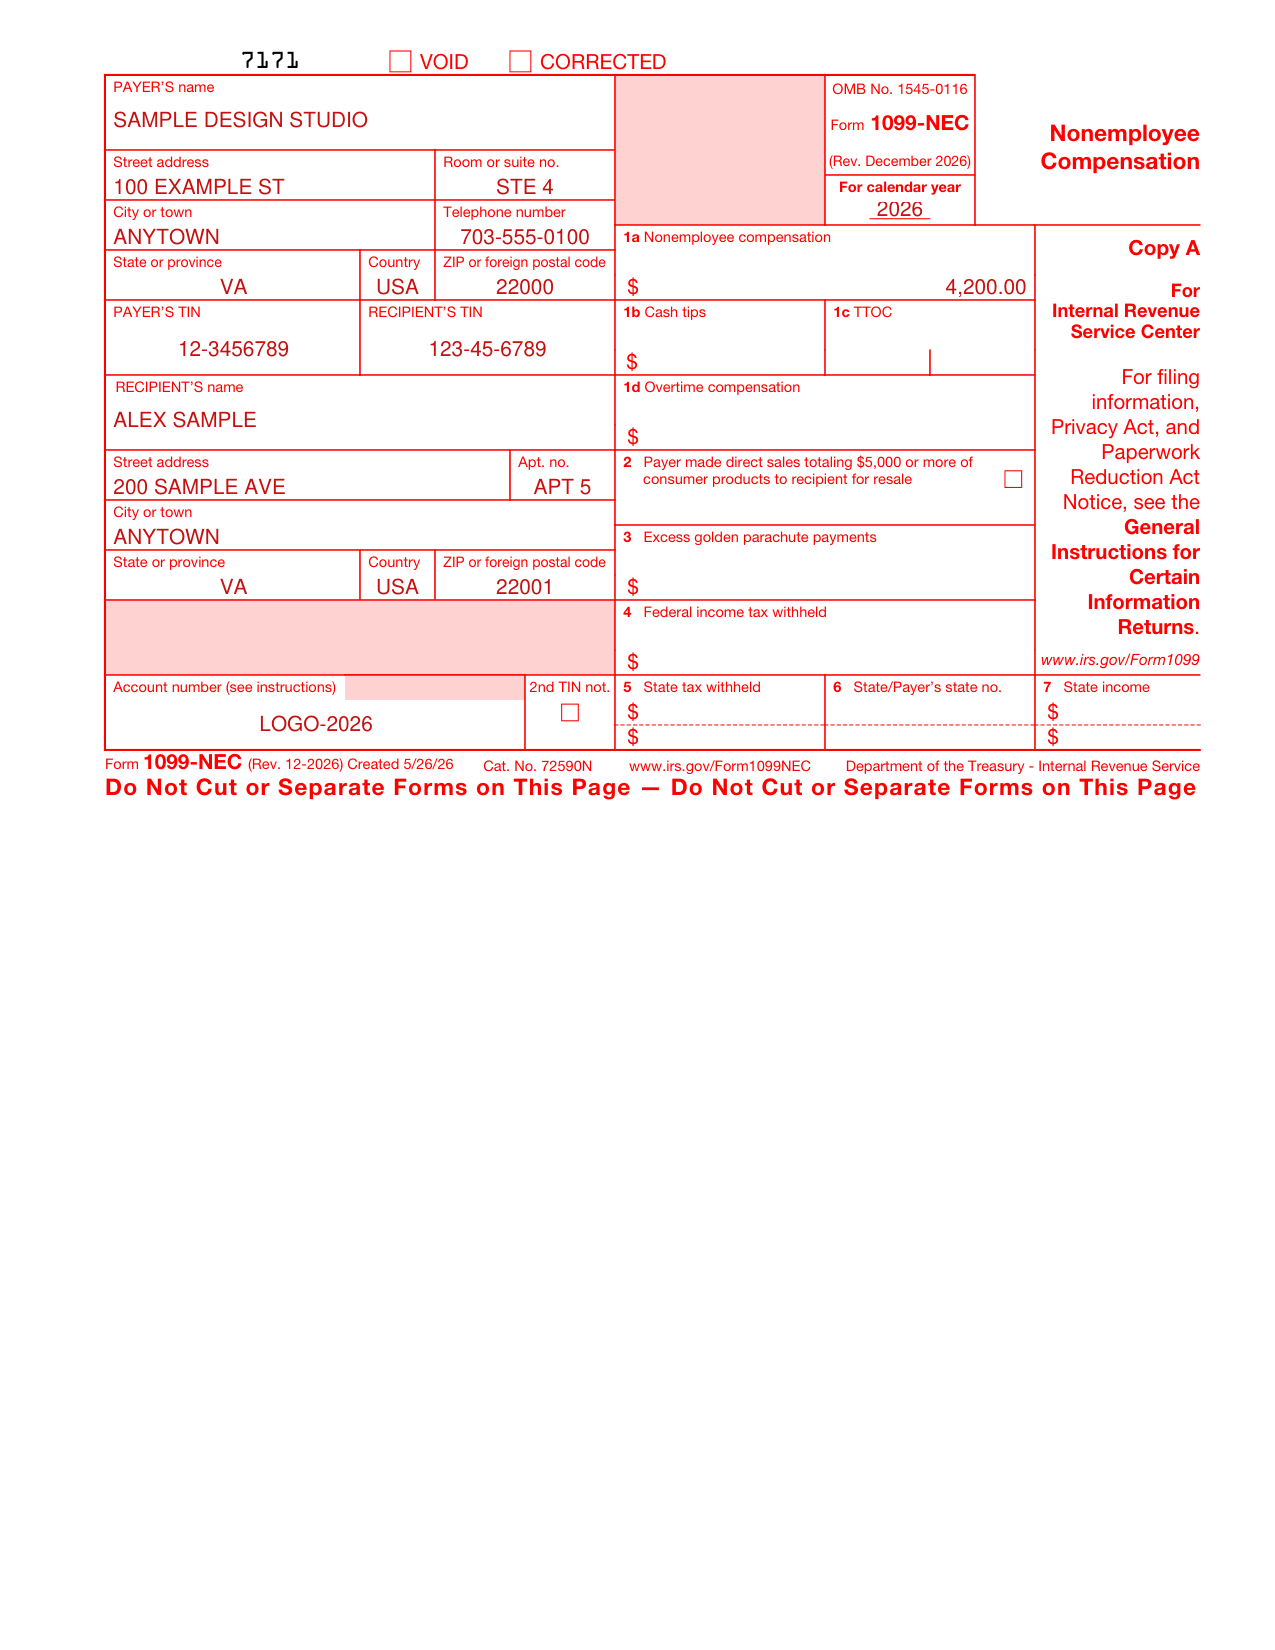
How to fill out Form 1099-NEC, box by box
VOID CORRECTED

If you are filing a correction on a paper form, do not check the VOID box on the form.
A checked VOID box alerts IRS scanning equipment to ignore the form and proceed to the next one.[2]
For calendar year
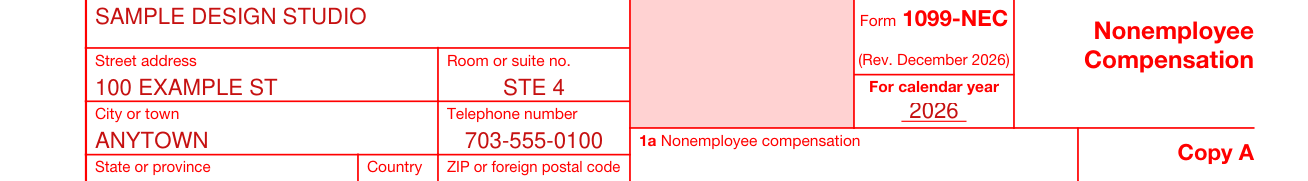
Enter the 4-digit calendar year in the "For calendar year" entry space for the calendar year this form is being filed.[2]
PAYER'S name and address
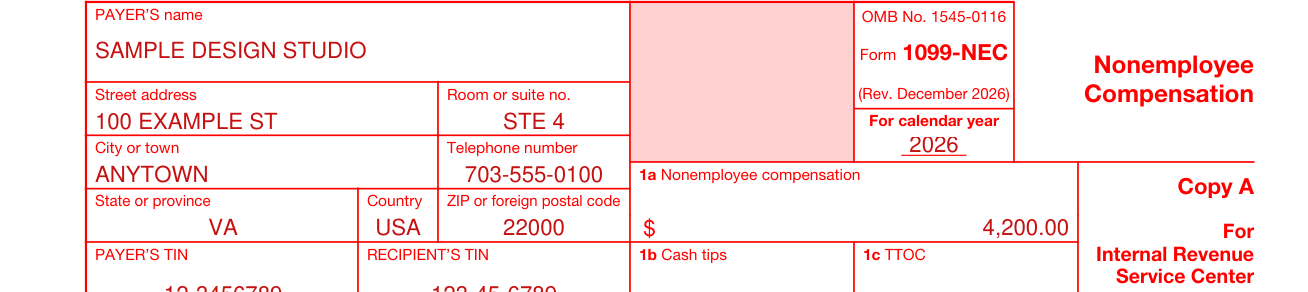
Enter PAYER'S name, Street address, Room or suite no., City or town, Telephone number, State or province, Country and ZIP or foreign postal code.
PAYER'S TIN and RECIPIENT'S TIN

RECIPIENT'S name and address
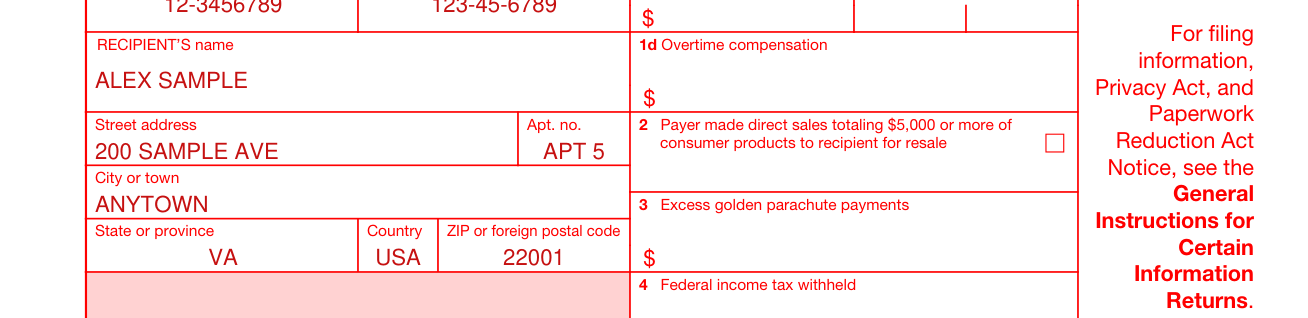
Enter RECIPIENT'S name, Street address, Apt. no., City or town, State or province, Country and ZIP or foreign postal code.
Account number and 2nd TIN not.

The Account number may show an account or other unique number the payer assigned to distinguish the account.
You may enter an "X" in this box, 2nd TIN not., if you were notified by the IRS twice within 3 calendar years that the payee provided an incorrect TIN.
If you mark this box, the IRS will not send you any further notices about this account.[2]
1a Nonemployee compensation
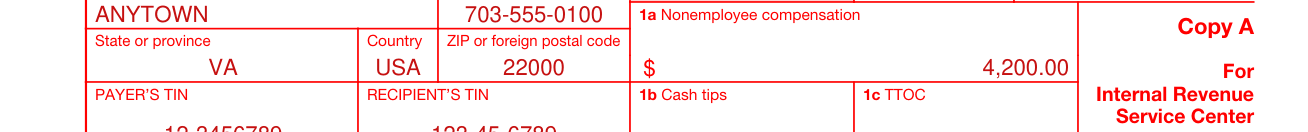
Box 1a shows the total nonemployee compensation.
1b Cash tips and 1c TTOC

Box 1b shows the total amount of cash tips.
"Cash tips" include tips received in cash or charged.
The amount in box 1b has been included in the amount reported in box 1a.
Box 1c shows up to two Treasury Tipped Occupation Code(s) (TTOC) for the tipped occupation(s).
If the occupation code 000 is used, and no other code is included in box 1c, the cash tips are not qualified tips; do not use the amount reported in box 1b for the deduction for qualified tips.
1d Overtime compensation

Box 1d shows the total amount of qualified overtime compensation.
The amount in box 1d has been included in the amount reported in box 1a.
2 Payer made direct sales

If box 2 is checked, consumer products totaling $5,000 or more were sold to the recipient for resale on a buy-sell, a deposit-commission, or another basis (checked October 22, 2026).
3 Excess golden parachute payments

Box 3 shows the total compensation of excess golden parachute payments subject to a 20% excise tax.
4 Federal income tax withheld

Box 4 shows backup withholding.
A payer must backup withhold on certain payments if the recipient did not give the TIN to the payer.
See Form W-9, Request for Taxpayer Identification Number and Certification, for information on backup withholding.
5 State tax withheld, 6 State/Payer's state no. and 7 State income
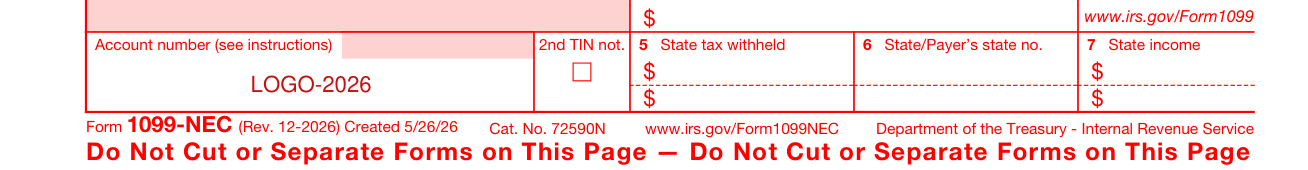
Boxes 5-7 are the State income tax withheld reporting boxes.
In box 6, enter the abbreviated name of the state and the payer's state identification number.
In box 7, you may enter the amount of the state payment.[2]
More rules for Form 1099-NEC
Copy 2 is to be filed with the recipient's state income tax return, when required.
If your situation is different
You received this form from a payer
The recipient received this form instead of Form W-2 because the payer did not consider the recipient an employee and did not withhold income tax or social security and Medicare taxes.
Recipient's taxpayer identification number (TIN). For your protection, this form may show only the last four digits of your TIN (social security number (SSN), individual taxpayer identification number (ITIN), adoption taxpayer identification number (ATIN), or employer identification number (EIN)). However, the issuer has reported your complete TIN to the IRS.
If you believe you are an employee and cannot get the payer to correct this form, report the amount shown in box 1 on the line for "Wages, salaries, tips, etc." of Form 1040, 1040-SR, or 1040-NR, and also complete Form 8919 and attach it to your return.
For more information, see Pub. 1779, Independent Contractor or Employee.
If you are not an employee but the amount in box 1 is not self-employment (SE) income (for example, it is income from a sporadic activity or a hobby), report the amount shown in box 1 on the "Other income" line (on Schedule 1 (Form 1040)).
If the amount in box 1a is SE income, report it on Schedule C or F (Form 1040) if a sole proprietor or on Form 1065 and Schedule K-1 (Form 1065) if a partnership, and the recipient/partner completes Schedule SE (Form 1040).
Include the amount in box 4 on your income tax return as tax withheld.
If you are receiving payments on which no income, social security, and Medicare taxes are withheld, you should make estimated tax payments; see Form 1040-ES (or Form 1040-ES (NR)).
Individuals must report these amounts as explained in these box 1 instructions. Corporations, fiduciaries, and partnerships must report these amounts on the appropriate lines of their tax returns.
If you are required to file a return, a negligence penalty or other sanction may be imposed on you if this income is taxable and the IRS determines that it has not been reported.
Common questions about Form 1099-NEC
How do I get a 1099-NEC form from the IRS?
To order official IRS information returns, which include a scannable Copy A for filing with the IRS and all other applicable copies of the form, go to IRS.gov/EmployerForms. The order limit for most information returns is 10 due to the e-file requirement.
Is there a printable 1099 form?
You may download and print Copy B and other copies of this form, which appear in black, to satisfy the requirement to furnish the information to the recipient.
Do I need to send 1099-NEC to the IRS?
Section 6071(c) requires you to file Form 1099-NEC on or before January 31, using either paper or electronic filing procedures. Filers of information returns, including Forms 1099-NEC and 1099-S, must furnish a copy of what is or will be filed with the IRS to the recipient.[2]
Is there a deadline?
You are required to furnish the payee statements and file with the IRS by January 31.[2]
Where do I file it?
If you have 10 or more information returns, in the aggregate, to file, you may be required to e-file information returns. You'll find that it is easier and faster to e-file using the IRS free Information Return Intake System (IRIS). See IRS.gov/InfoReturn and IRS.gov/IRIS for details.
Is there a penalty?
Do not print and file copy A of this PDF; we may impose a penalty for filing information return forms that we can't scan.
Sources
[1] Form 1099-NEC (Rev. December 2026), Nonemployee Compensation, Department of the Treasury, Internal Revenue Service (the Official source link on this page).
[2] irs.gov, line_void_corrected_doc_no_void_on_paper_correction. Accessed October 22, 2026.
[3] irs.gov, documents_to_bring. Accessed October 22, 2026.
