

Form 100S at a glance
What it is: Form 100S, the 2025 California S Corporation Franchise or Income Tax Return, is used if a corporation has elected to be a small business corporation (S corporation).
Where and when to file: Mail Form 100S with payment to: FRANCHISE TAX BOARD PO BOX 942857 SACRAMENTO CA 94257-0501
All federal S corporations subject to California laws must file Form 100S and pay the greater of the minimum franchise tax or the 1.5% income or franchise tax.
What to bring and attach to Form 100S
Assemble the corporation return in the following order: Form 100S, ScheduleR (if required), supporting schedules, a copy of federal return (if required), and form FTB 5806, Underpayment of Estimated Tax by Corporations, (if required).
Use black or blue ink on the tax return sent to the FTB.
Send a clean legible copy.
A filled-in Form 100S example: a small calendar-year S corporation
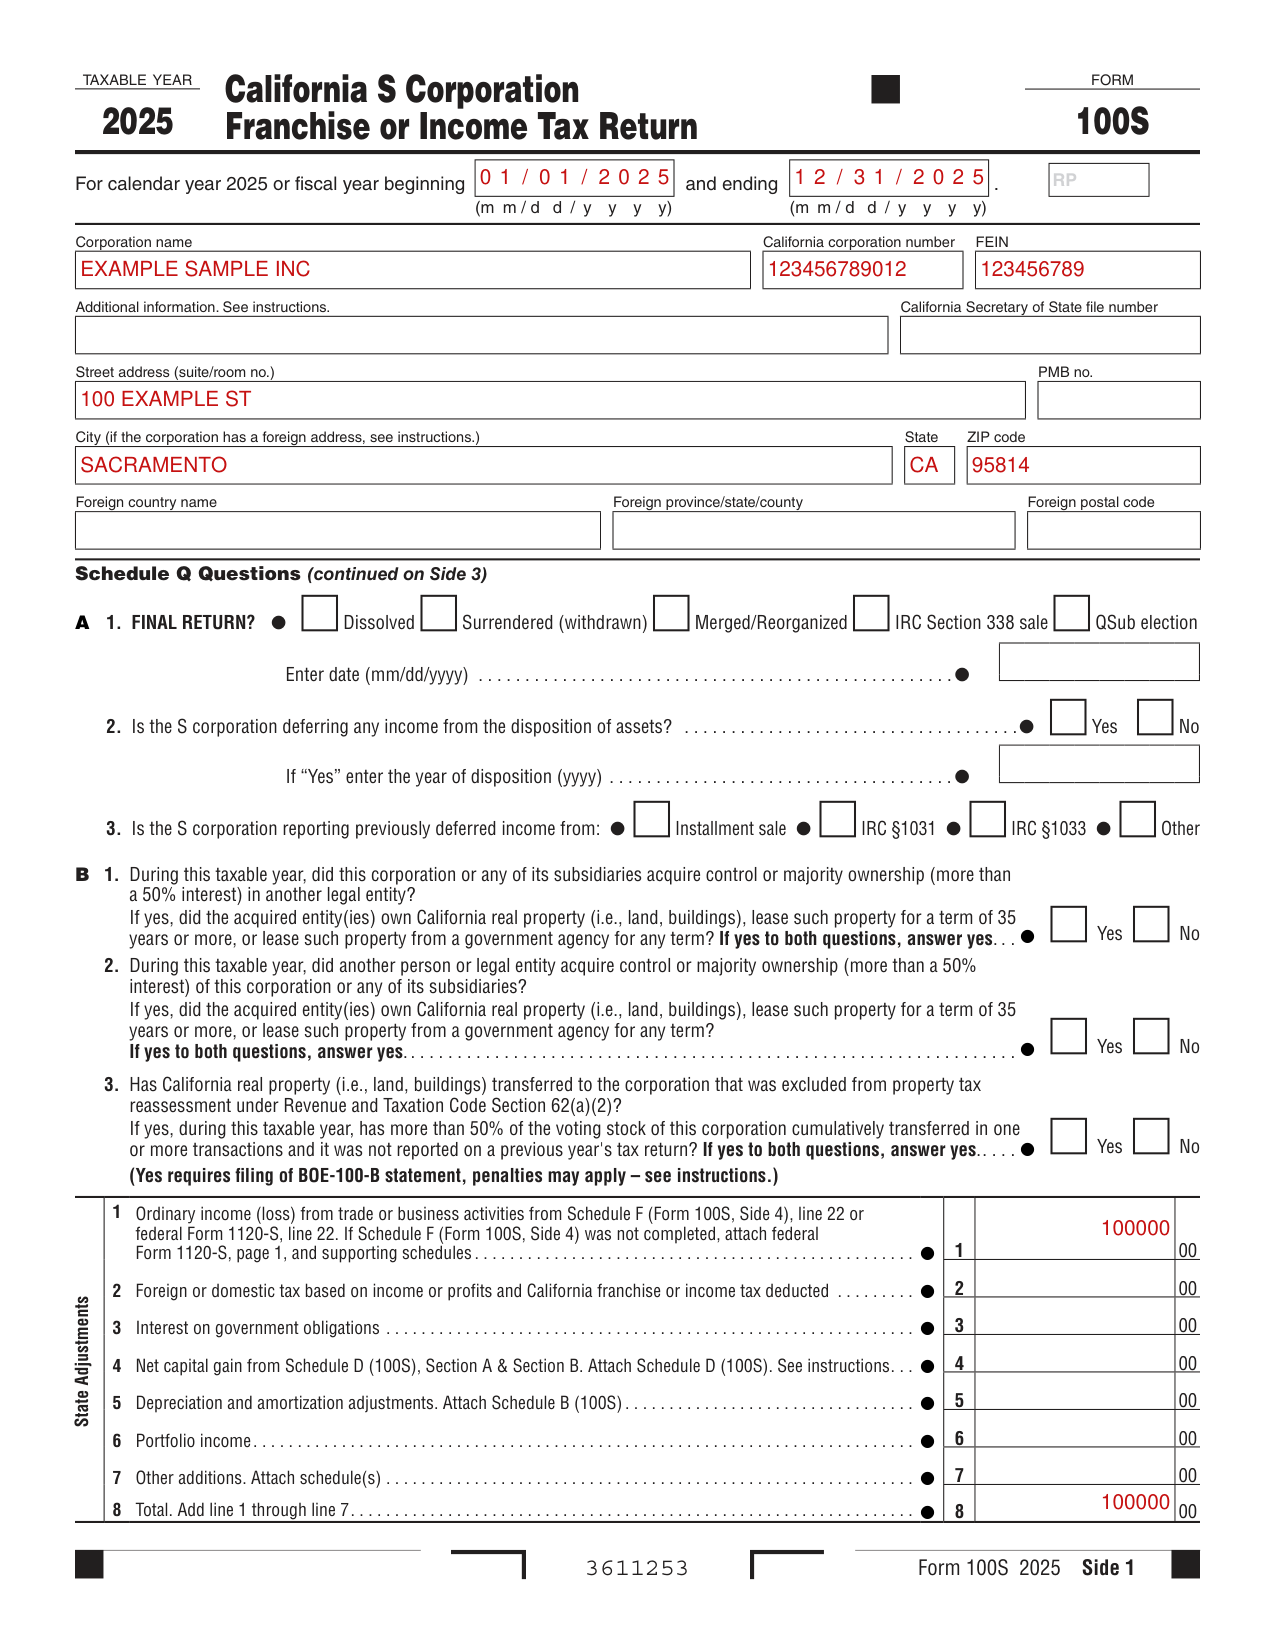
How to fill out Form 100S, box by box
Corporation name and address
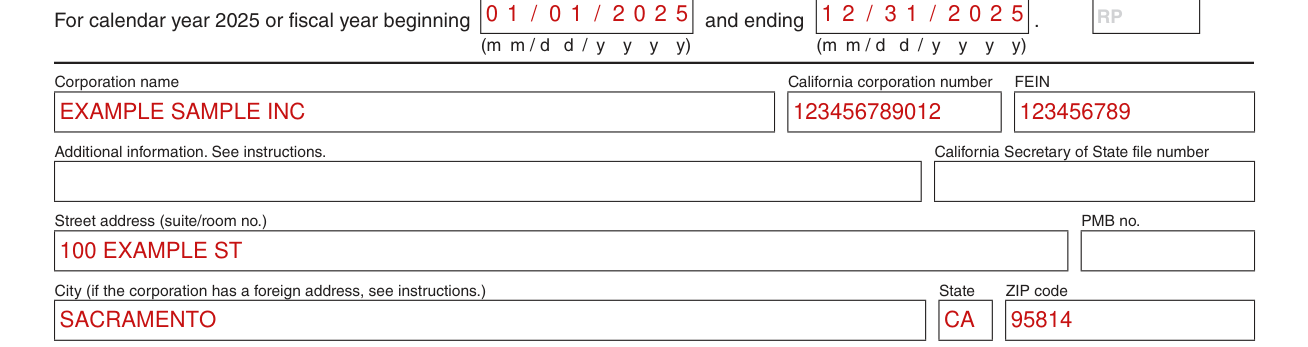
Print name and address (in CAPITAL LETTERS).
When a domesticS corporation files the first California tax return, the fiscal year beginning date must be the date the S corporation is incorporated.
Lines 1 to 8, Ordinary income and Total
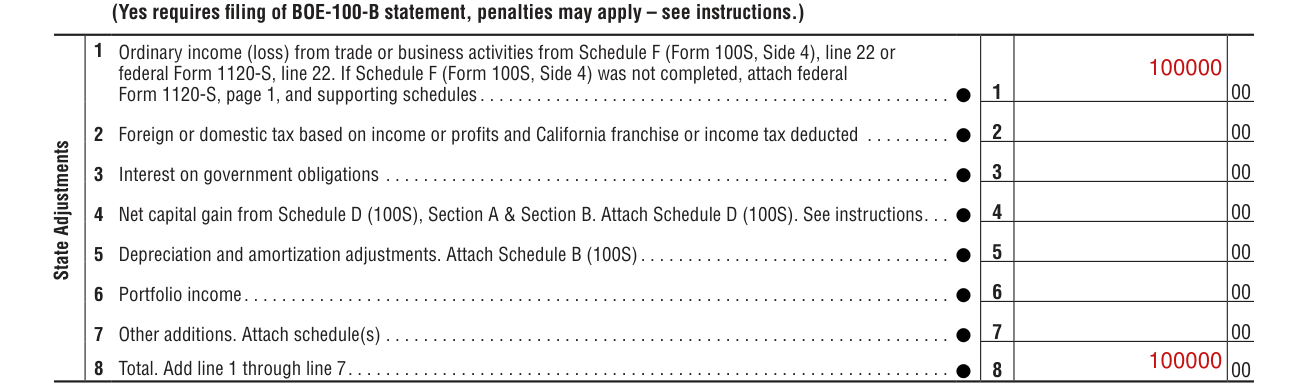
1 Ordinary income (loss) from trade or business activities from Schedule F (Form 100S, Side 4), line 22 or federal Form 1120-S, line 22. If Schedule F (Form 100S, Side 4) was not completed, attach federal Form 1120-S, page 1, and supporting schedules
Round cents to the nearest whole dollar.
Line 8, Total: Add line 1 through line 7.
Lines 9 to 20, Net income
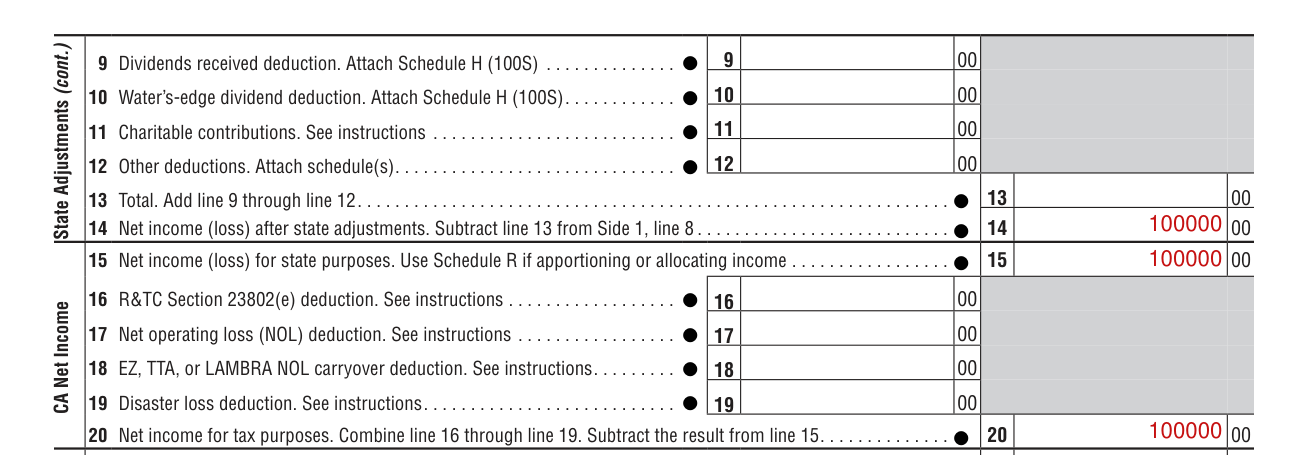
13 Total. Add line 9 through line 12. 14 Net income (loss) after state adjustments. Subtract line 13 from Side 1, line 8.
Line 15, Net income (loss) for state purposes: Use Schedule R if apportioning or allocating income.
Line 20, Net income for tax purposes: Combine line 16 through line 19. Subtract the result from line 15.
Lines 21 to 30, Tax
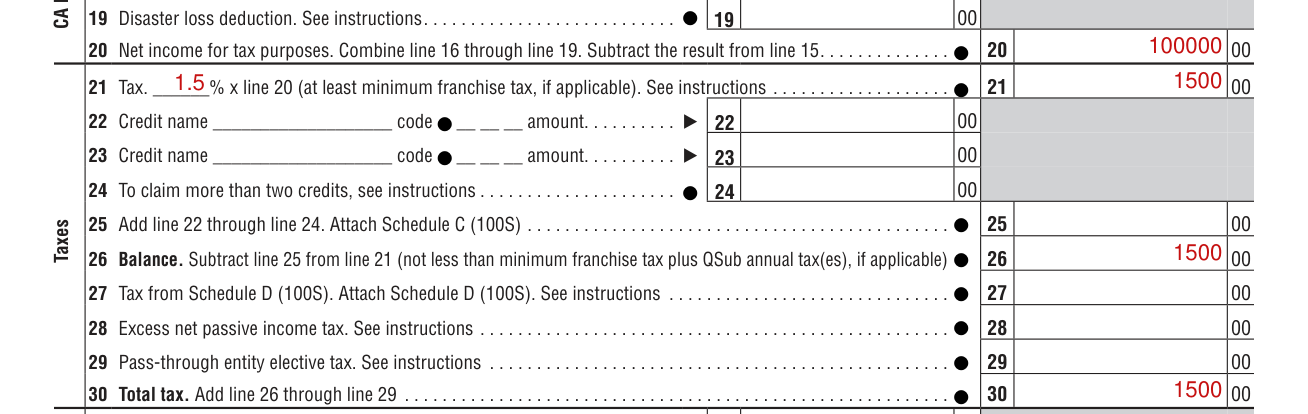
Line 21: S corporations must use a tax rate of 1.5%. Financial S corporations must use the financial tax rate of 3.5%.
Line 21, Tax: % x line 20 (at least minimum franchise tax, if applicable).
The minimum franchise tax is $800 and must be paid whether the S corporation is active, inactive, operates at a loss, or files a return for a short-period of less than 12 months. (checked November 8, 2026)
A corporation that incorporated or qualified through the California Secretary of State (SOS) to do business in California is not subject to the minimum franchise tax for its first taxable year and will compute its tax liability by multiplying its state net income by the appropriate tax rate.
Line 26, Balance: Subtract line 25 from line 21 (not less than minimum franchise tax plus QSub annual tax(es), if applicable).
Line 30, Total tax: Add line 26 through line 29.
Lines 31 to 45, Total payments, Overpayment and Total amount due
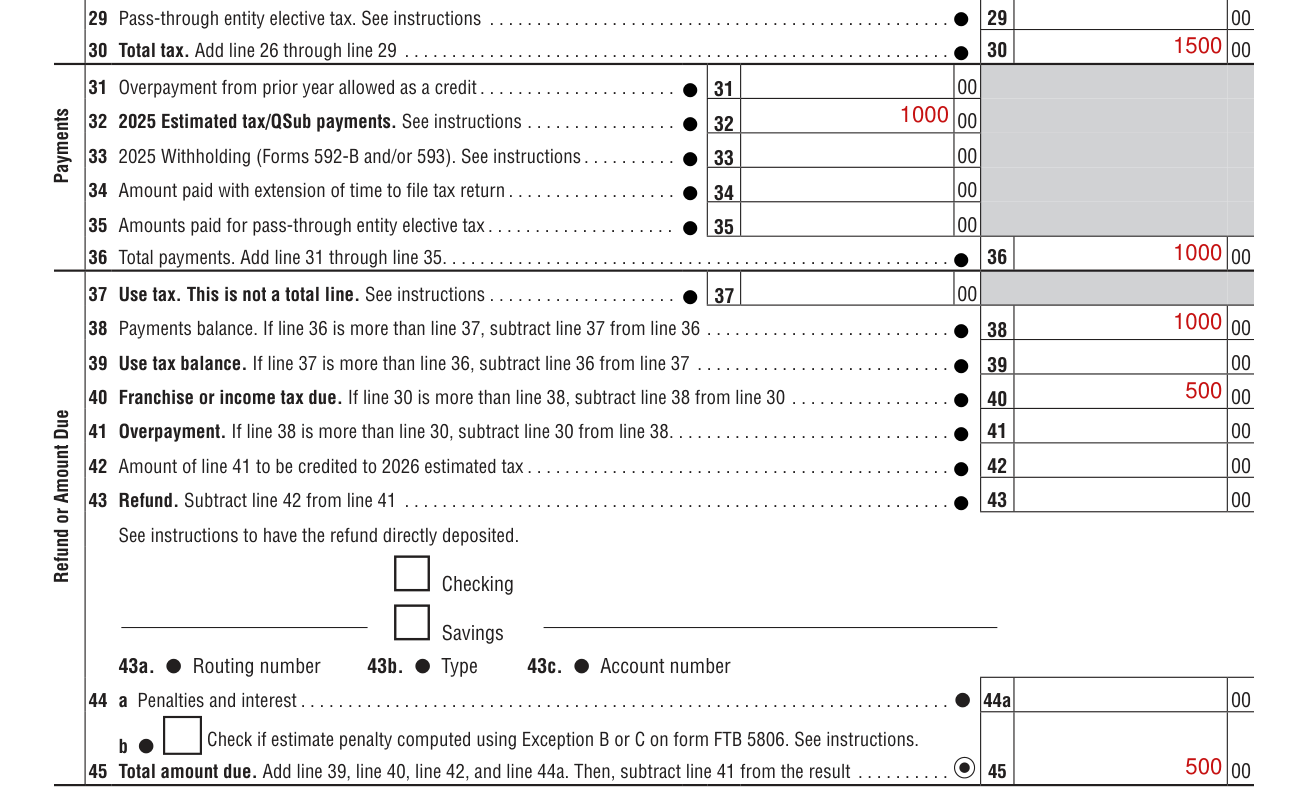
When making a payment with a check or money order, enclose but do not staple the payment to the front of the tax return.
Line 36, Total payments: Add line 31 through line 35.
Line 38, Payments balance: If line 36 is more than line 37, subtract line 37 from line 36.
Line 40, Franchise or income tax due: If line 30 is more than line 38, subtract line 38 from line 30.
Line 41, Overpayment: If line 38 is more than line 30, subtract line 30 from line 38.
Line 45, Total amount due: Add line 39, line 40, line 42, and line 44a. Then, subtract line 41 from the result.
Complete and attach form FTB 5806, to the back of Form 100S (after all schedules and federal return) only if Exception B or Exception C of form FTB 5806 is used to compute or eliminate the penalty. Be sure to check the box on line 44b.
Sign Here

Under penalties of perjury, I declare that I have examined this return, including accompanying schedules and statements, and to the best of my knowledge and belief, it is true, correct, and complete.
If the S corporation wants to allow the FTB to discuss its 2025 tax return with the paid preparer who signed it, check the “Yes” box in the signature area of the return.
More rules for Form 100S
When the due date falls on a weekend or holiday, the deadline to file and pay without penalty is extended to the next business day.
Extensions, late returns and refunds
The S corporation cannot file by the original due date
If an S corporation cannot file its California tax return by the 15th day of the 3rd month after the close of the taxable year, it may file on or before the 15th day of the 9th month without filing a written request for an extension.
The full amount of tax must be paid by the original due date of Form 100S.
If there is an unpaid tax liability on the original due date, complete form FTB 3539, Payment for Automatic Extension for Corporations and Exempt Organizations, and send it with the payment by the original due date of the Form 100S.
The S corporation files late
The delinquent filing penalty is computed at 5% of the tax due, after allowing for timely payments, for every month that the return is late, up to a maximum of 25%.
If an S corporation is subject to both the penalty for failure to file a timely return and the penalty for failure to pay the total tax by the due date, a combination of the two penalties may be assessed, but the total will not exceed 25% of the unpaid tax.
Mail Form 100S requesting a refund
Mail Form 100S requesting a refund, a return without payment, to: FRANCHISE TAX BOARD PO BOX 942857 SACRAMENTO CA 94257-0500
Common questions about Form 100S
Is there a deadline?
File Form 100S by the 15th day of the 3rd month after the close of the taxable year unless the return is for a short-period as required under R&TC Section 24634. Generally, the due date of a short-period return is the same as the due date of the federal short-period return.
Where do I file it?
Mail Form 100S with payment to: FRANCHISE TAX BOARD PO BOX 942857 SACRAMENTO CA 94257-0501
Is there a penalty?
Any S corporation that fails to pay the total tax shown on Form 100S by the original due date is assessed a penalty. The penalty is 5% of the unpaid tax, plus 0.5% for each month, or part of the month (not to exceed 40 months) the tax remains unpaid. This penalty may not exceed 25% of the unpaid tax.
Sources
[1] 2025 Form 100S booklet, California Franchise Tax Board (the Official source link on this page).