
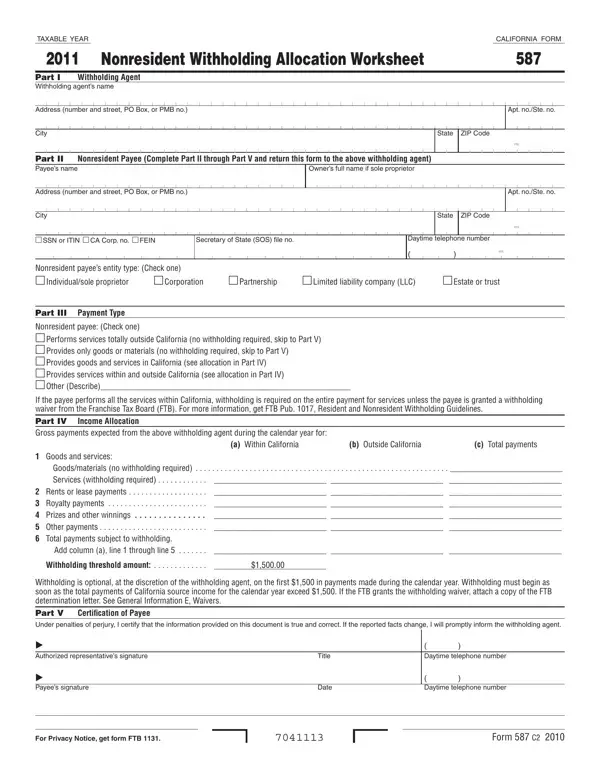
The withholding agent keeps this form with their records.
No withholding: No withholding is required if the payee performs services totally outside California or provides only goods or materials.
All services in California: Withholding is required on the entire payment for services unless the payee is granted a withholding waiver from the Franchise Tax Board.
Entity type: Check one: individual/sole proprietor, corporation, partnership, limited liability company (LLC), or estate or trust.
Part IV: Income Allocation lists gross payments expected from the withholding agent during the calendar year within California, outside California and in total.
| Question | Answer |
|---|---|
| Form Name | Form 587 |
| Official Title | Nonresident Withholding Allocation Worksheet |
| Issued By | California Franchise Tax Board (FTB) |
| Purpose | Allocate California-source income for nonresident withholding tax |
| Withholding Rate | 7% (individuals), 8.84% (corporations), 13.8% (S corps) |
| Withholding Threshold | California-source payments exceeding $1,500 per calendar year |
| Form Length | 1 page |
| Fillable? | Yes |
| Fillable fields | 48 |
| Avg. time to fill out | 8 min |
| Edition | 2025 |
| Returned to | The withholding agent |
| Matches the agency's file | Yes, checked October 3, 2026 |
| Other names | 587, Form 587, CA 587, CA Form 587, California Form 587, FTB 587, Nonresident Withholding Allocation Worksheet |
| Official source | California Form 587 (2025), Franchise Tax Board |
California Form 587 isn’t the one you’re looking for?