
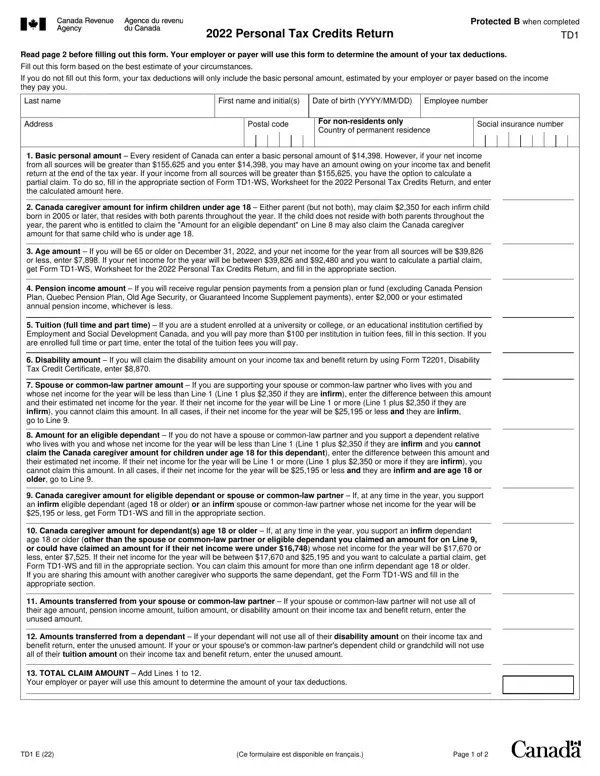
Form TD1 at a glance
What it is: Form TD1 is the 2026 Personal Tax Credits Return.
Who signs: Sign and date it, and give it to your employer or payer.
Fill out this form only if any of the following apply:
you have a new employer or payer, and you will receive salary, wages, commissions, pensions, employment insurance benefits, or any other remuneration; you want to change the amounts you previously claimed (for example, the number of your eligible dependants has changed); you want to claim the deduction for living in a prescribed zone; you want to increase the amount of tax deducted at source.
A filled-in Form TD1 example: a new employee claims the basic personal amount
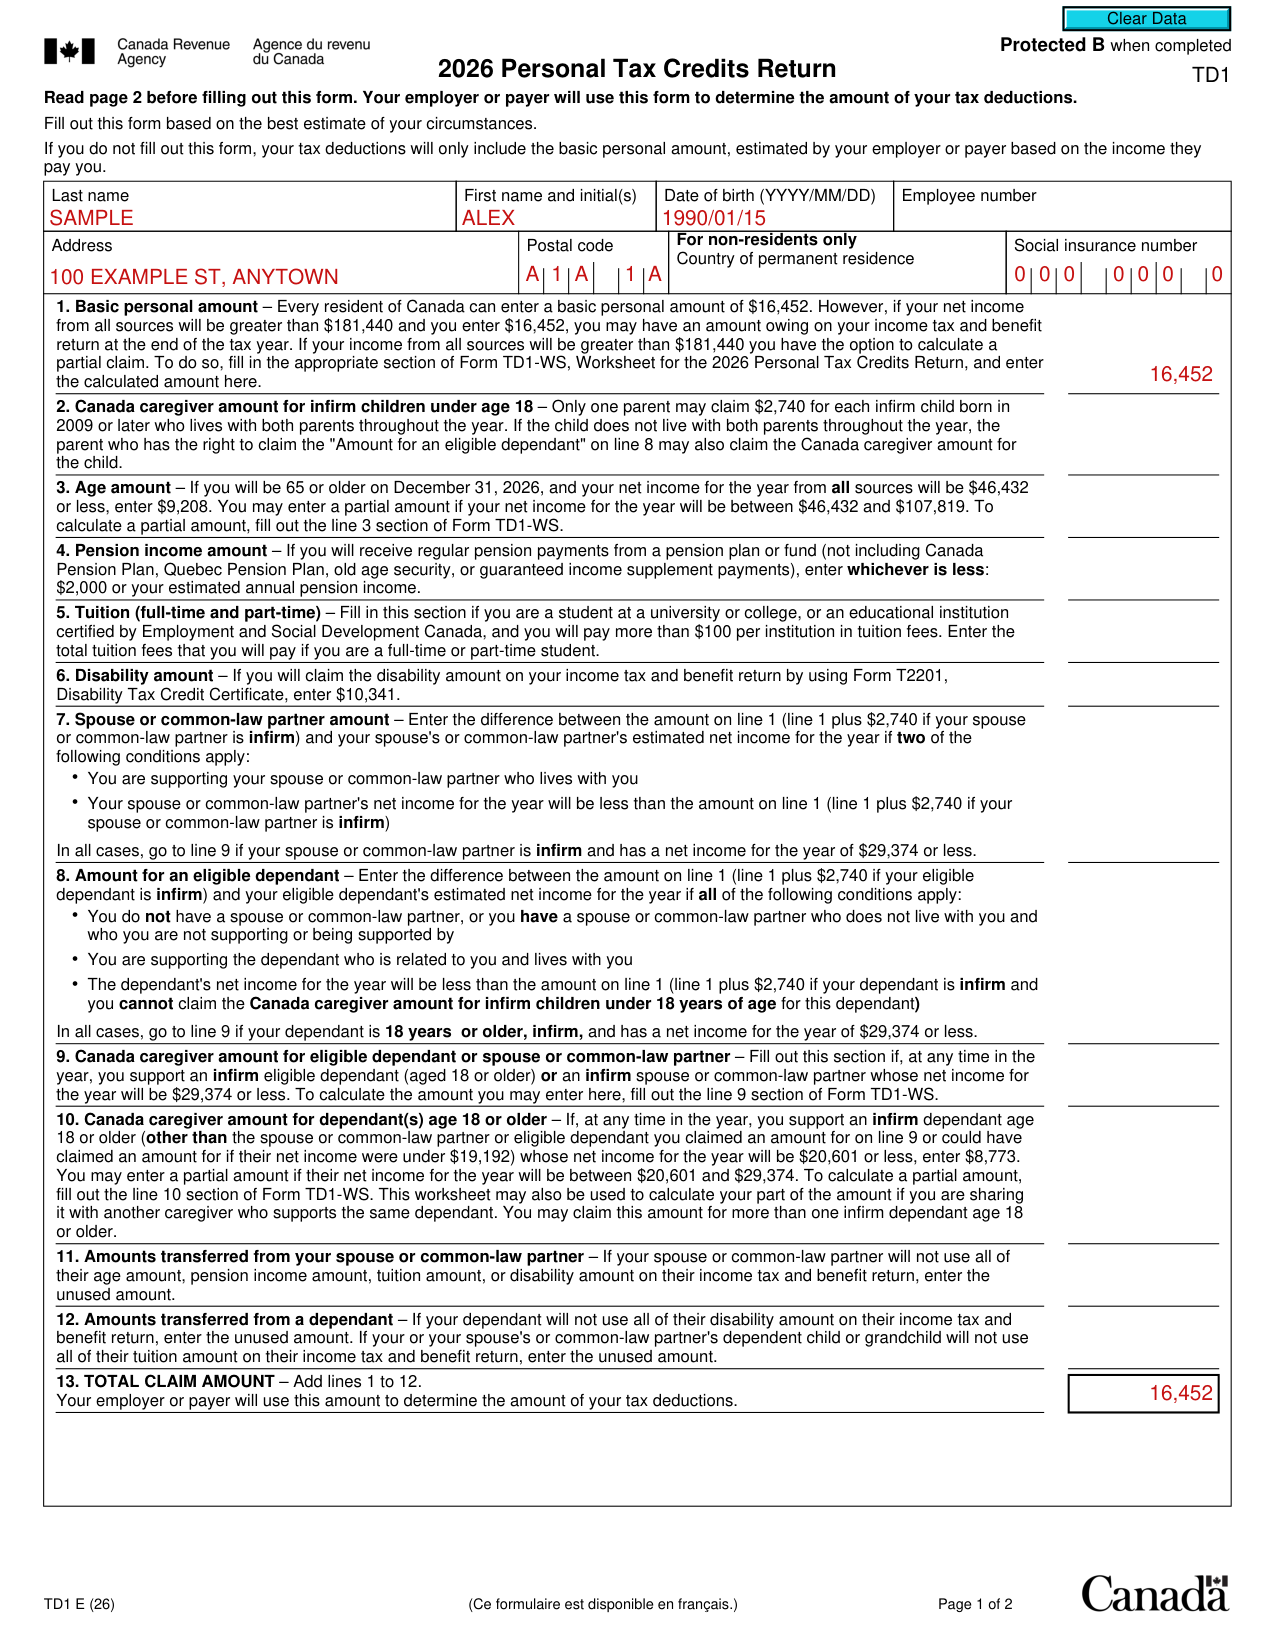
How to fill out Form TD1, box by box
Last name, Address and Social insurance number
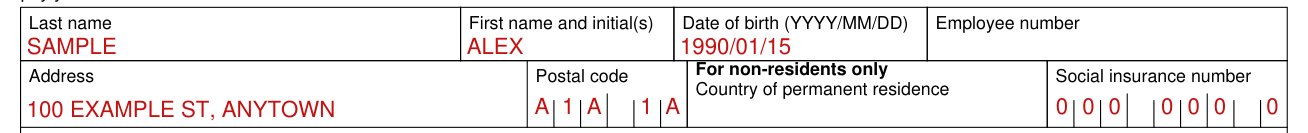
Fill in Last name, First name and initial(s), Date of birth (YYYY/MM/DD) and Employee number.
Fill in Address, Postal code and Social insurance number.
1. Basic personal amount

Every resident of Canada can enter a basic personal amount of $16,452. (checked November 9, 2026)
If your net income from all sources will be greater than $181,440 and you enter $16,452, you may have an amount owing on your income tax and benefit return at the end of the tax year. (checked November 9, 2026)
If your income from all sources will be greater than $181,440 you have the option to calculate a partial claim. To do so, fill in the appropriate section of Form TD1-WS, Worksheet for the 2026 Personal Tax Credits Return, and enter the calculated amount here. (checked November 9, 2026)
Lines 2 to 12: other amounts you claim
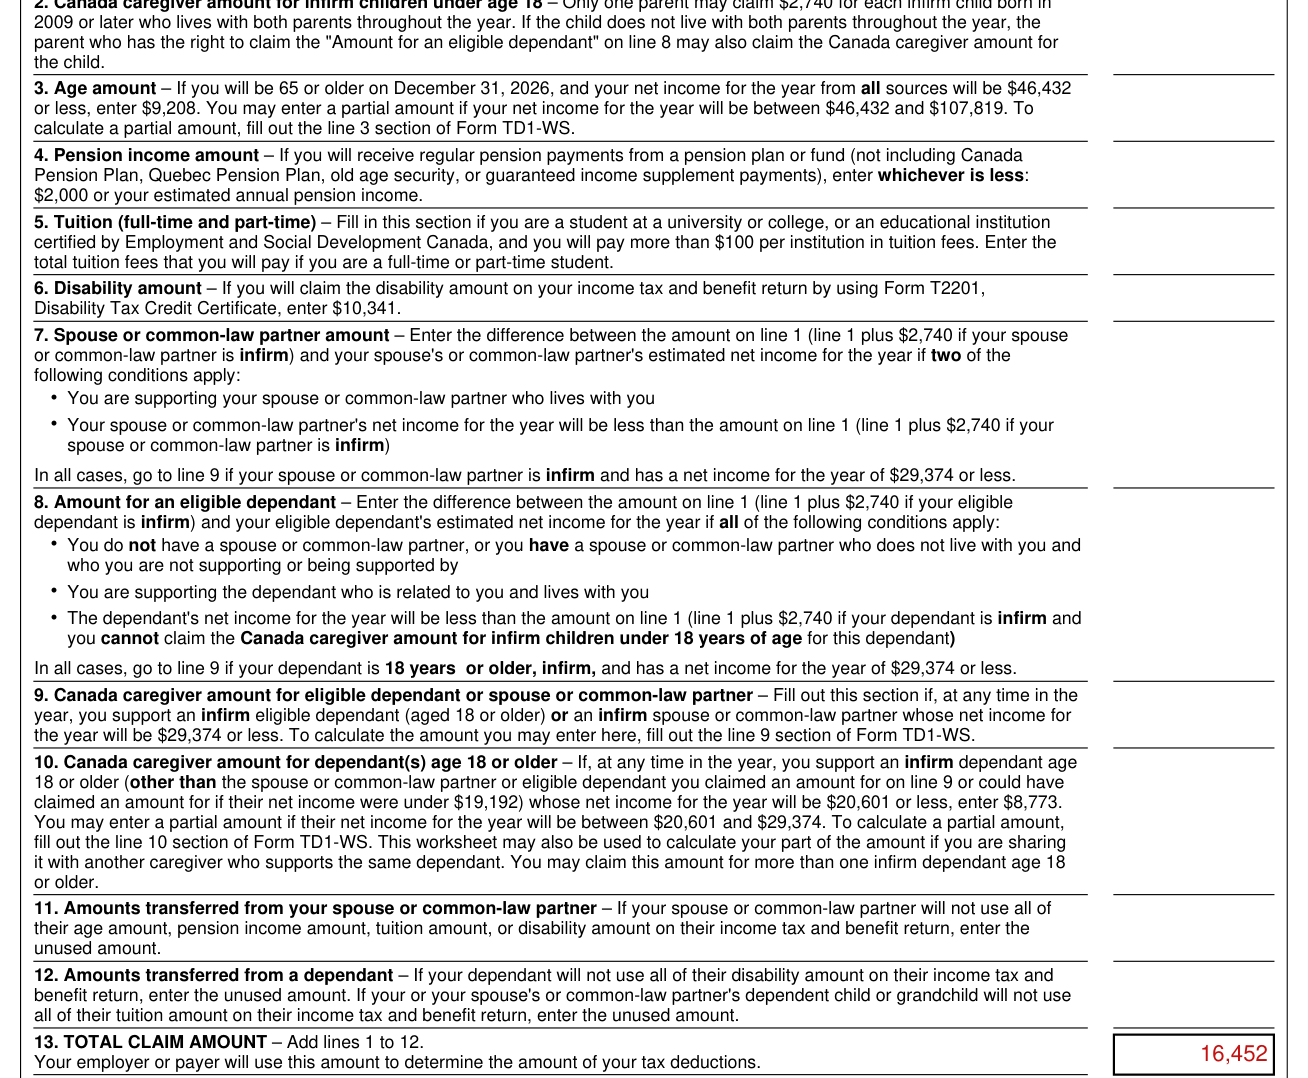
Line 2, Canada caregiver amount for infirm children under age 18: only one parent may claim $2,740 for each infirm child born in 2009 or later who lives with both parents throughout the year. (checked November 9, 2026)
Line 3, Age amount: if you will be 65 or older on December 31, 2026, and your net income for the year from all sources will be $46,432 or less, enter $9,208. (checked November 9, 2026)
Line 4, Pension income amount: if you will receive regular pension payments from a pension plan or fund (not including Canada Pension Plan, Quebec Pension Plan, old age security, or guaranteed income supplement payments), enter whichever is less: $2,000 or your estimated annual pension income. (checked November 9, 2026)
Line 5, Tuition (full-time and part-time): fill in this section if you are a student at a university or college, or an educational institution certified by Employment and Social Development Canada, and you will pay more than $100 per institution in tuition fees. (checked November 9, 2026)
Line 6, Disability amount: if you will claim the disability amount on your income tax and benefit return by using Form T2201, Disability Tax Credit Certificate, enter $10,341. (checked November 9, 2026)
On line 7, Spouse or common-law partner amount, enter the difference between the amount on line 1 (line 1 plus $2,740 if your spouse or common-law partner is infirm) and your spouse's or common-law partner's estimated net income for the year if two of the following conditions apply: You are supporting your spouse or common-law partner who lives with you. Your spouse or common-law partner's net income for the year will be less than the amount on line 1 (line 1 plus $2,740 if your spouse or common-law partner is infirm). (checked November 9, 2026)
Line 11, Amounts transferred from your spouse or common-law partner: if your spouse or common-law partner will not use all of their age amount, pension income amount, tuition amount, or disability amount on their income tax and benefit return, enter the unused amount.
Line 12, Amounts transferred from a dependant: if your dependant will not use all of their disability amount on their income tax and benefit return, enter the unused amount.
13. TOTAL CLAIM AMOUNT

Line 13, TOTAL CLAIM AMOUNT: Add lines 1 to 12.
More than one employer or payer at the same time

If you have more than one employer or payer at the same time and you have already claimed personal tax credit amounts on another Form TD1 for 2026, you cannot claim them again.
If your total income from all sources will be more than the personal tax credits you claimed on another Form TD1, check this box, enter "0" on Line 13 and do not fill in Lines 2 to 12.
Total income is less than the total claim amount

Tick this box if your total income for the year from all employers and payers will be less than your total claim amount on line 13.
Your employer or payer will not deduct tax from your earnings.
For non-resident only

For non-residents only, fill in Country of permanent residence.
For non-resident only (Tick the box that applies to you.) As a non-resident, will 90% or more of your world income be included in determining your taxable income earned in Canada in 2026?
Yes (Fill out the previous page.)
No (Enter "0" on line 13, and do not fill in lines 2 to 12 as you are not entitled to the personal tax credits.)
Call the international tax and non-resident enquiries line at 1-800-959-8281 if you are unsure of your residency status.
Deduction for living in a prescribed zone
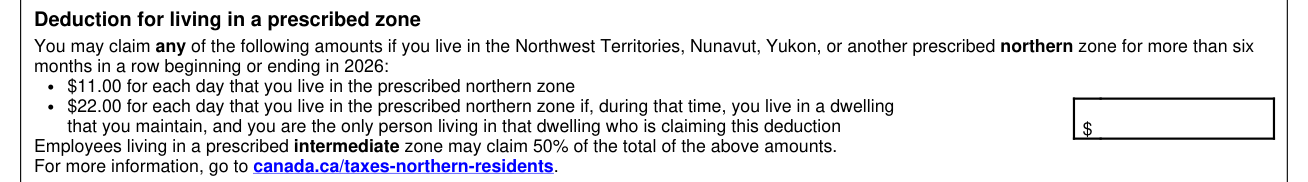
You may claim any of the following amounts if you live in the Northwest Territories, Nunavut, Yukon, or another prescribed northern zone for more than six months in a row beginning or ending in 2026: $11.00 for each day that you live in the prescribed northern zone. (checked November 9, 2026)
$22.00 for each day that you live in the prescribed northern zone if, during that time, you live in a dwelling that you maintain, and you are the only person living in that dwelling who is claiming this deduction. (checked November 9, 2026)
Employees living in a prescribed intermediate zone may claim 50% of the total of the amounts for each day that you live in the prescribed northern zone.
Additional tax to be deducted

You may want to have more tax deducted from each payment if you receive other income such as non-employment income from CPP or QPP benefits, or old age security pension.
Enter the additional tax amount you want deducted from each payment to choose this option.
You may fill out a new Form TD1 to change this deduction later.
Certification
"I certify that the information given on this form is correct and complete."
Enter the Date.
It is a serious offence to make a false return.
More rules for Form TD1
Read page 2 before filling out this form.
Fill out this form based on the best estimate of your circumstances.
If you do not fill out this form, your tax deductions will only include the basic personal amount, estimated by your employer or payer based on the income they pay you.
You also have to fill out a provincial or territorial TD1 form if your claim amount on line 13 is more than $16,452. (checked November 9, 2026)
Use the Form TD1 for your province or territory of employment if you are an employee.
Use the Form TD1 for your province or territory of residence if you are a pensioner.
Your employer or payer will use both this federal form and your most recent provincial or territorial Form TD1 to determine the amount of your tax deductions.
You may ask to have less tax deducted at source if you are eligible for deductions or non-refundable tax credits that are not listed on this form (for example, periodic contributions to a registered retirement savings plan (RRSP), child care or employment expenses, charitable donations, and tuition and education amounts carried forward from the previous year).
To make this request, fill out Form T1213, Request to Reduce Tax Deductions at Source, to get a letter of authority from your tax services office.
Give the letter of authority to your employer or payer.
You do not need a letter of authority if your employer deducts RRSP contributions from your salary.
Common questions about Form TD1
What is TD1 personal tax credits return form?
Form TD1 is the 2026 Personal Tax Credits Return. Your employer or payer will use this form to determine the amount of your tax deductions.
Is there a penalty?
Failure to provide this information may result in paying interest or penalties, or in other actions.
Sources
[1] Form TD1 (2026), Personal Tax Credits Return, Canada Revenue Agency (the Official source link on this page).