

Form H-3 at a glance
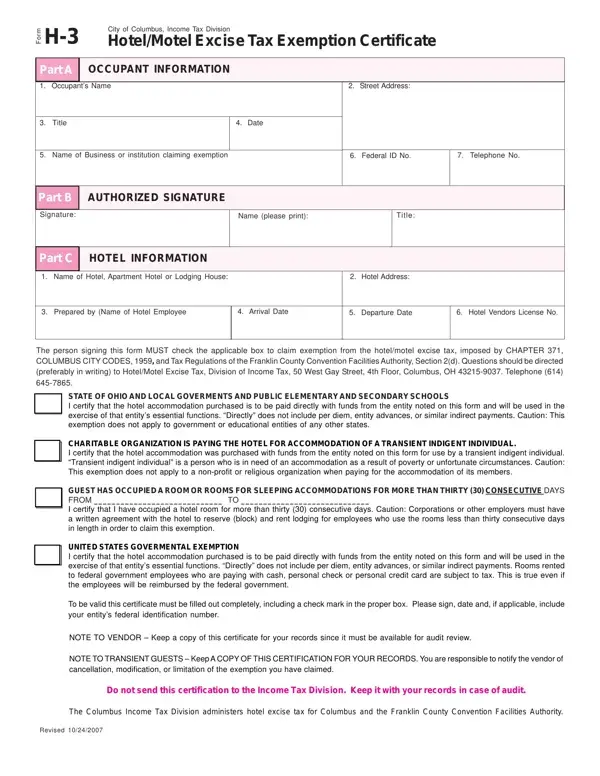
What it is: Hotel/Motel Excise Tax Exemption Certificate H-3, City of Columbus, Income Tax Division: the person signing this form MUST check the applicable box to claim exemption from the hotel/motel excise tax.
Where and when to file: Do not send this certification to the Income Tax Division. Keep it with your records in case of audit.
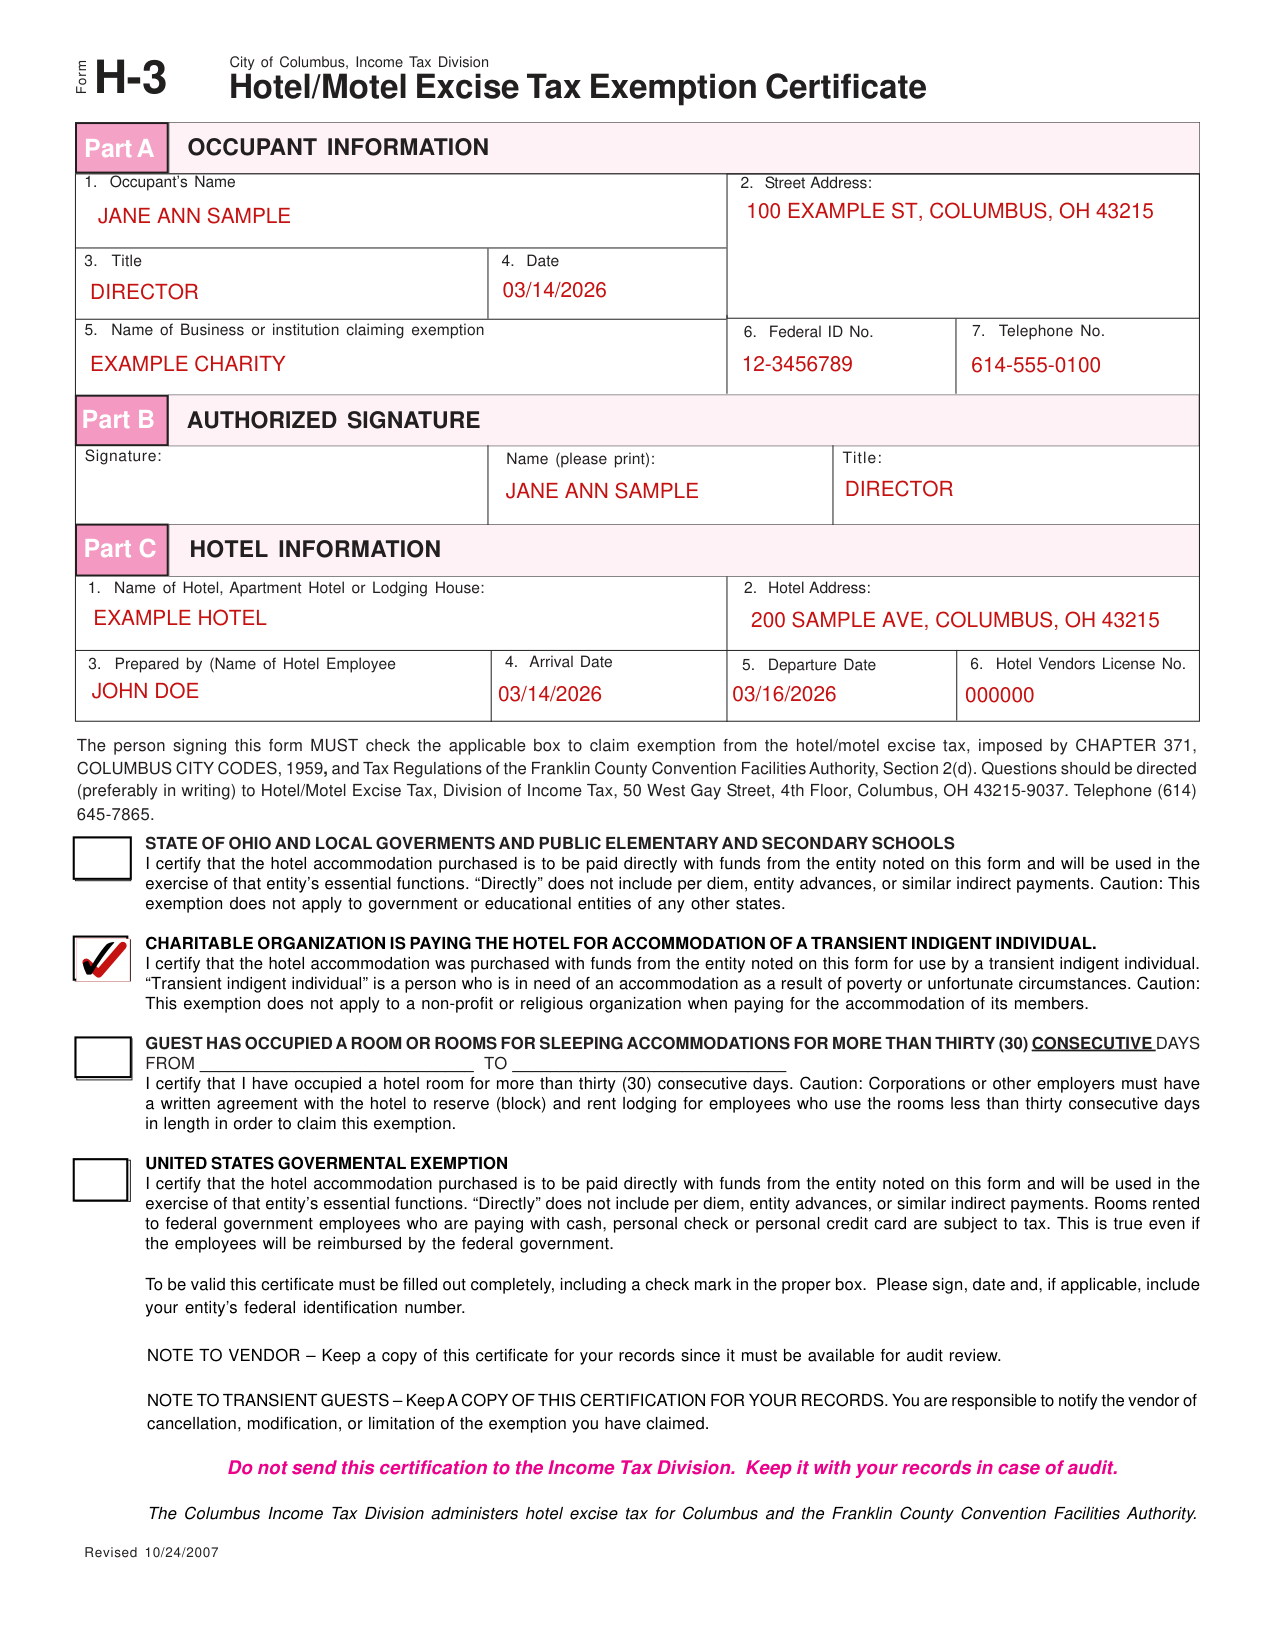
A filled-in Form H-3 example: a charity pays for a guest
How to fill out Form H-3, box by box
Occupant's Name, Title and Federal ID No.
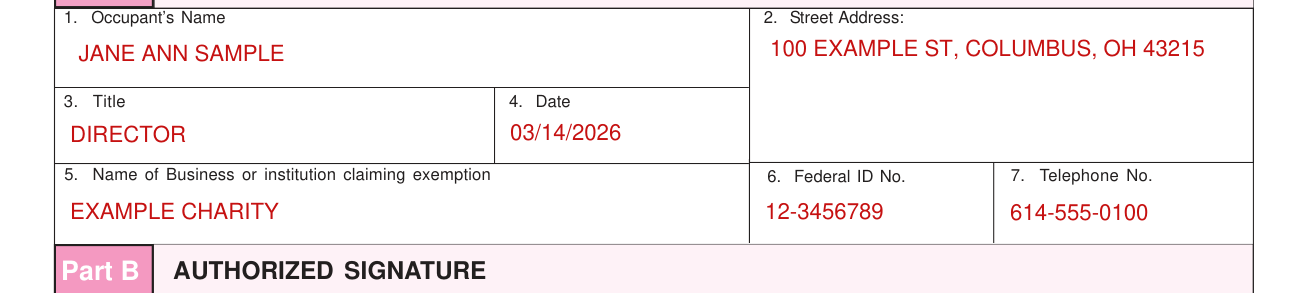
Enter the Occupant's Name in box 1 and the Street Address in box 2.
Enter the Title in box 3 and the Date in box 4.
Enter the Name of Business or institution claiming exemption in box 5.
Enter the Federal ID No. in box 6 and the Telephone No. in box 7.
Signature, Name and Title
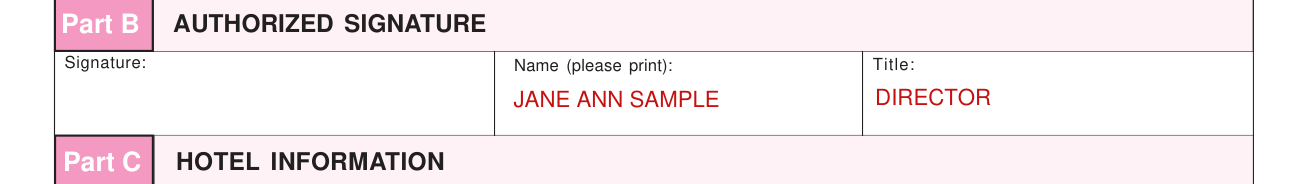
Sign at Signature, then enter Name (please print) and Title.
Name of Hotel, Arrival Date and Departure Date
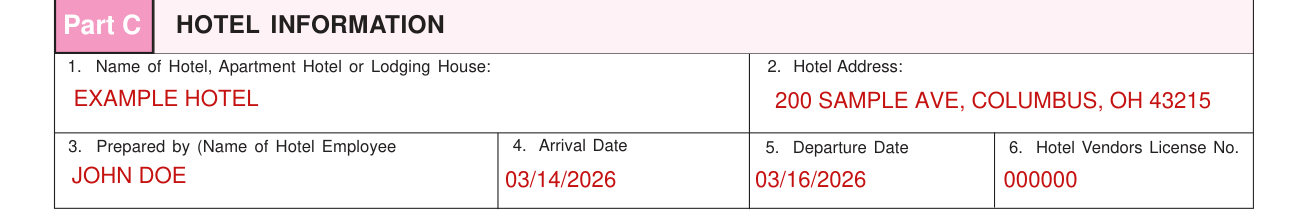
Enter the Name of Hotel, Apartment Hotel or Lodging House in box 1 and the Hotel Address in box 2.
Enter the Name of Hotel Employee who prepared the form in box 3 and the Arrival Date in box 4.
Enter the Departure Date in box 5 and the Hotel Vendors License No. in box 6.
The exemption box to check
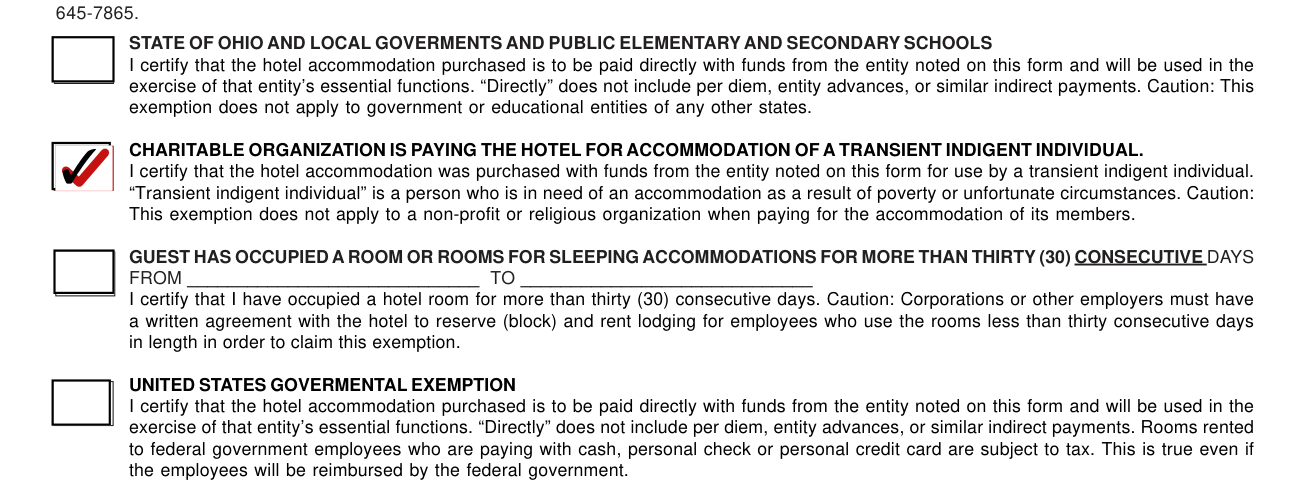
State of Ohio and local governments and public elementary and secondary schools: by signing you certify that the hotel accommodation purchased is to be paid directly with funds from the entity noted on this form and will be used in the exercise of that entity's essential functions. “Directly” does not include per diem, entity advances, or similar indirect payments. Caution: This exemption does not apply to government or educational entities of any other states.
Charitable organization is paying the hotel for accommodation of a transient indigent individual: by signing you certify that the hotel accommodation was purchased with funds from the entity noted on this form for use by a transient indigent individual. “Transient indigent individual” is a person who is in need of an accommodation as a result of poverty or unfortunate circumstances. Caution: This exemption does not apply to a non-profit or religious organization when paying for the accommodation of its members.
Guest has occupied a room or rooms for sleeping accommodations for more than thirty (30) consecutive days FROM to TO: by signing you certify that you have occupied a hotel room for more than thirty (30) consecutive days. Caution: Corporations or other employers must have a written agreement with the hotel to reserve (block) and rent lodging for employees who use the rooms less than thirty consecutive days in length in order to claim this exemption.
United States governmental exemption: by signing you certify that the hotel accommodation purchased is to be paid directly with funds from the entity noted on this form and will be used in the exercise of that entity's essential functions. As in the other exemption, “directly” does not include per diem, entity advances, or similar indirect payments. Rooms rented to federal government employees who are paying with cash, personal check or personal credit card are subject to tax. This is true even if the employees will be reimbursed by the federal government.
More rules for Form H-3
To be valid this certificate must be filled out completely, including a check mark in the proper box. Please sign, date and, if applicable, include your entity's federal identification number.
NOTE TO VENDOR - Keep a copy of this certificate for your records since it must be available for audit review.
Keep a copy of this certification for your records. You are responsible to notify the vendor of cancellation, modification, or limitation of the exemption you have claimed.
Common questions about Form H-3
Where do I file it?
Do not send this certification to the Income Tax Division. Keep it with your records in case of audit.
Where to get help with Form H-3
Questions should be directed (preferably in writing) to Hotel/Motel Excise Tax, Division of Income Tax, 50 West Gay Street, 4th Floor, Columbus, OH 43215-9037. Telephone (614) 645-7865.
Sources
[1] Hotel/Motel Excise Tax Exemption Certificate H-3, City of Columbus, Income Tax Division (revised 10/24/2007) (the Official source link on this page).