

Form 14653 at a glance
What it is: Form 14653 is the Internal Revenue Service certification by a U.S. person residing outside of the United States for the Streamlined Foreign Offshore Procedures.
Who signs: Form 14653 requires the signature of the taxpayer(s) or fiduciary even if this form is signed by a paid preparer (For Paid Preparer Use Only).
A filled-in Form 14653 example: a U.S. citizen living abroad certifies three years
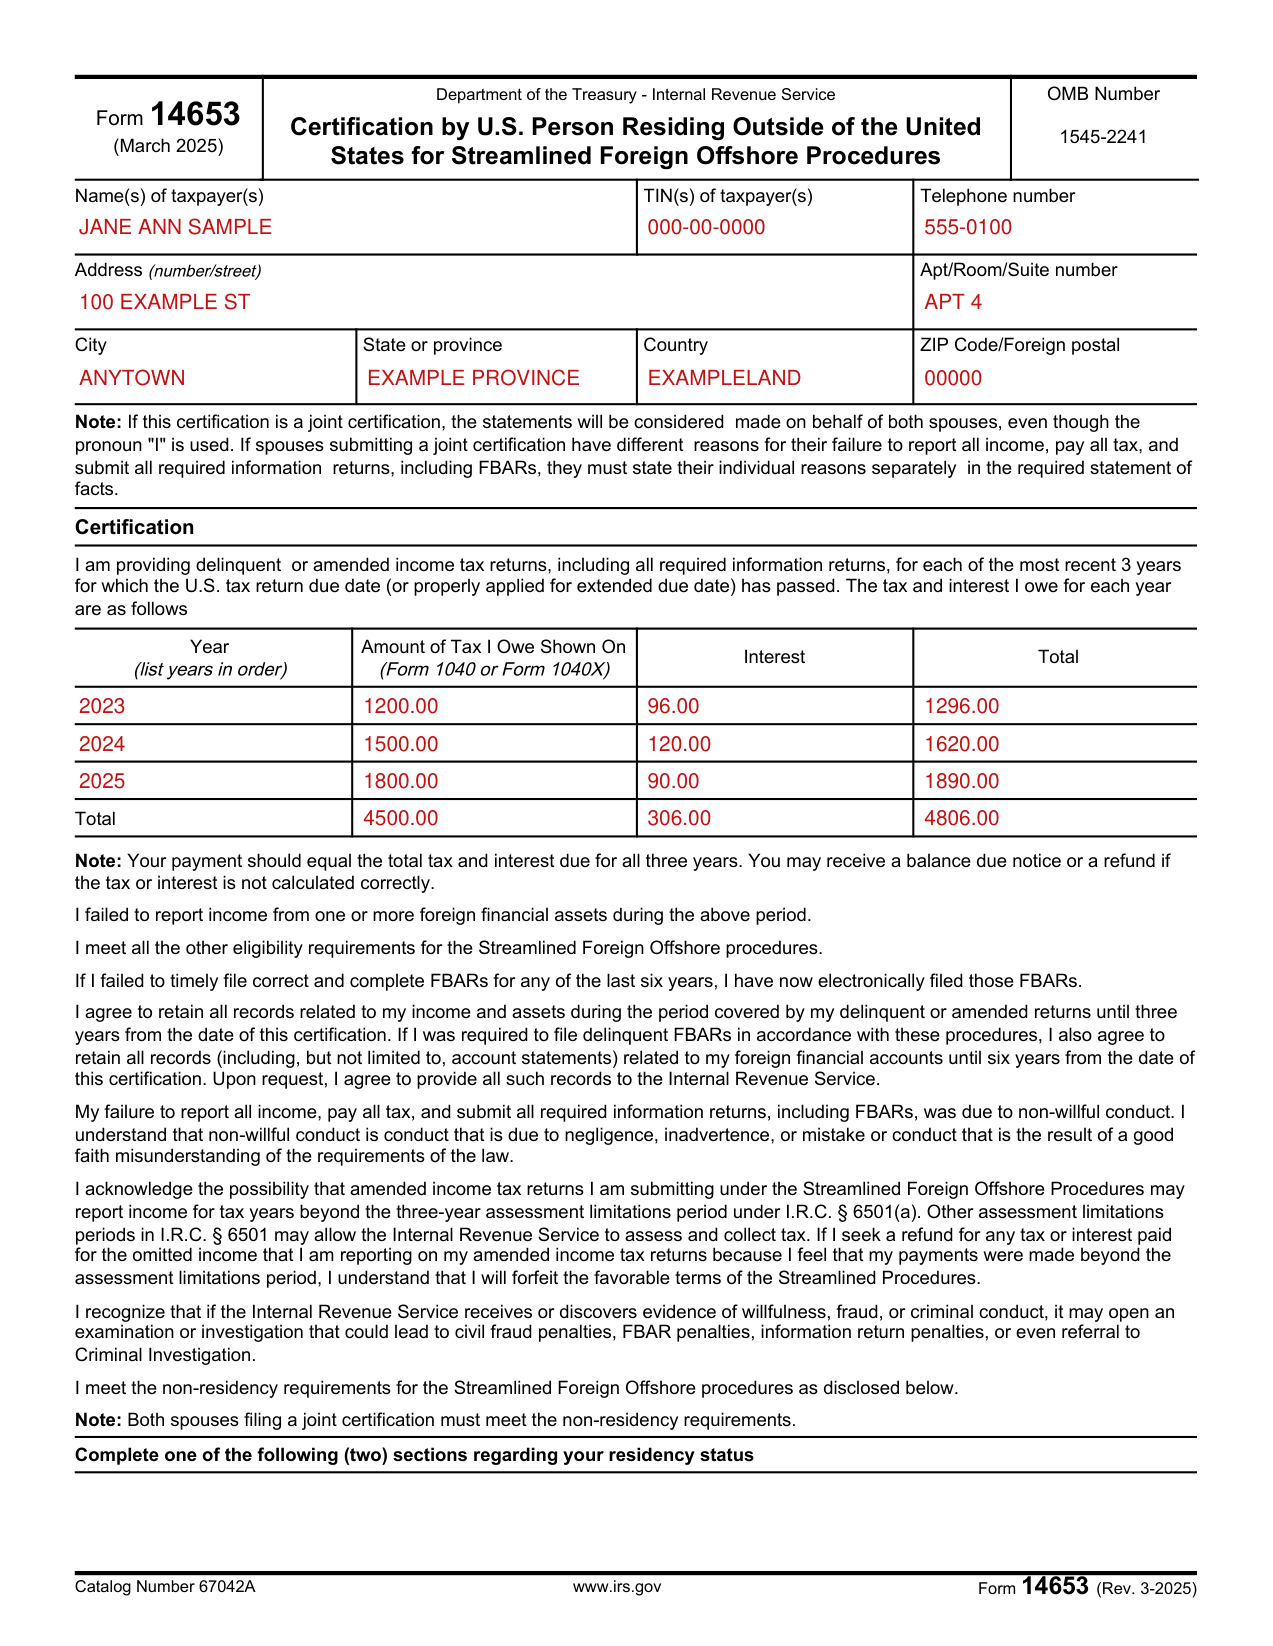
How to fill out Form 14653, box by box
Name(s) of taxpayer(s), TIN(s) and address
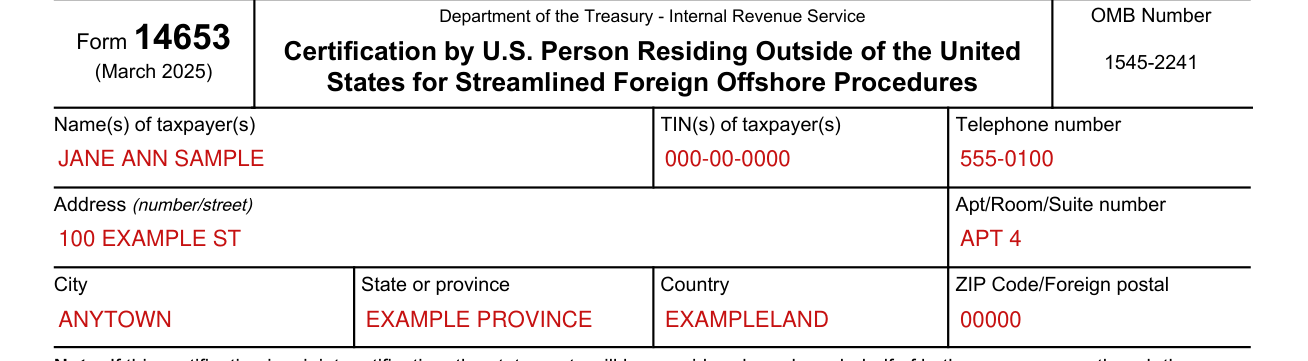
Form 14653 has you enter the Name(s) of taxpayer(s), the TIN(s) of taxpayer(s), the Telephone number, the Address (number/street), the Apt/Room/Suite number, the City, the State or province, the Country and the ZIP Code/Foreign postal.
The terms of the Streamlined Filing Compliance Procedures require a valid Taxpayer Identification Number (TIN).[2]
Certification: the years, the tax and the interest
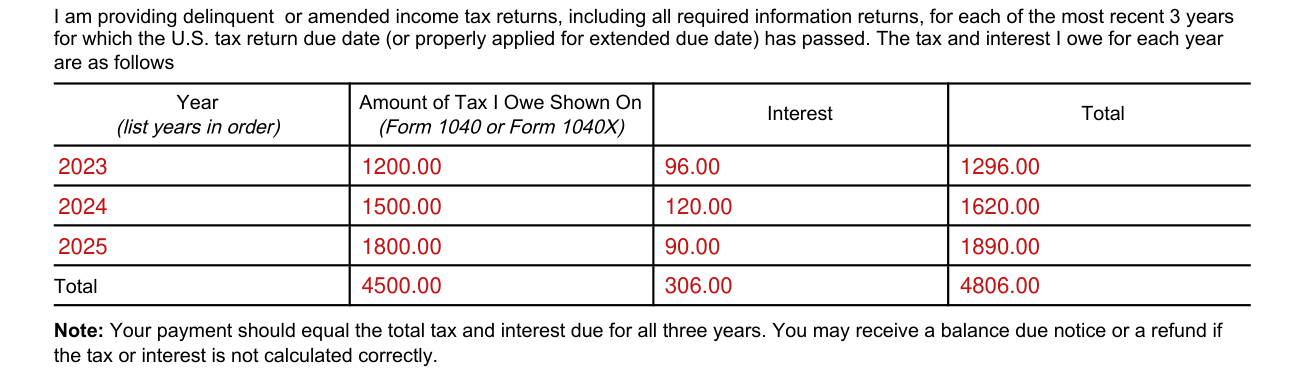
Certification: you are providing delinquent or amended income tax returns, including all required information returns, for each of the most recent 3 years for which the U.S. tax return due date (or properly applied for extended due date) has passed.
For each year, enter the Year (list years in order), the Amount of Tax I Owe Shown On (Form 1040 or Form 1040X), the Interest and the Total. Then enter the Total.
Your payment should equal the total tax and interest due for all three years. You may receive a balance due notice or a refund if the tax or interest is not calculated correctly.
Certification: foreign income, FBARs, refunds and willfulness
You failed to report income from one or more foreign financial assets during the period listed.
If you failed to timely file correct and complete FBARs for any of the last six years, you have now electronically filed those FBARs.
Your failure to report all income, pay all tax, and submit all required information returns, including FBARs, was due to non-willful conduct. You understand that non-willful conduct is conduct that is due to negligence, inadvertence, or mistake or conduct that is the result of a good faith misunderstanding of the requirements of the law.
You acknowledge the possibility that amended income tax returns you are submitting under the Streamlined Foreign Offshore Procedures may report income for tax years beyond the three-year assessment limitations period under I.R.C. § 6501(a). Other assessment limitations periods in I.R.C. § 6501 may allow the Internal Revenue Service to assess and collect tax. If you seek a refund for any tax or interest paid for the omitted income that you are reporting on your amended income tax returns because you feel that your payments were made beyond the assessment limitations period, you understand that you will forfeit the favorable terms of the Streamlined Procedures.
You recognize that if the Internal Revenue Service receives or discovers evidence of willfulness, fraud, or criminal conduct, it may open an examination or investigation that could lead to civil fraud penalties, FBAR penalties, information return penalties, or even referral to Criminal Investigation.
Residency status: U.S. citizen or lawful permanent resident, the 330 days chart
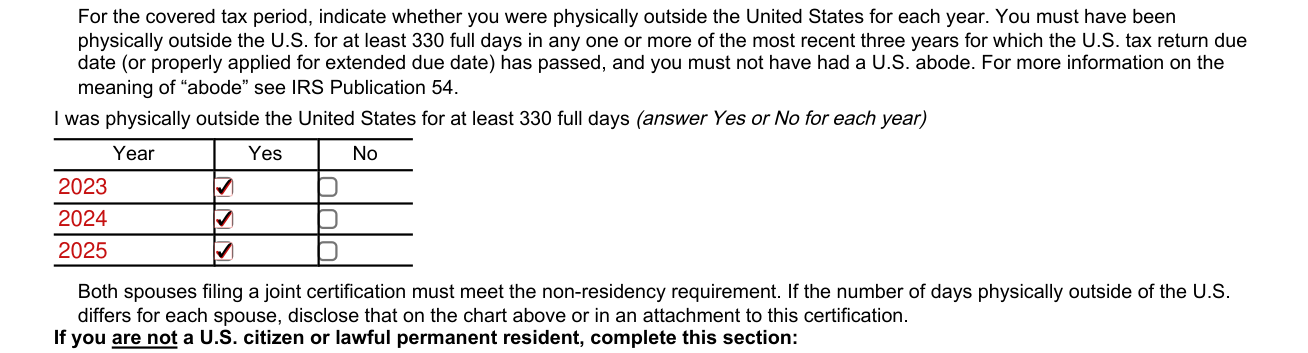
Form 14653 has you complete one of the following (two) sections regarding your residency status. You meet the non-residency requirements for the Streamlined Foreign Offshore procedures as disclosed in the section you complete.
If you are a U.S. citizen or lawful permanent resident (i.e., “green card holder”), complete this section. For the covered tax period, indicate whether you were physically outside the United States for each year.
You must have been physically outside the U.S. for at least 330 full days in any one or more of the most recent three years for which the U.S. tax return due date (or properly applied for extended due date) has passed, and you must not have had a U.S. abode. For more information on the meaning of “abode” see IRS Publication 54.
Answer Yes or No for each Year: you were physically outside the United States for at least 330 full days.
If the number of days physically outside of the U.S. differs for each spouse, disclose that on the chart or in an attachment to this certification.
Not a U.S. citizen or lawful permanent resident: the computation
If you are not a U.S. citizen or lawful permanent resident, complete this section. Attach to this certification your computation showing that you did not meet the substantial presence test under I.R.C. sec. 7701(b)(3).
Your computation must disclose the number of days you were present in the U.S. for the three years included in your Streamlined Foreign Offshore Procedures submission and the previous two years.
Common mistake: If you do not attach a complete computation showing that you did not meet the substantial presence test, your submission will be considered incomplete and your submission will not qualify for the Streamlined Foreign Offshore Procedures.
If the number of days inside the U.S. differs for each spouse, disclose that in an attachment to this certification.
Statement of facts
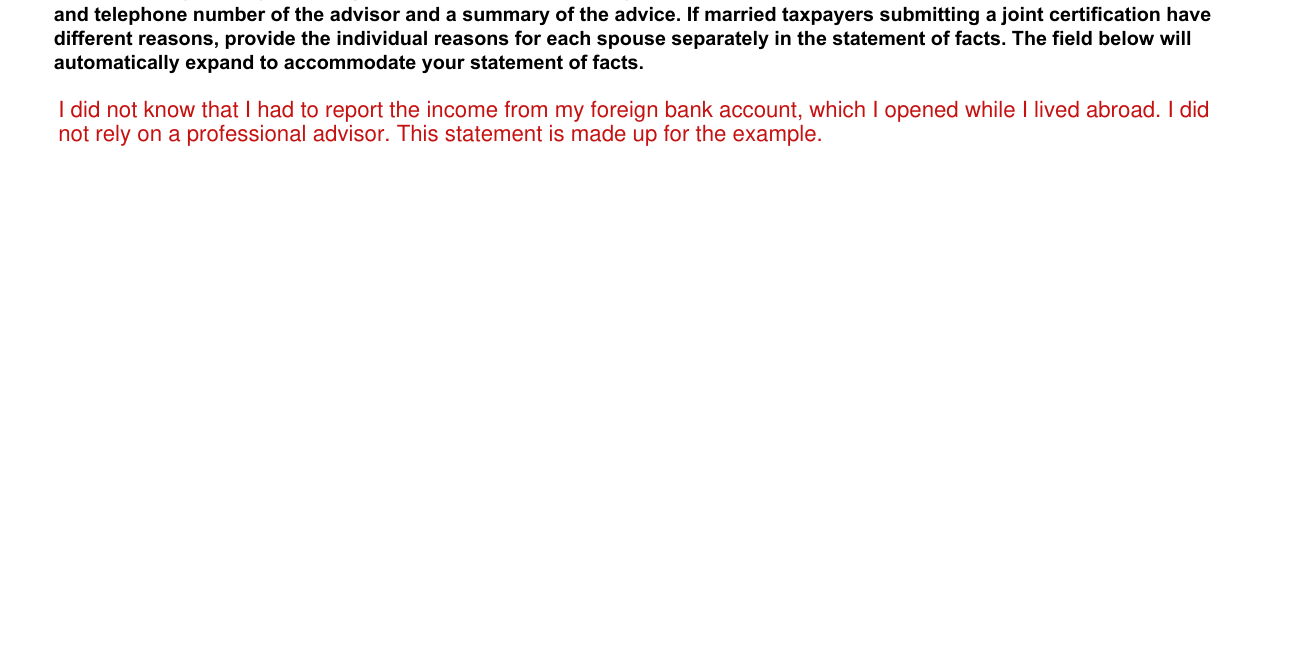
Common mistake: Form 14653 requires you to provide specific facts on this form or on a signed attachment explaining your failure to report all income, pay all tax, and submit all required information returns, including FBARs. Any submission that does not contain a narrative statement of facts will be considered incomplete and will not qualify for the streamlined penalty relief.
Provide specific reasons, whether favorable or unfavorable to you, which should include your personal background, financial background, and anything else you believe is relevant. Include the whole story including favorable and unfavorable facts.
Explain the source of funds in all of your foreign financial accounts/assets. For example, explain whether you inherited the account/asset, whether you opened it while residing in a foreign country, or whether you had a business reason to open or use it. And explain your contacts with the account/asset including withdrawals, deposits, and investment/management decisions. Provide a complete story about your foreign financial account/asset.
If you relied on a professional advisor, provide the name, address, and telephone number of the advisor and a summary of the advice.
The field automatically expands to accommodate your statement of facts.
Signing the certification
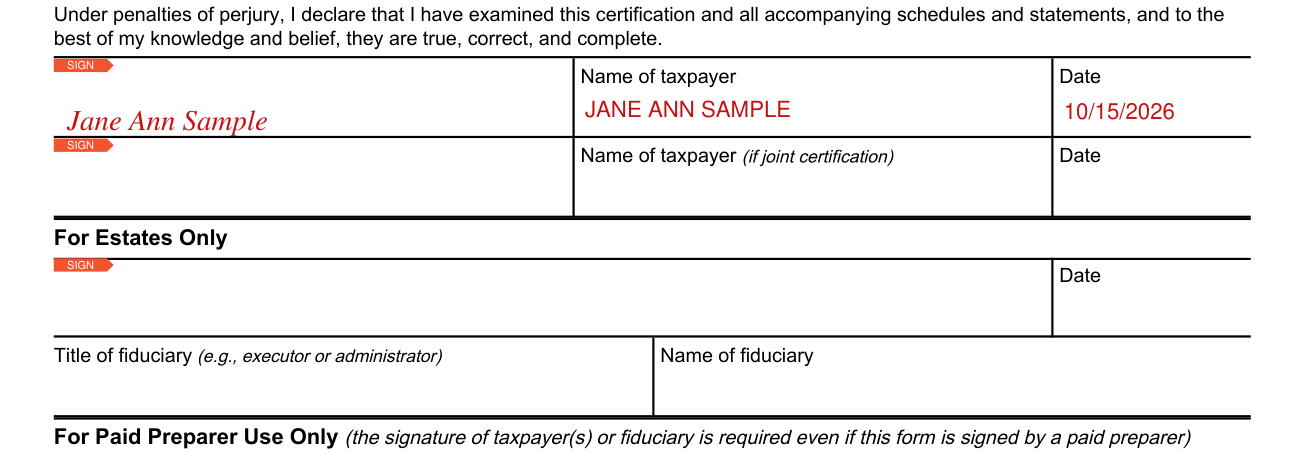
Form 14653 is signed under penalties of perjury: you declare that you have examined this certification and all accompanying schedules and statements, and to the best of your knowledge and belief, they are true, correct, and complete.
Sign, and enter the Name of taxpayer and the Date.
Sign, and enter the Name of taxpayer (if joint certification) and the Date.
For Estates Only: sign, and enter the Date, the Title of fiduciary (e.g., executor or administrator) and the Name of fiduciary.
For Paid Preparer Use Only
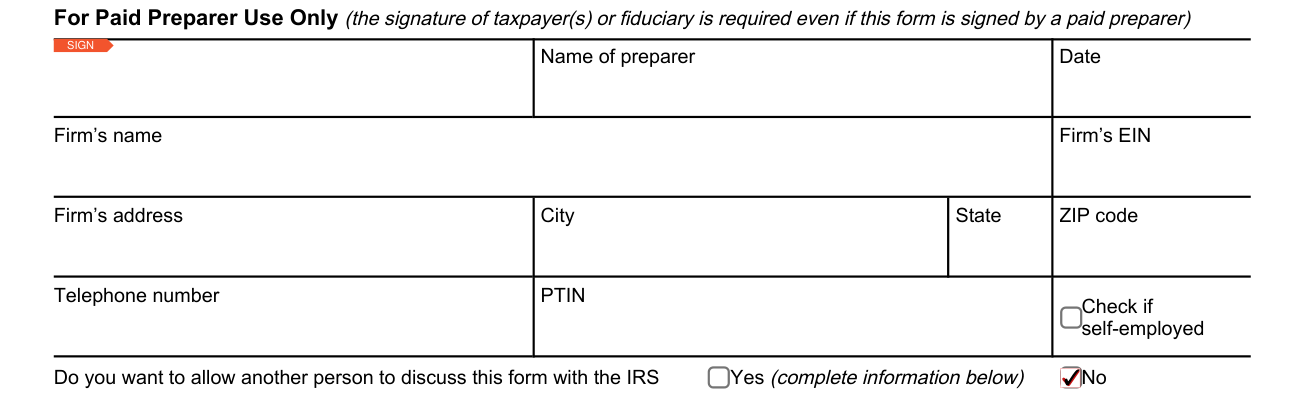
Common mistake: For Paid Preparer Use Only (the signature of taxpayer(s) or fiduciary is required even if this form is signed by a paid preparer): sign, and enter the Name of preparer, the Date, the Firm's name, the Firm's EIN, the Firm's address, the City, the State, the ZIP code, the Telephone number and the PTIN. Check if self-employed.
Allow another person to discuss this form with the IRS
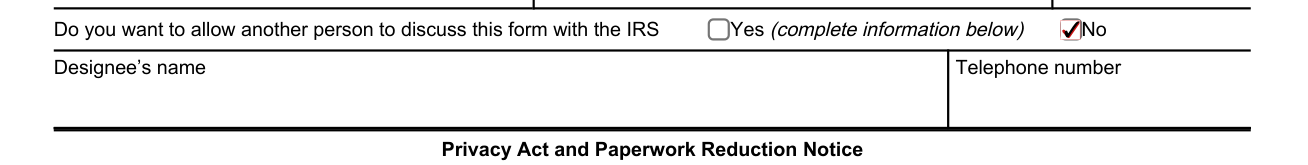
Do you want to allow another person to discuss this form with the IRS? Check No or Yes (complete information). If Yes, enter the Designee's name and Telephone number.
More rules for Form 14653
This information will be used to determine and collect the correct amount of tax under the terms of the streamlined filing compliance program.
You are not required to apply for participation in the streamlined filing compliance program. If you choose to apply, however, you are required to provide all the information requested on the streamlined certification.
Failure to provide the information may delay or prevent processing your application.
Joint certifications and an error in the original submission
Spouses submitting a joint certification
If this certification is a joint certification, the statements will be considered made on behalf of both spouses, even though the pronoun “I” is used. If married taxpayers submitting a joint certification have different reasons for their failure to report all income, pay all tax, and submit all required information returns, including FBARs, they must provide the individual reasons for each spouse separately in the required statement of facts.
Both spouses filing a joint certification must meet the non-residency requirements.
An error in the original Streamlined submission
Explain all facts and circumstances concerning the error in the original Streamlined submission. See SFO FAQ 6 for relevant information to provide. Mail the amended submission to: IRS 3651 S. IH 35 MS 6063 AUSC Attn.: Streamlined Procedures Austin, TX 78741[2]
Common questions about Form 14653
Is there a penalty?
Providing false information may subject you to penalties.
Sources
[1] Form 14653 (Rev. 3-2025), Certification by U.S. Person Residing Outside of the United States for Streamlined Foreign Offshore Procedures, Internal Revenue Service (the Official source link on this page).
[2] irs.gov, line_tin_of_taxpayers_doc_valid_tin_required (irs.gov). Accessed October 18, 2026.
