

Form 4626 at a glance
What it is: Form 4626, Alternative Minimum Tax-Corporations, is used to determine whether a corporation is an applicable corporation under section 59(k) and to calculate CAMT under section 55 for applicable corporations.[2]
Where and when to file: Attach to your tax return. Go to www.irs.gov/Form4626 for instructions and the latest information.
Unless a filing exclusion applies, a corporation must file Form 4626 to determine whether it is an applicable corporation and, if it is classified as an applicable corporation, to calculate CAMT.[2]
A filled-in Form 4626 example: a corporation that skips Part I
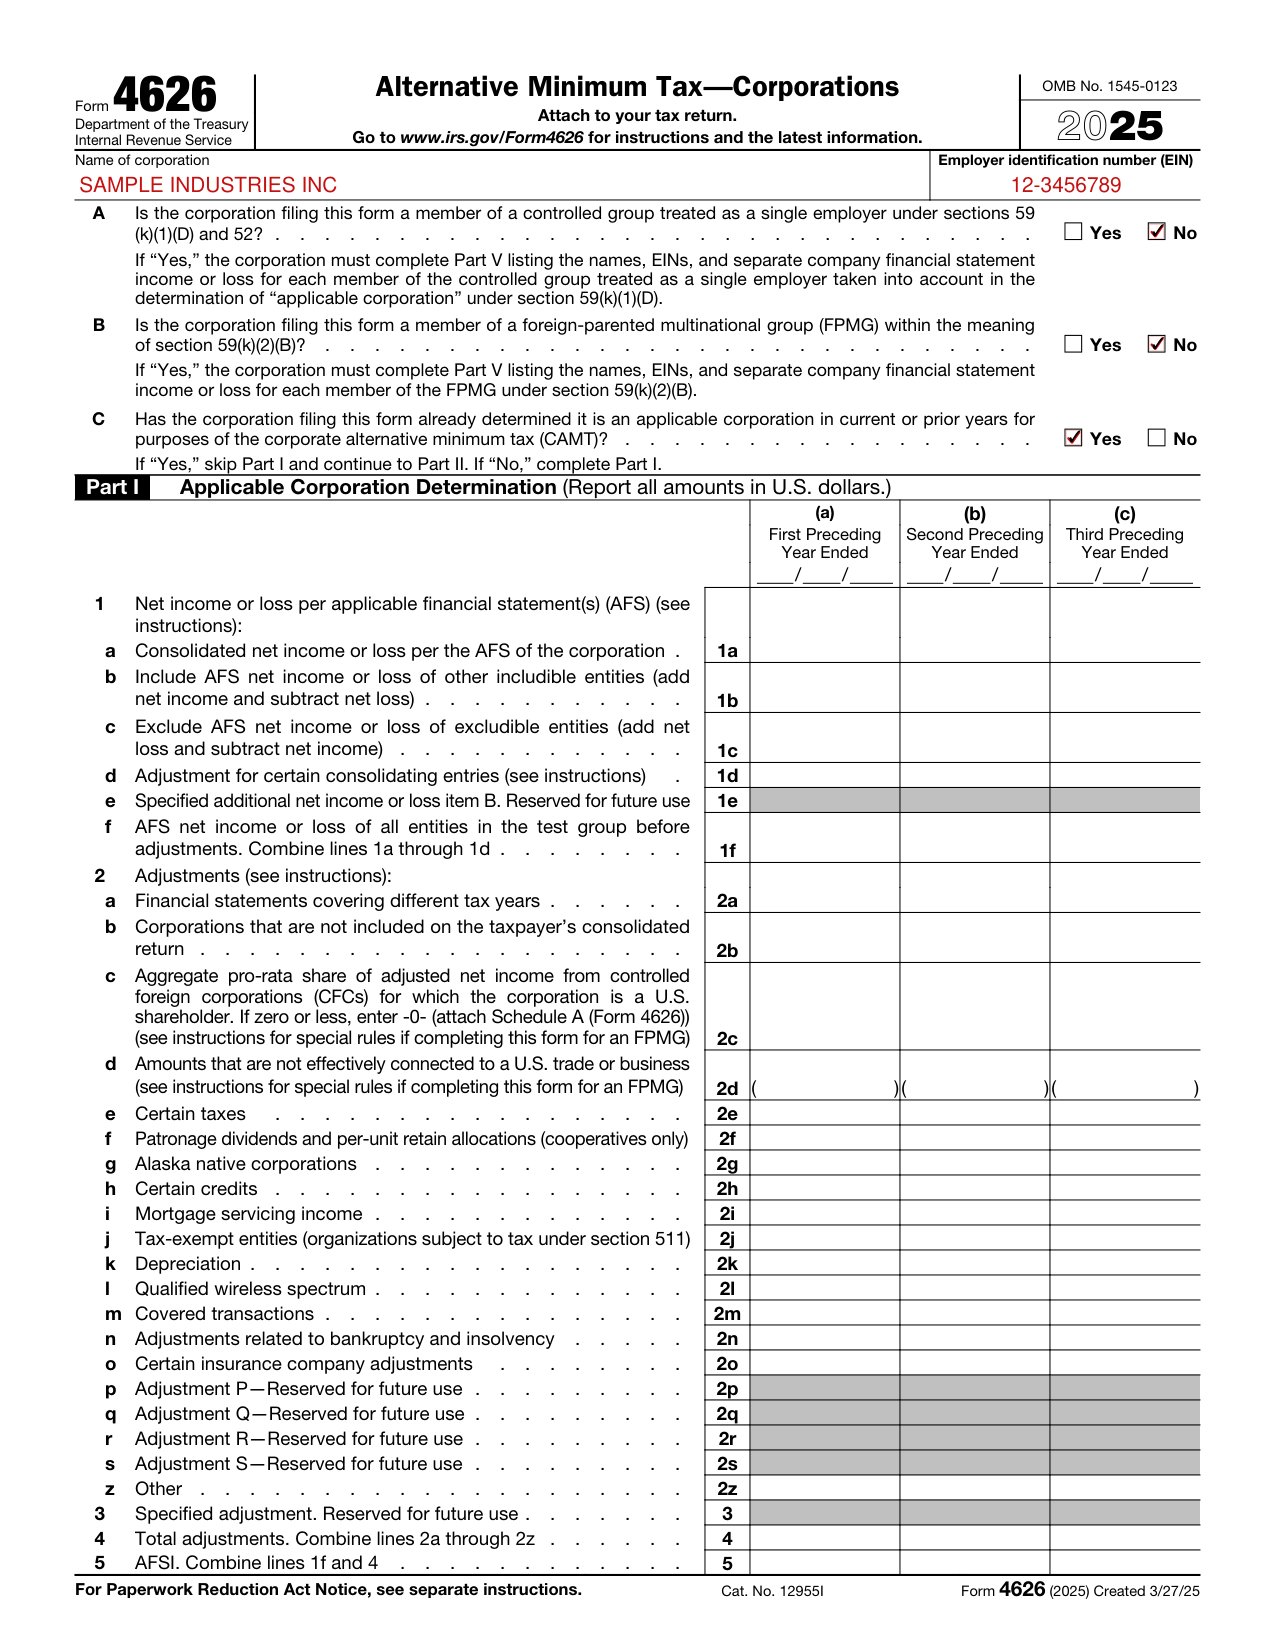
How to fill out Form 4626, box by box
Items A, B and C
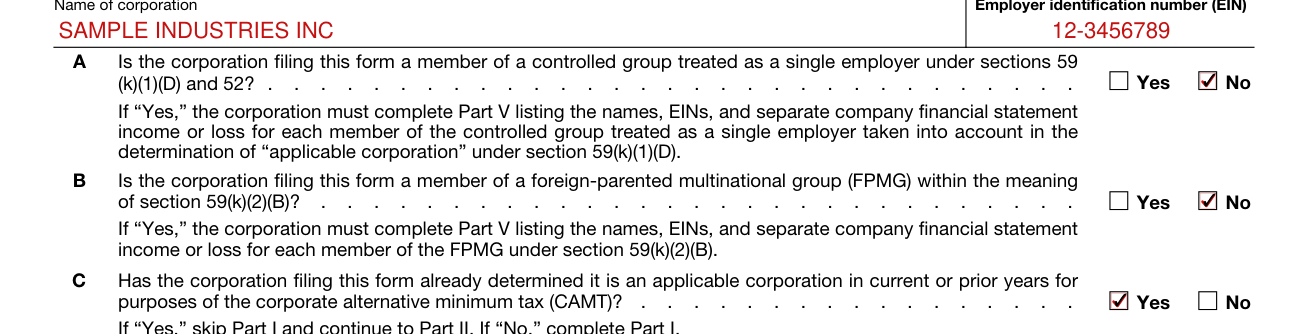
In Item A, check Yes if the corporation filing this form is a member of a controlled group treated as a single employer under sections 59(k)(1)(D) and 52, and also complete Part V. If Yes, the corporation must complete Part V listing the names, EINs, and separate company financial statement income or loss for each member of the controlled group treated as a single employer.
In Item B, check Yes or No. Check Yes if the corporation is a member of a foreign-parented multinational group (FPMG) within the meaning of section 59(k)(2)(B), and also complete Part V. If Yes, the corporation must complete Part V listing the names, EINs, and separate company financial statement income or loss for each member of the FPMG under section 59(k)(2)(B).
If the corporation is a member of an FPMG, also attach a statement described under Proposed Regulations section 1.59-3(g)(4) disclosing the applicable financial accounting standard used to determine if a corporation is a member of an FPMG.
In Item C, check Yes if the corporation has already determined it is an applicable corporation for purposes of the CAMT, skip Part I, and continue to Part II. Otherwise, check No and complete Part I to determine if the corporation is an applicable corporation.[2]
Part I lines 7, 8, 9 and 16
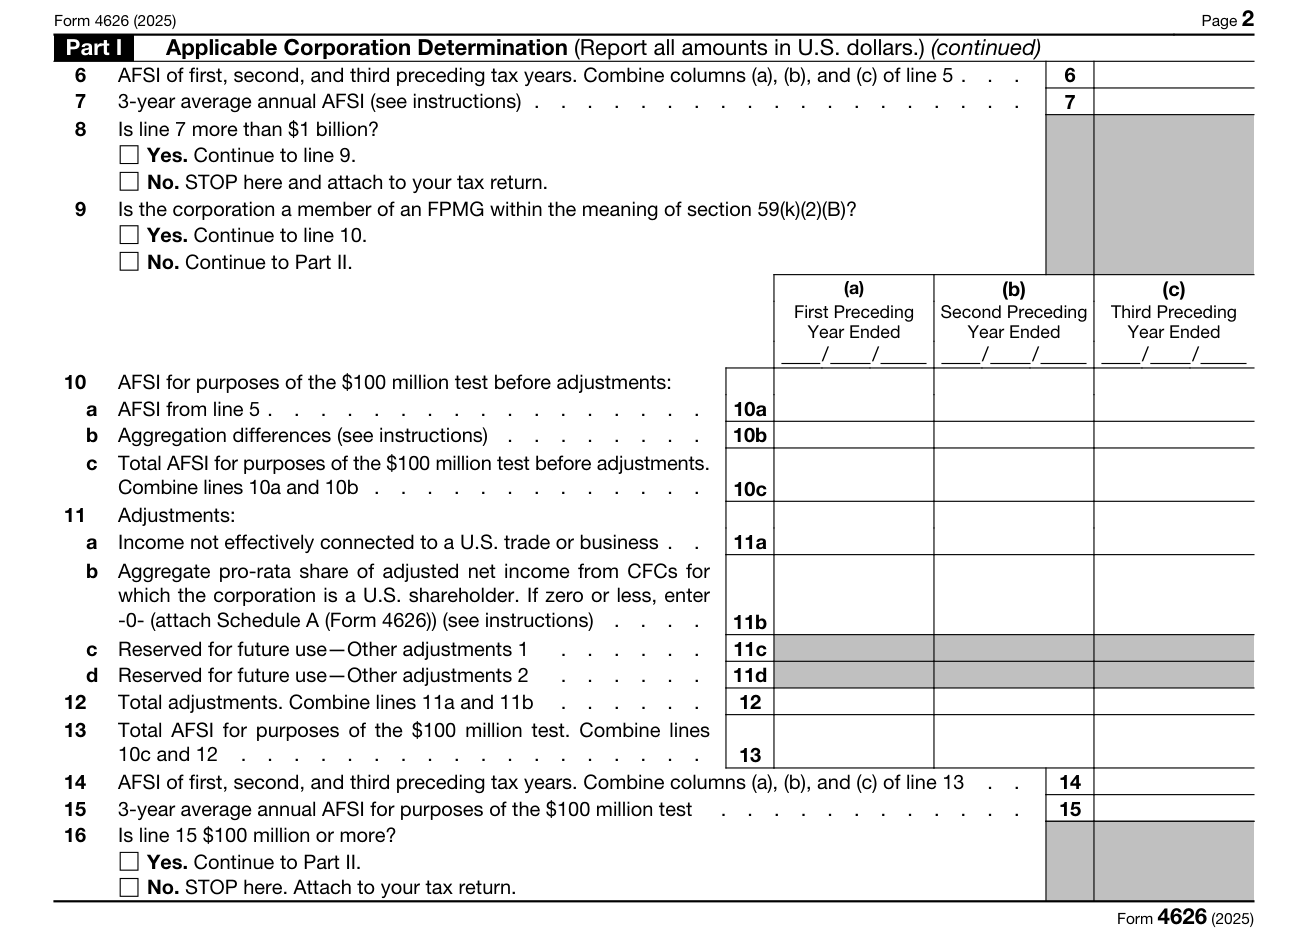
On line 7, calculate the 3-year average annual AFSI by dividing the amount on line 6 by the number of tax years included on line 6, using the period during which the corporation existed.
If line 7 exceeds $1 billion, check Yes on line 8 and continue to line 9; if No, stop here and attach to your tax return (checked November 8, 2026).
On line 9, check Yes if the corporation is a member of an FPMG within the meaning of section 59(k)(2)(B) and continue to line 10; if No, continue to Part II.
On line 16, check Yes if line 15 is $100 million or more and continue to Part II; if No, stop here and attach to your tax return (checked November 8, 2026).[2]
Part II Corporate Alternative Minimum Tax (CAMT)
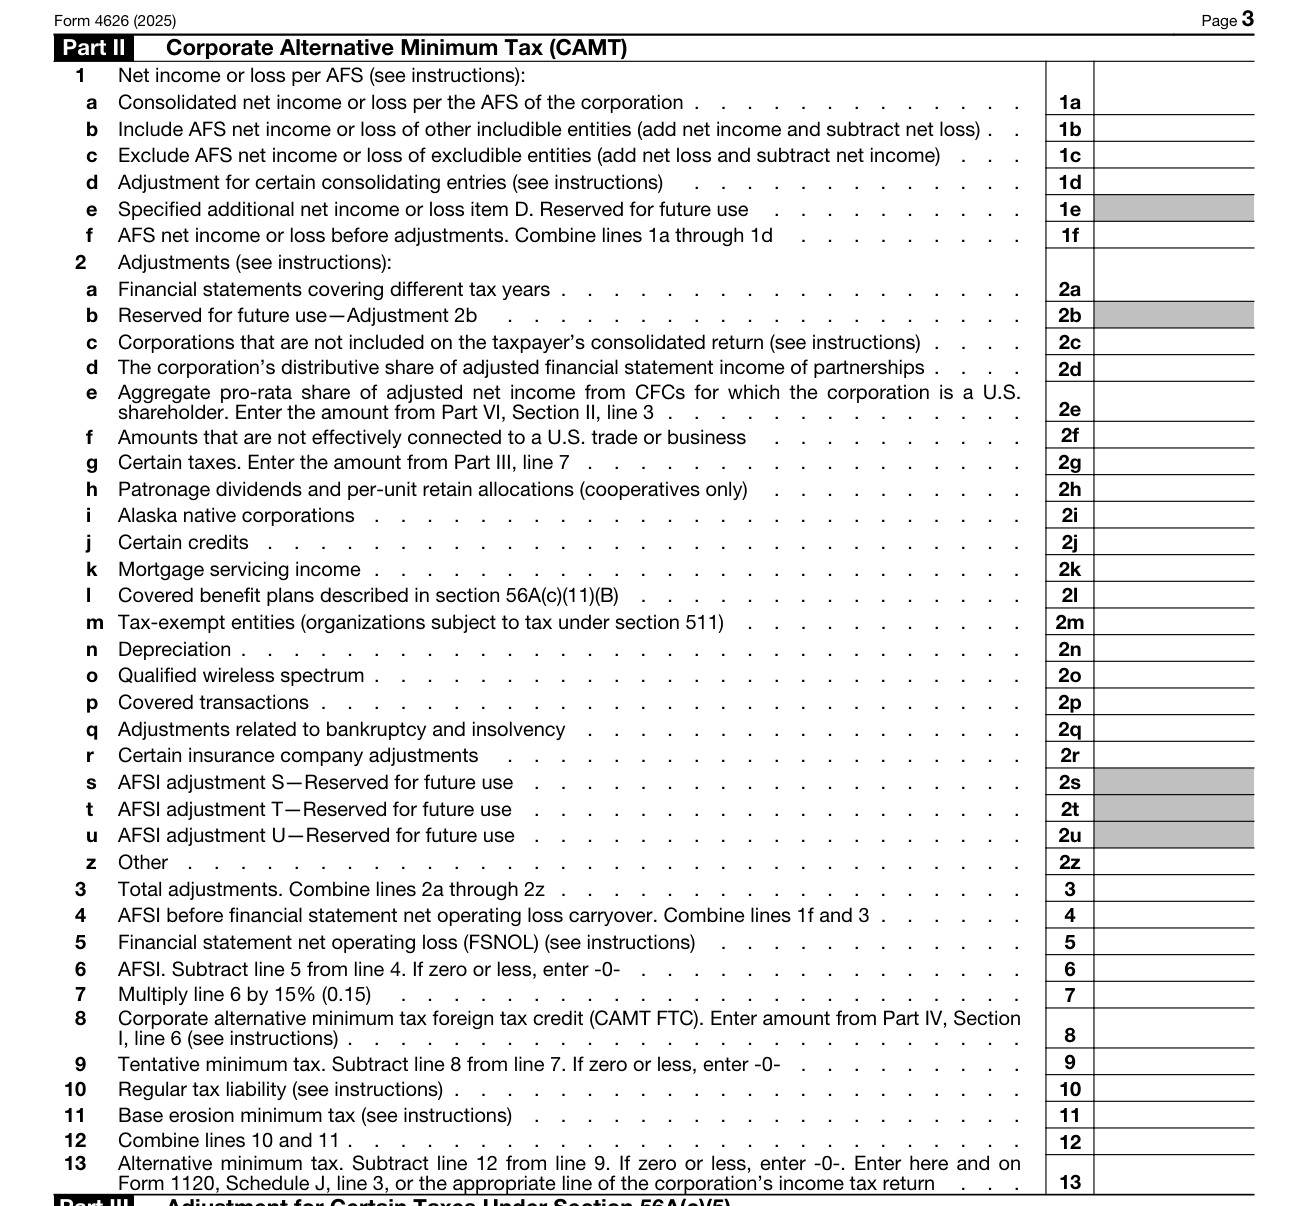
On line 1f, enter the AFS net income or loss before adjustments by combining lines 1a through 1d.
On line 4, enter the AFSI before financial statement net operating loss carryover by combining lines 1f and 3.
On line 6, enter AFSI by subtracting line 5 from line 4; if zero or less, enter -0-.
On line 7, multiply line 6 by 15% (0.15).
After line 7, on line 8, enter the amount from Part IV, Section I, line 6 as the corporate alternative minimum tax foreign tax credit (CAMT FTC).
On line 9, enter the tentative minimum tax by subtracting line 8 from line 7; if zero or less, enter -0-.
On line 12, combine lines 10 and 11.
On line 13, enter the alternative minimum tax by subtracting line 12 from line 9; if zero or less, enter -0-, and enter it here and on Form 1120, Schedule J, line 3, or the appropriate line of the corporation's income tax return.
If your situation is different
When To File
Attach Form 4626 to the corporation's income tax return (or, if applicable, exempt organization business income tax return) and file by the due date (including extensions) for that return.[2]
Filing exclusions
A corporation is not required to file Form 4626 if the corporation is an S corporation, a regulated investment company (RIC), a real estate investment trust (REIT), a tax-exempt entity that is not required to file an exempt organization business income tax return because it has no unrelated business taxable income (even if such entity is a member of a controlled group treated as a single employer under sections 59(k)(1)(D) and 52(a) or (b)) or a corporation that is not required to file Form 4626 because it is not an applicable corporation under the interim simplified method or simplified method and chooses to apply that method. This filing exception does not apply if the corporation is an applicable corporation in the current tax year because the corporation was an applicable corporation in a prior tax year.[2]
Sources
[1] Form 4626 (2025), Alternative Minimum Tax-Corporations, Internal Revenue Service (the Official source link on this page).
[2] 2025 Instructions for Form 4626, Alternative Minimum Tax-Corporations, Internal Revenue Service.