
Form 592-B at a glance
What it is: California Form 592-B is the Resident and Nonresident Withholding Tax Statement for taxable year 2025.
Tax deadline: Form 592-B must be completed and provided to each payee by January 31st following the close of the calendar year for residents or nonresidents.
Form 592-B must be completed by the withholding agent, including any person or entity who has withheld on payments to residents or nonresidents, who has withheld backup withholding on payments to residents or nonresidents, or who was withheld upon and must pass through the withholding credit to their pass-through entity owners.
Use Form 592-B to report to the payee the amount of payment or distribution subject to withholding and tax withheld.
Complete a separate Form 592-B for each payee.
A filled-in Form 592-B example: a freelancer paid 12,000 for design work
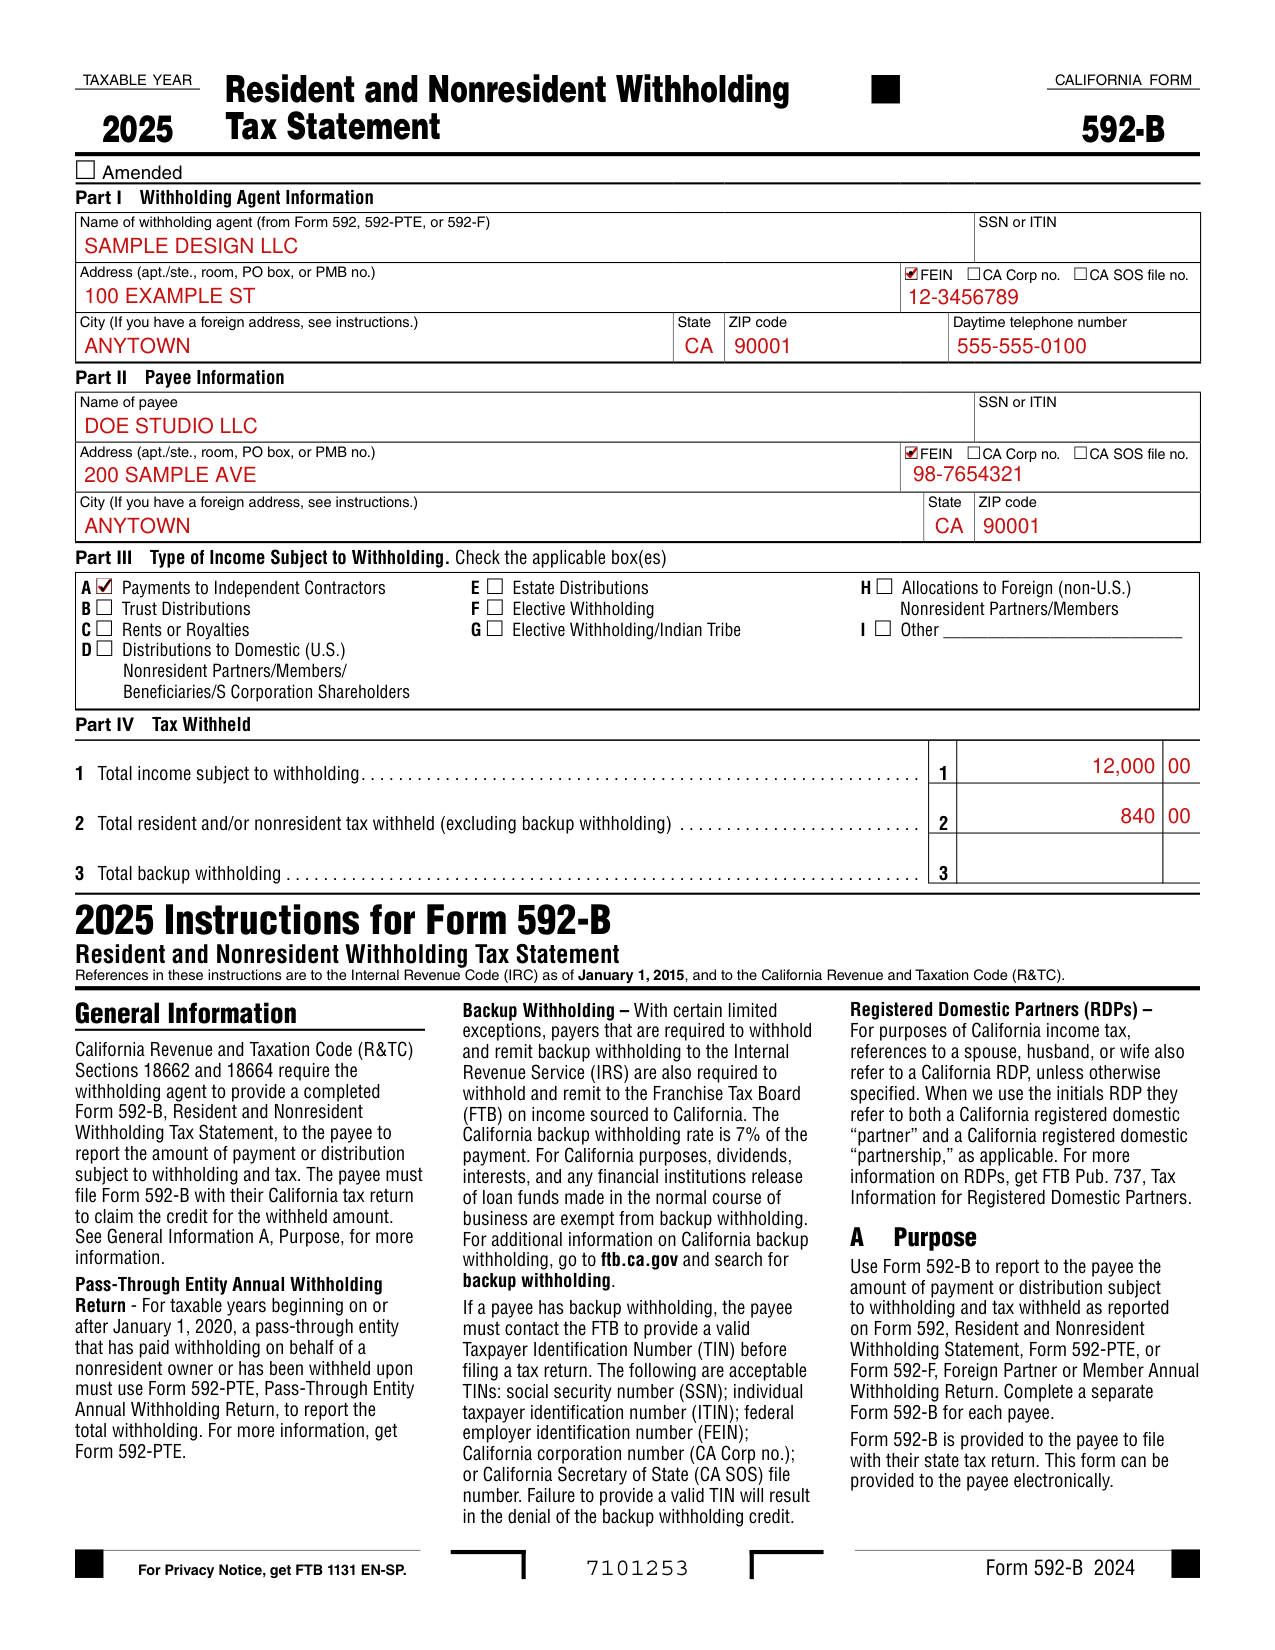
How to fill out Form 592-B, box by box
Amended

Check the Amended box at the top left corner of the form.
Part 1. Withholding Agent Information
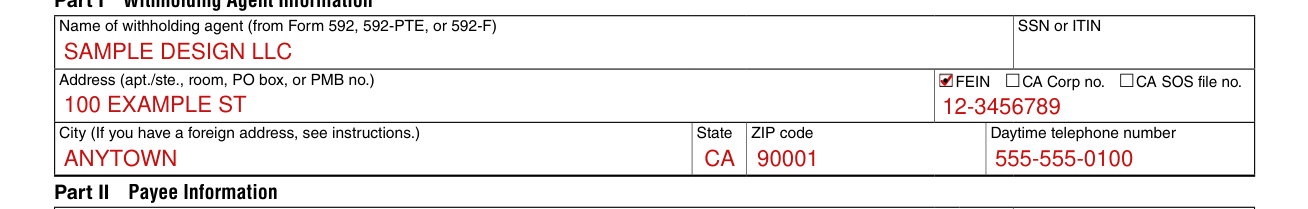
In Part 1, enter the withholding agent's name, TIN, address, and telephone number.
Include the PMB in the address field and write “PMB” first, then the box number.
For a foreign address, follow the country's practice for entering the city, county, province, state, country, and postal code, as applicable, in the appropriate boxes.
For a foreign address, do not abbreviate the country name.
Part 2. Payee Information
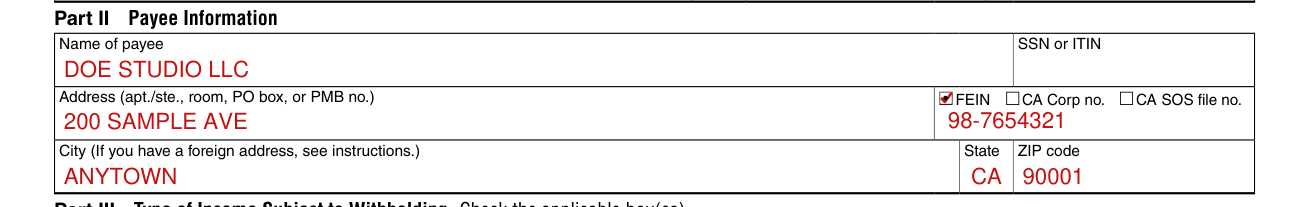
In Part 2, enter the payee's name, TIN, and address.
Get taxpayer identification numbers (TINs) from all payees.
The following are acceptable TINs: SSN, ITIN, FEIN, CA Corp no., or CA SOS file number.
Part 3. Type of Income Subject to Withholding
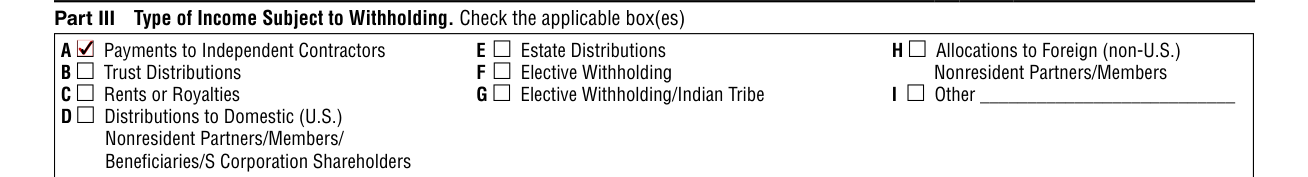
In Part 3, check the box(es) for the type of income subject to withholding.
Part 4. Tax Withheld
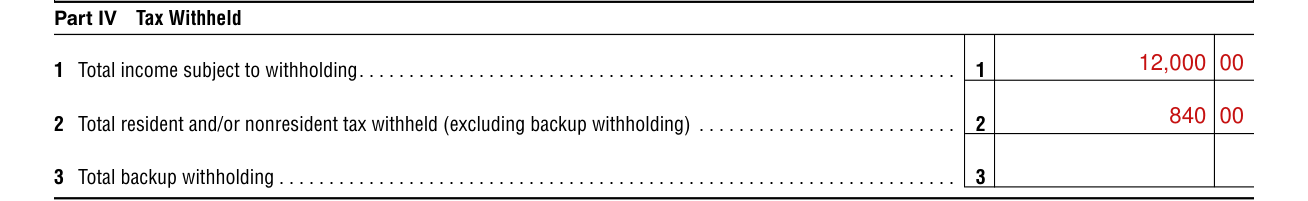
In Part 4, on line 1, enter the total income subject to withholding.
On line 2, enter the total resident and/or nonresident tax withheld (excluding backup withholding).
The amount of tax to be withheld is computed by applying a rate of 7% on items of income subject to withholding.
For foreign partners, the rate is 8.84% for corporations, 10.84% for banks and financial institutions, and 12.3% for all others.
For pass-through entities, the amount withheld is allocated to partners, members, S corporation shareholders, or beneficiaries, whether they are residents or nonresidents of California, in proportion to their ownership or beneficial interest.
On line 3, enter the total backup withholding, if applicable.
More rules for Form 592-B
The withholding agent retains the proof of withholding for a minimum of five years and must provide it to the FTB upon request.
For the withholding agent, the year at the top left corner of Form 592-B represents the calendar year in which the withholding took place.
The withholding agent must furnish complete and correct copies of Form(s) 592-B to the payee by the due date.
If your situation is different
An error is discovered
If an error is discovered after the withholding agent provides Form 592-B to the payee, the withholding agent must follow the amending instructions for Form 592, Form 592-PTE, or Form 592-F.
Complete a new Form 592-B using the same taxable year form as originally provided to the payee.
Provide the amended copy of Form 592-B to the payee.
The payee is a grantor trust
If the payee is a grantor trust, enter the individual name and SSN or ITIN of the grantor that is required to file a tax return and report the income.
If the payee is a grantor trust, do not enter the name of the trust or trustee information.
The payee is a nongrantor trust
If the payee is a nongrantor trust, enter the name of the trust and the trust's FEIN.
If the payee is a nongrantor trust, do not enter trustee information.
If the trust has applied for a FEIN, but it has not been received, enter "applied for" in the space for the trust's FEIN and attach a copy of the federal application to the back of Form 592-B.
After the FEIN is received, amend Form 592-B to submit the assigned FEIN.
The payees are married/RDP
If the payees are married/RDP, enter only the name and SSN or ITIN of the primary spouse/RDP.
If the payees intend to file separate California tax returns, the withholding agent should split the withholding and complete a separate Form 592-B for each spouse/RDP.
The form is for foreign partners or foreign members
For foreign partners or foreign members, match the year at the top left corner of Form 592-B to the year that the partnership's or LLC's taxable year ended.
You are the payee
Enter the amount from Form 592-B, Part IV, line 2 on your California tax return as withholding from Form(s) 592-B or 593, Real Estate Withholding Statement.
Attach a copy of Form 592-B to your California tax return.
If a payee notices an error, the payee should contact the withholding agent. Only withholding agents can complete an amended Form 592-B.
Keep a copy for a minimum of five years and provide it to the FTB upon request.
Common questions about Form 592-B
Is there a deadline?
Form 592-B must be completed and provided to each payee by February 15th following the close of the calendar year for brokers as stated in Internal Revenue Code (IRC) Section 6045. Form 592-B must be provided to each foreign (non-U.S.) partner or member by the 15th day of the 3rd month following the close of the partnership's or LLC's taxable year. Form 592-B must be provided to each foreign (non-U.S.) partner or member by the 15th day of the 6th month following the close of the partnership's or LLC's taxable year, if all the partners in the partnership or members in the LLC are foreign.
Is there a penalty?
If the withholding agent fails to provide complete, correct, and timely Form(s) 592-B to the payee, the penalty per Form 592-B is up to $130 for each payee statement not provided by the due date. (checked November 8, 2026) If the withholding agent fails to provide complete, correct, and timely Form(s) 592-B to the payee, the penalty per Form 592-B is $330 or 10% of the amount required to be reported (whichever is greater), if the failure is due to intentional disregard of the requirement. (checked November 8, 2026)
When is this form not the right one?
In the Form 592-B Instructions 2024: do not use Form 592-B to allocate or distribute withholding to each payee, use Form 592, Form 592-PTE, or Form 592-F. Pass-through entities withheld upon by another entity use Form 592-PTE to pass through the withholding to domestic nonresident partners in a partnership, members of a limited liability company (LLC), estate or trust beneficiaries, and S corporation shareholders. Pass-through entities withheld upon by another entity use Form 592-F to pass through the withholding to foreign (non-U.S.) partners or members.
Sources
[1] Form 592-B (2025), Resident and Nonresident Withholding Tax Statement, California Franchise Tax Board (the Official source link on this page).