

Form HUD-92800.5B at a glance
What it is: Form HUD-92800.5B, the Conditional Commitment Direct Endorsement Statement of Appraised Value, sets the terms of the commitment and the conditions that must be met before HUD can endorse a Firm Commitment for Mortgage Insurance.
This form serves as the application for individual "proposed construction" and "existing construction" properties.
Responses to the collection of information are required to obtain mortgage insurance.
Information contained in this collection will be used only for the purpose of determining the eligibility of a property for mortgage insurance.
A filled-in Form HUD-92800.5B example: a lender issues a Conditional Commitment
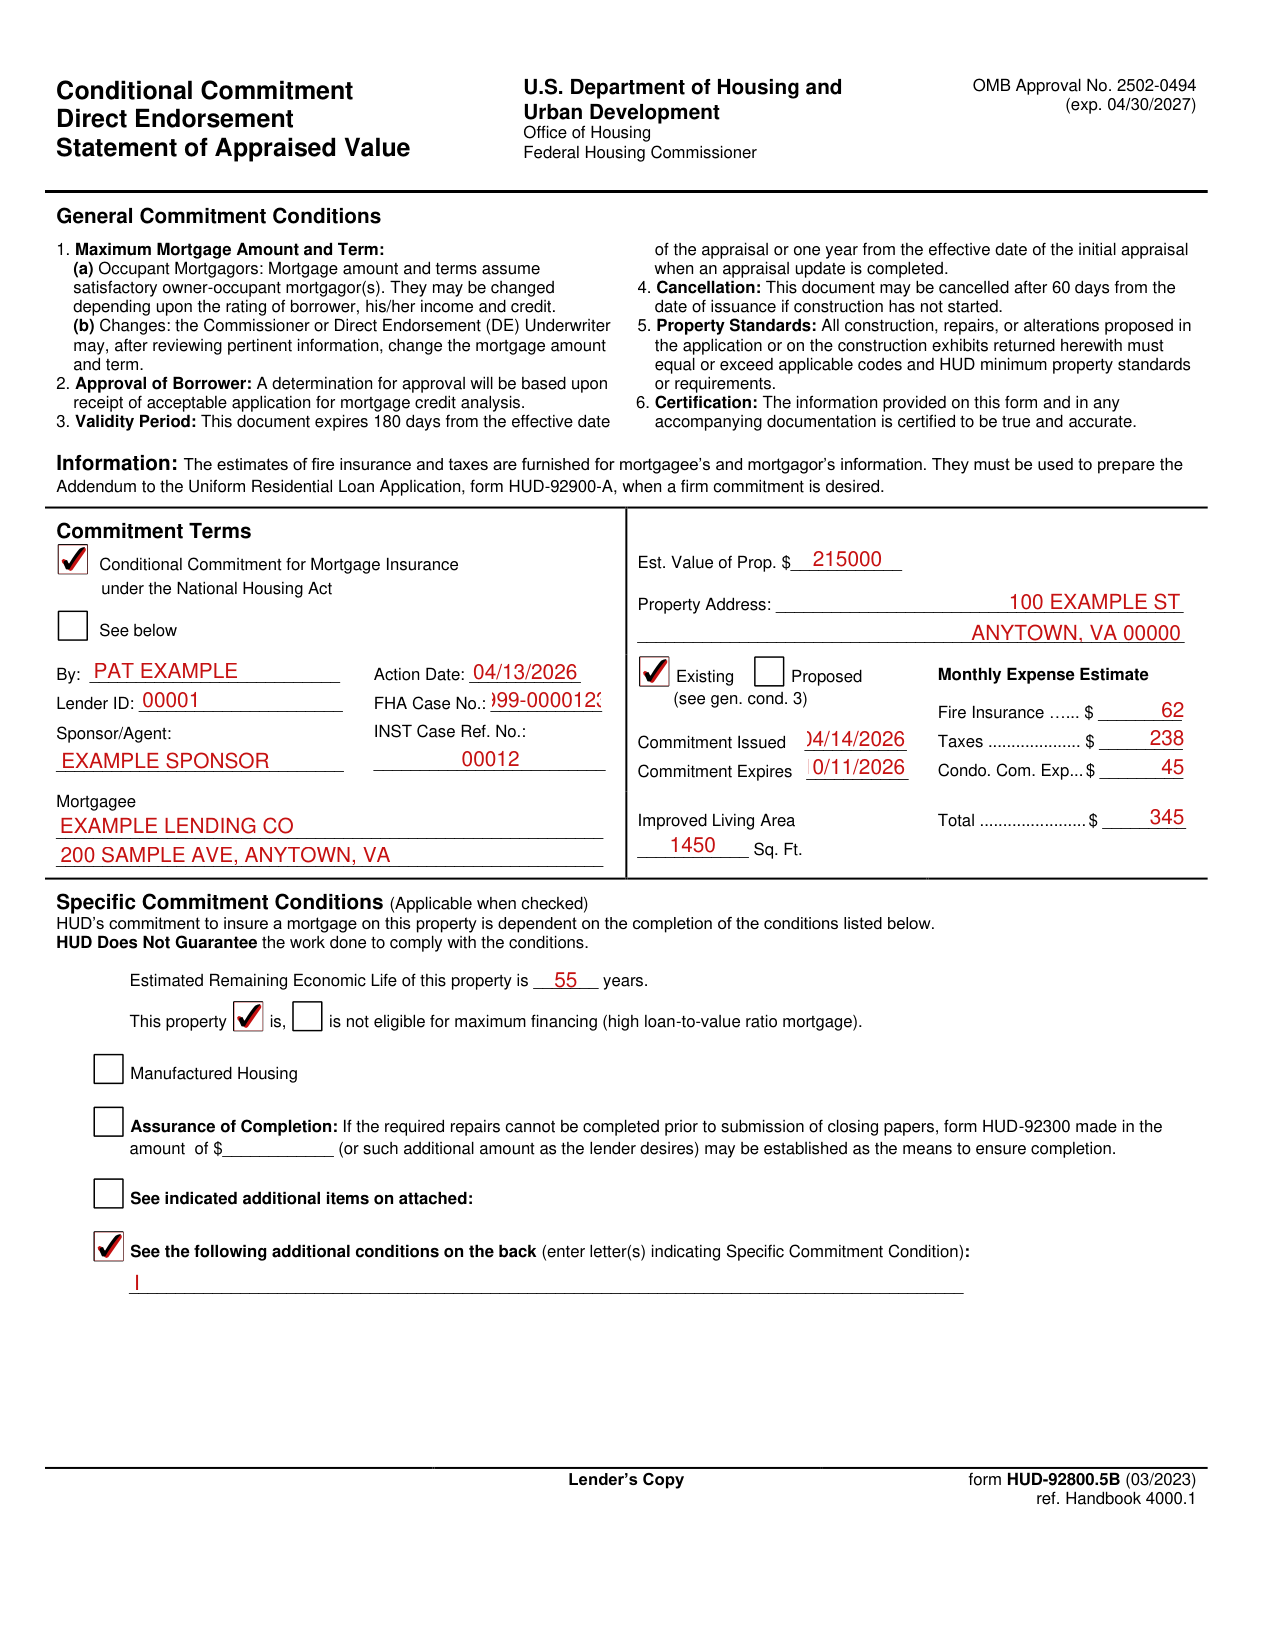
How to fill out Form HUD-92800.5B, box by box
Tap a group of boxes to open it, and a picture to see it full size.
Commitment Terms
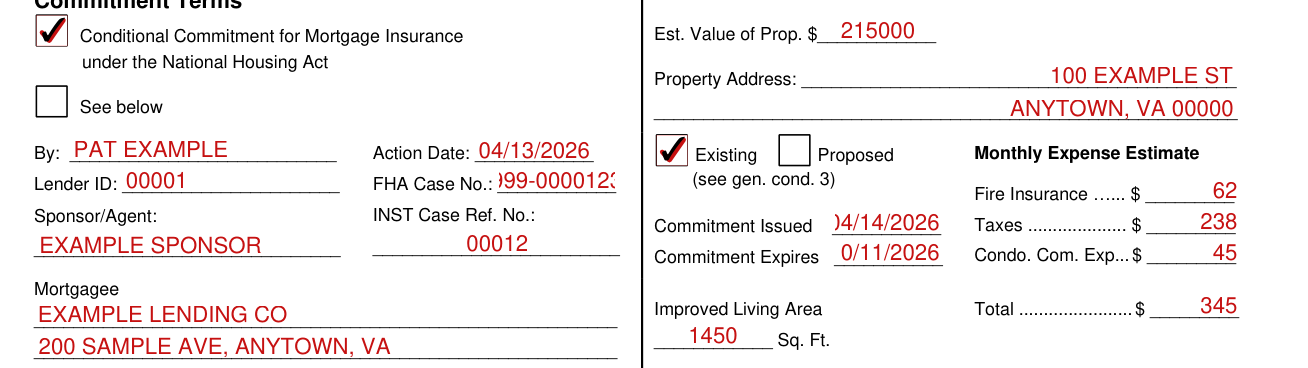
Check Conditional Commitment for Mortgage Insurance under the National Housing Act.
Enter the Est. Value of Prop. and the Property Address.
Estimated Value of Property: The amount HUD considers the property to be worth.
Check Existing or Proposed (see gen. cond. 3).
Enter By and the Lender ID.
Enter the Action Date, the FHA Case No. and the INST Case Ref. No.
Enter the Sponsor/Agent.
Enter Commitment Issued and Commitment Expires.
Enter the Improved Living Area in Sq. Ft.
Enter the Mortgagee on the two lines.
Enter the Monthly Expense Estimate for Fire Insurance, Taxes and Condo. Com. Exp., and the Total.
Information: The estimates of fire insurance and taxes are furnished for mortgagee's and mortgagor's information. They must be used to prepare the Addendum to the Uniform Residential Loan Application, form HUD-92900-A, when a firm commitment is desired.
General Commitment Conditions
1. Maximum Mortgage Amount and Term: (a) Occupant Mortgagors: Mortgage amount and terms assume satisfactory owner-occupant mortgagor(s). They may be changed depending upon the rating of borrower, his/her income and credit.
(b) Changes: the Commissioner or Direct Endorsement (DE) Underwriter may, after reviewing pertinent information, change the mortgage amount and term.
2. Approval of Borrower: A determination for approval will be based upon receipt of acceptable application for mortgage credit analysis.
3. Validity Period: This document expires 180 days from the effective date of the appraisal or one year from the effective date of the initial appraisal when an appraisal update is completed.
4. Cancellation: This document may be cancelled after 60 days from the date of issuance if construction has not started.
5. Property Standards: All construction, repairs, or alterations proposed in the application or on the construction exhibits returned herewith must equal or exceed applicable codes and HUD minimum property standards or requirements.
6. Certification: The information provided on this form and in any accompanying documentation is certified to be true and accurate.
Economic life, maximum financing and additional conditions
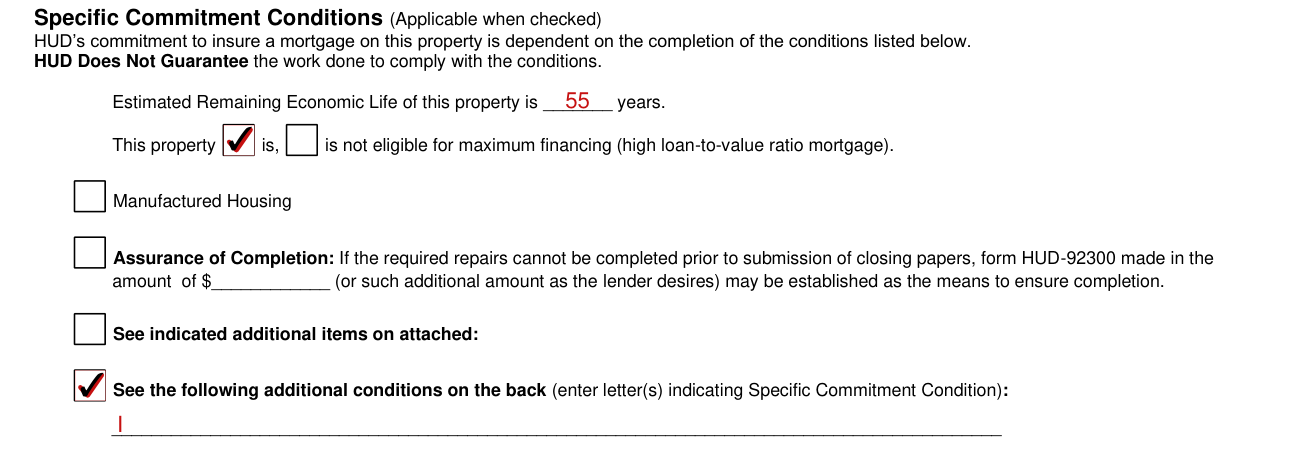
Specific Commitment Conditions are applicable when checked. HUD's commitment to insure a mortgage on this property is dependent on the completion of the conditions listed.
HUD does not guarantee the work done to comply with the conditions.
Enter the Estimated Remaining Economic Life of this property in years.
Check one: This property is, or is not, eligible for maximum financing (high loan-to-value ratio mortgage).
Manufactured Housing is one of the Specific Commitment Conditions, which are applicable when checked.
Assurance of Completion: If the required repairs cannot be completed prior to submission of closing papers, form HUD-92300 made in the amount entered in the box (or such additional amount as the lender desires) may be established as the means to ensure completion.
See indicated additional items on attached is one of the Specific Commitment Conditions, which are applicable when checked.
Specific Commitment Conditions
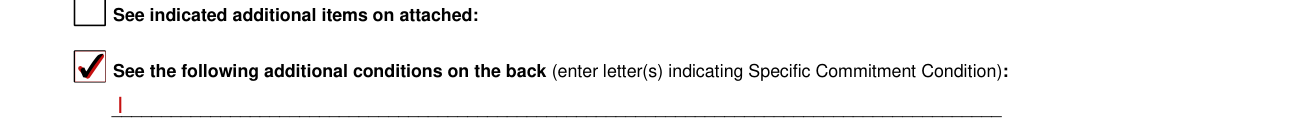
See the following additional conditions on the back is applicable when checked; enter the letter(s) indicating Specific Commitment Condition.
The Specific Commitment Conditions are applicable when indicated on the front of this form.
E. Health Authority Approval: Submit local health authority approval (on a form or letter) indicating the individual water supply and/or sewage disposal system is acceptable.
G. Prefabricator's Certificate: The Lender shall provide a prefabrication certificate as required by the related engineering bulletin.
I. Flood Insurance Requirement: This property is located in a special flood hazard area and must be covered by flood insurance in accordance with HUD regulation 24 CFR 203.16a.
L. Code Enforcement: The lender shall submit a statement from the public authority that the property meets local code requirements. If the mortgage on the property is to be insured under Section 221(d)(2), a code compliance inspection is required.
M. Repairs: The lender shall notify the original appraiser upon completion of required repairs, unless otherwise instructed.
N. Lender's Certificate of Completion: The lender shall furnish a certificate that required repairs have been examined and were satisfactorily completed.
U. The lender shall furnish a certificate of occupancy or letter of acceptance from the local building authority.
Grace Period
Grace Period: If this application is rejected, the lender may request reconsideration within 60 days of the last rejection date.
Where a sales contract is signed prior to the expiration of the Conditional Commitment/ Direct Endorsement Statement of Appraised Value, a lender has 30 days to process or submit an application to the Field Office for a Firm Commitment.
A Firm Commitment with a term of 90 days may be issued.
More rules for Form HUD-92800.5B
The form has a Lender's Copy, a Case Binder Copy and a Homebuyer's Copy.
The law requires that borrowers using HUD-insured financing must receive a copy of this form prior to the purchase of property.
This form must be delivered to the borrower promptly, but no later than at the time of the borrower's signing of the Uniform Residential Loan Application (URLA) and Addendum (form HUD-92900-A).
Proposed Construction and Existing Construction
Proposed Construction
B. Proposed Construction: The builder or mortgagee must notify the assigned inspector as appropriate (see items P, Q, and R).
C. Warranty: Form HUD-92544 is required on all new construction and shall be executed between the builder and the purchaser.
H. Termite Control: (Proposed Construction) If soil poisoning is used, the builder shall complete form HUD-92052, Termite Soil Treatment Guarantee, and transmit a copy to HUD or the Direct Endorsement Underwriter. The Mortgagee will deliver the original and a copy to the mortgagor at closing.
P. Initial Inspection (2 working days) is requested before the "beginning of construction" with forms in place.
Q. Frame Inspection (1 working day) is requested when the building is enclosed and framing, plumbing, heating, electrical, and insulation is complete and visible.
R. Final Inspection is requested when construction is completed and the property ready for occupancy.
Existing Construction
K. Termite Control (Existing Construction): A recognized termite control operator shall furnish certification using form NCPA-1, or State-mandated form, that the house and other structures within the legal boundaries of the property indicate no evidence of active termite infestation.
Common questions about Form HUD-92800.5B
What is a HUD 92800.5 b form?
Form HUD-92800.5B, the Conditional Commitment Direct Endorsement Statement of Appraised Value, sets the terms of the commitment and the conditions that must be met before HUD can endorse a Firm Commitment for Mortgage Insurance.
Sources
[1] Form HUD-92800.5B (03/2023), Conditional Commitment Direct Endorsement Statement of Appraised Value, U.S. Department of Housing and Urban Development (the Official source link on this page).
