

Form MW506NRS at a glance
What it is: Form MW506NRS is the Maryland Return of Income Tax Withholding for Nonresident Sale of Real Property 2024.
Where and when to file: Unless the transaction is otherwise exempt from the income tax withholding requirement, the person responsible for closing must include with the deed or other instrument of transfer, a Form MW506NRS for each nonresident transferor/seller, when the deed or other instrument of transfer is presented to the Clerk of the Circuit Court for recordation.
Form MW506NRS is designed to assure the regular and timely collection of Maryland income tax due from nonresident sellers of real property located within the State. This form is used to determine the amount of income tax withholding due on the sale of property and provide for its collection at the time of the sale or transfer.
If the transferor/seller is a nonresident individual or entity, and is transferring an interest in real property located within the State of Maryland, unless the transaction is otherwise exempt from the income tax withholding requirement, the person responsible for closing must file Form MW506NRS with the deed or other instrument of transfer that will be filed with the Clerk of the Circuit Court for recordation.
If there are multiple transferors/sellers, a separate form must be completed for each nonresident individual or nonresident entity subject to the withholding requirements. The separate form requirement does not apply to spouses filing a joint Maryland income tax return.
A “nonresident entity” is defined to mean an entity that: (1) is not formed under the laws of Maryland more than 90 days before the date of sale of the property, and (2) is not qualified by or registered with the Department of Assessments and Taxation to do business in Maryland more than 90 days before the date of sale of the property.
A filled-in Form MW506NRS example: a closing agent files for a nonresident seller
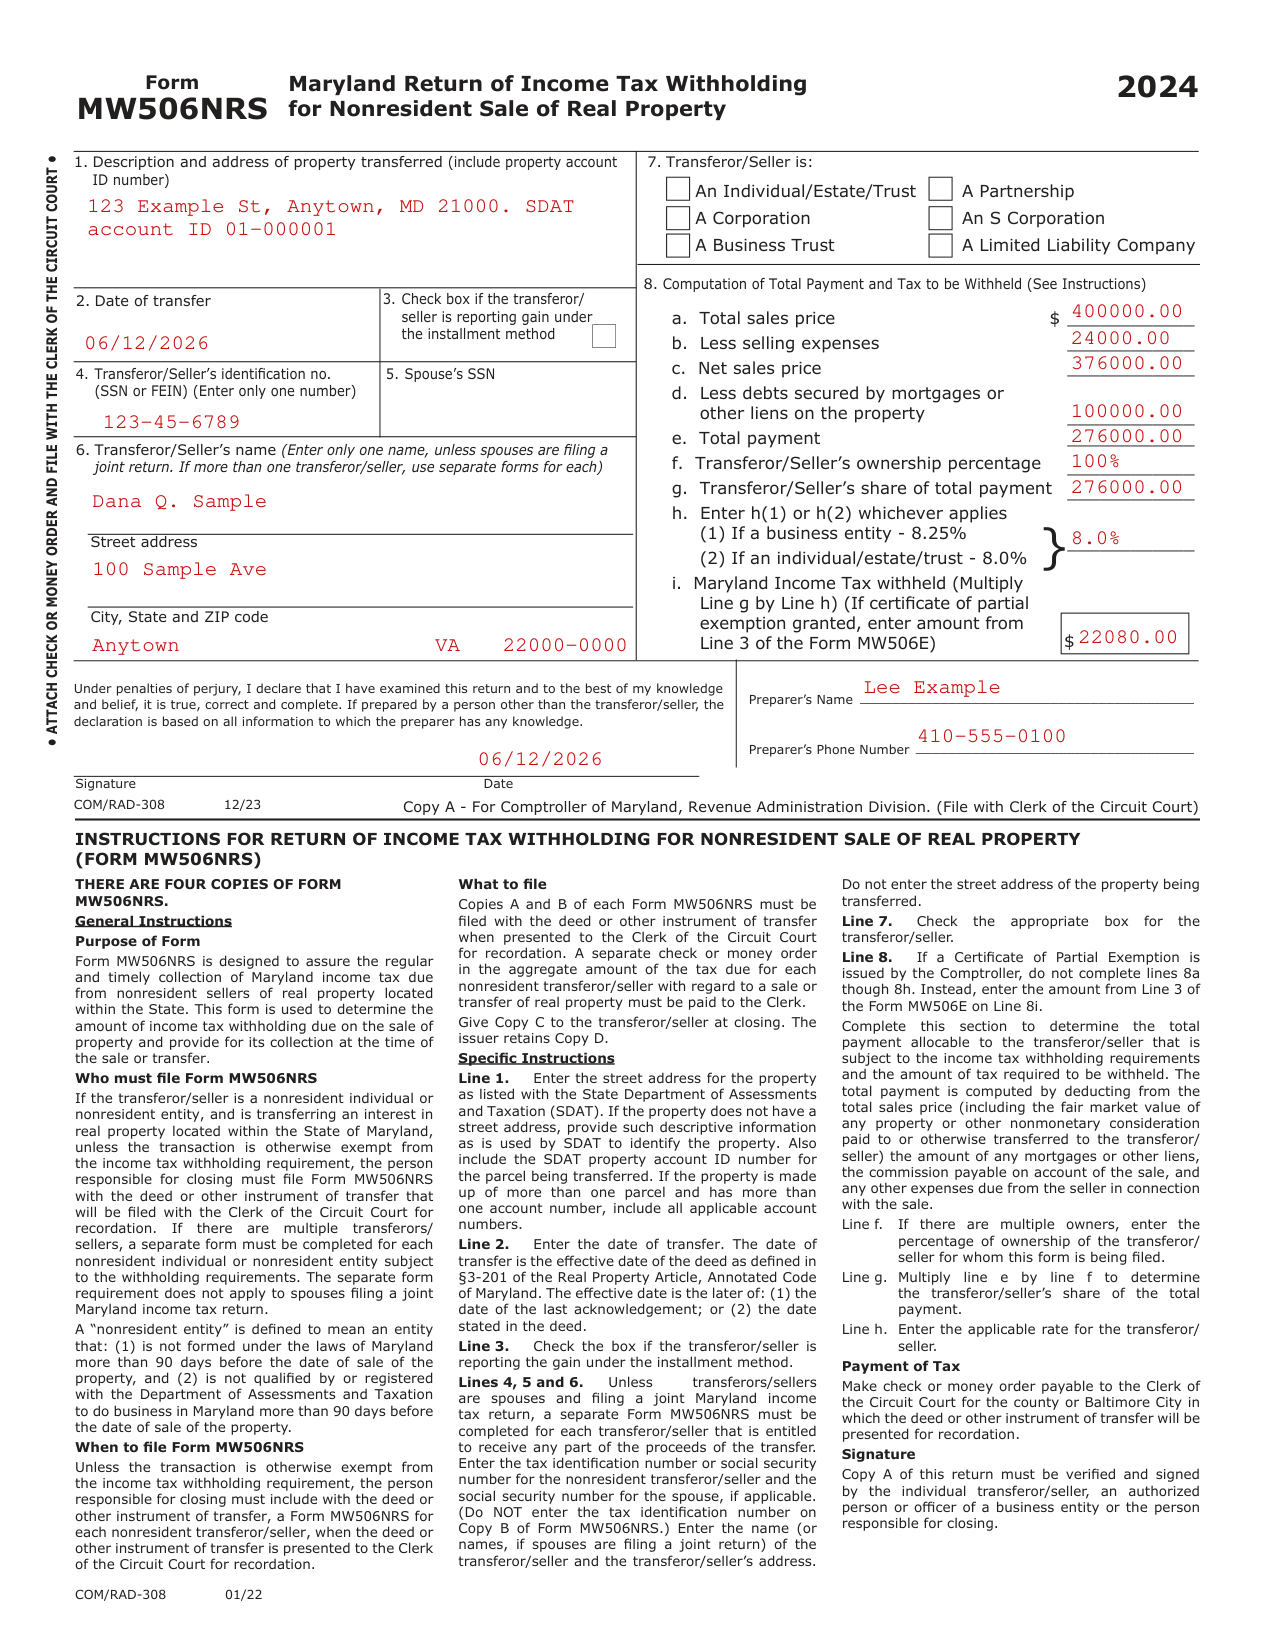
How to fill out Form MW506NRS, box by box
Description and address of property transferred
Line 1. Enter the street address for the property as listed with the State Department of Assessments and Taxation (SDAT). If the property does not have a street address, provide such descriptive information as is used by SDAT to identify the property. Also include the SDATproperty account ID number for the parcel being transferred. If the property is made up of more than one parcel and has more than one account number, include all applicable account numbers.
Date of transfer and installment method
Line 2. Enter the date of transfer. The date of transfer is the effective date of the deed as defined in §3-201 of the Real Property Article, Annotated Code of Maryland. The effective date is the later of: (1) the date of the last acknowledgement; or (2) the date stated in the deed.
Line 3. Check the box if the transferor/seller is reporting the gain under the installment method.
Spouse's SSN, identification number, name and address
Lines 4, 5 and 6. Unless transferors/sellers are spouses and filing a joint Maryland income tax return, a separate Form MW506NRS must be completed for each transferor/seller that is entitled to receive any part of the proceeds of the transfer. Enter the tax identification number or social security number for the nonresident transferor/seller and the social security number for the spouse, if applicable.
(Do NOT enter the tax identification number on Copy B of Form MW506NRS.)
Enter the name (or names, if spouses filing a joint return) of the transferor/ seller and the transferor/seller's address. Do not enter the street address of the property being transferred.
Transferor/Seller is
Line 7. Check the appropriate box for the transferor/seller.
Computation of Total Payment and Tax to be Withheld
Line 8. If a Certificate of Partial Exemption is issued by the Comptroller, do not complete lines 8a though 8h. Instead, enter the amount from Line 3 of the Form MW506E on Line 8i.
The total payment is computed by deducting from the total sales price (including the fair market value of any property or other nonmonetary consideration paid to or otherwise transferred to the transferor/seller) the amount of any mortgages or other liens, the commission payable on account of the sale and any other expenses due from the seller in connection with the sale.
Line f. If there are multiple owners, enter the percentage of ownership of the transferor/ seller for whom this form is being filed.
Line g. Multiply line e by line f to determine the transferor/seller's share of the total payment.
Line h. Enter the applicable rate for the transferor/seller. Enter h(1) or h(2) whichever applies: (1) If a business entity - 8.25% (2) If an individual/estate/trust - 8.0%
Maryland Income Tax withheld (Multiply Line g by Line h) (If certificate of partial exemption granted, enter amount from Line 3 of the Form MW506E)
Declaration, preparer and signature
Under penalties of perjury, I declare that I have examined this return and to the best of my knowledge and belief, it is true, correct and complete. If prepared by a person other than the transferor/seller, the declaration is based on all information to which the preparer has any knowledge.
Copy A of this return must be verified and signed by the individual transferor/seller, an authorized person or officer of a business entity or the person responsible for closing.
More rules for Form MW506NRS
Give Copy C to the transferor/seller at closing. The issuer retains Copy D.
A nonresident individual or nonresident entity that sells real property located in Maryland must file a Maryland income tax return. The appropriate income tax return must be filed for the year in which the transfer of the real property occurred. The due date for each income tax return type can be found in the instructions to the specific income tax return.
The manner in which the income tax withheld is claimed by the nonresident individual or nonresident entity depends on the type of Maryland income tax return you are required to file. The income tax withheld and reported on Line 8 of the Form MW506NRS must be claimed as an estimated income tax payment.
Nonresident individuals are required to file a Nonresident Maryland Income Tax Return (Form 505).
C corporations are required to file a Maryland Corporation Income Tax Return (Form 500).
S corporations, partnerships and limited liability companies and business trusts that elect to be treated as pass-through entities must file a Maryland Pass-Through Entity Income Tax Return (Form 510).
Trustees of trusts and personal representatives of estates are required to file a Maryland Fiduciary Income Tax Return (Form 504).
Do NOT submit Copy C of the Form MW506NRS with the return filed with the Comptroller of Maryland.
Before you go
A separate check or money order in the aggregate amount of the tax due for each nonresident transferor/seller with regard to a sale or transfer of real property must be paid to the Clerk.
Make check or money order payable to the Clerk of the Circuit Court for the county or Baltimore City in which the deed or other instrument of transfer will be presented for recordation.
Common questions about Form MW506NRS
Where do I file it?
Copies A and B of each Form MW506NRS must be filed with the deed or other instrument of transfer when presented to the Clerk of the Circuit Court for recordation.
Sources
[1] Form MW506NRS (COM/RAD-308 12/23), Maryland Return of Income Tax Withholding for Nonresident Sale of Real Property 2024, Comptroller of Maryland (the Official source link on this page).
