

Form ST-10 at a glance
What it is: Form ST-10 is the Commonwealth of Virginia Sales and Use Tax Certificate of Exemption.
Who signs: If the dealer is a corporation, an officer of the corporation or other person authorized to sign on behalf of the corporation must sign; if a partnership, one partner must sign; if an unincorporated association, a member must sign; if a sole proprietorship, the proprietor must sign.
The form is for use by a Virginia dealer who purchases tangible personal property for resale, or for lease or rental, or who purchases materials or containers to package tangible personal property for sale.
A filled-in Form ST-10 example: a sole proprietor buys for resale
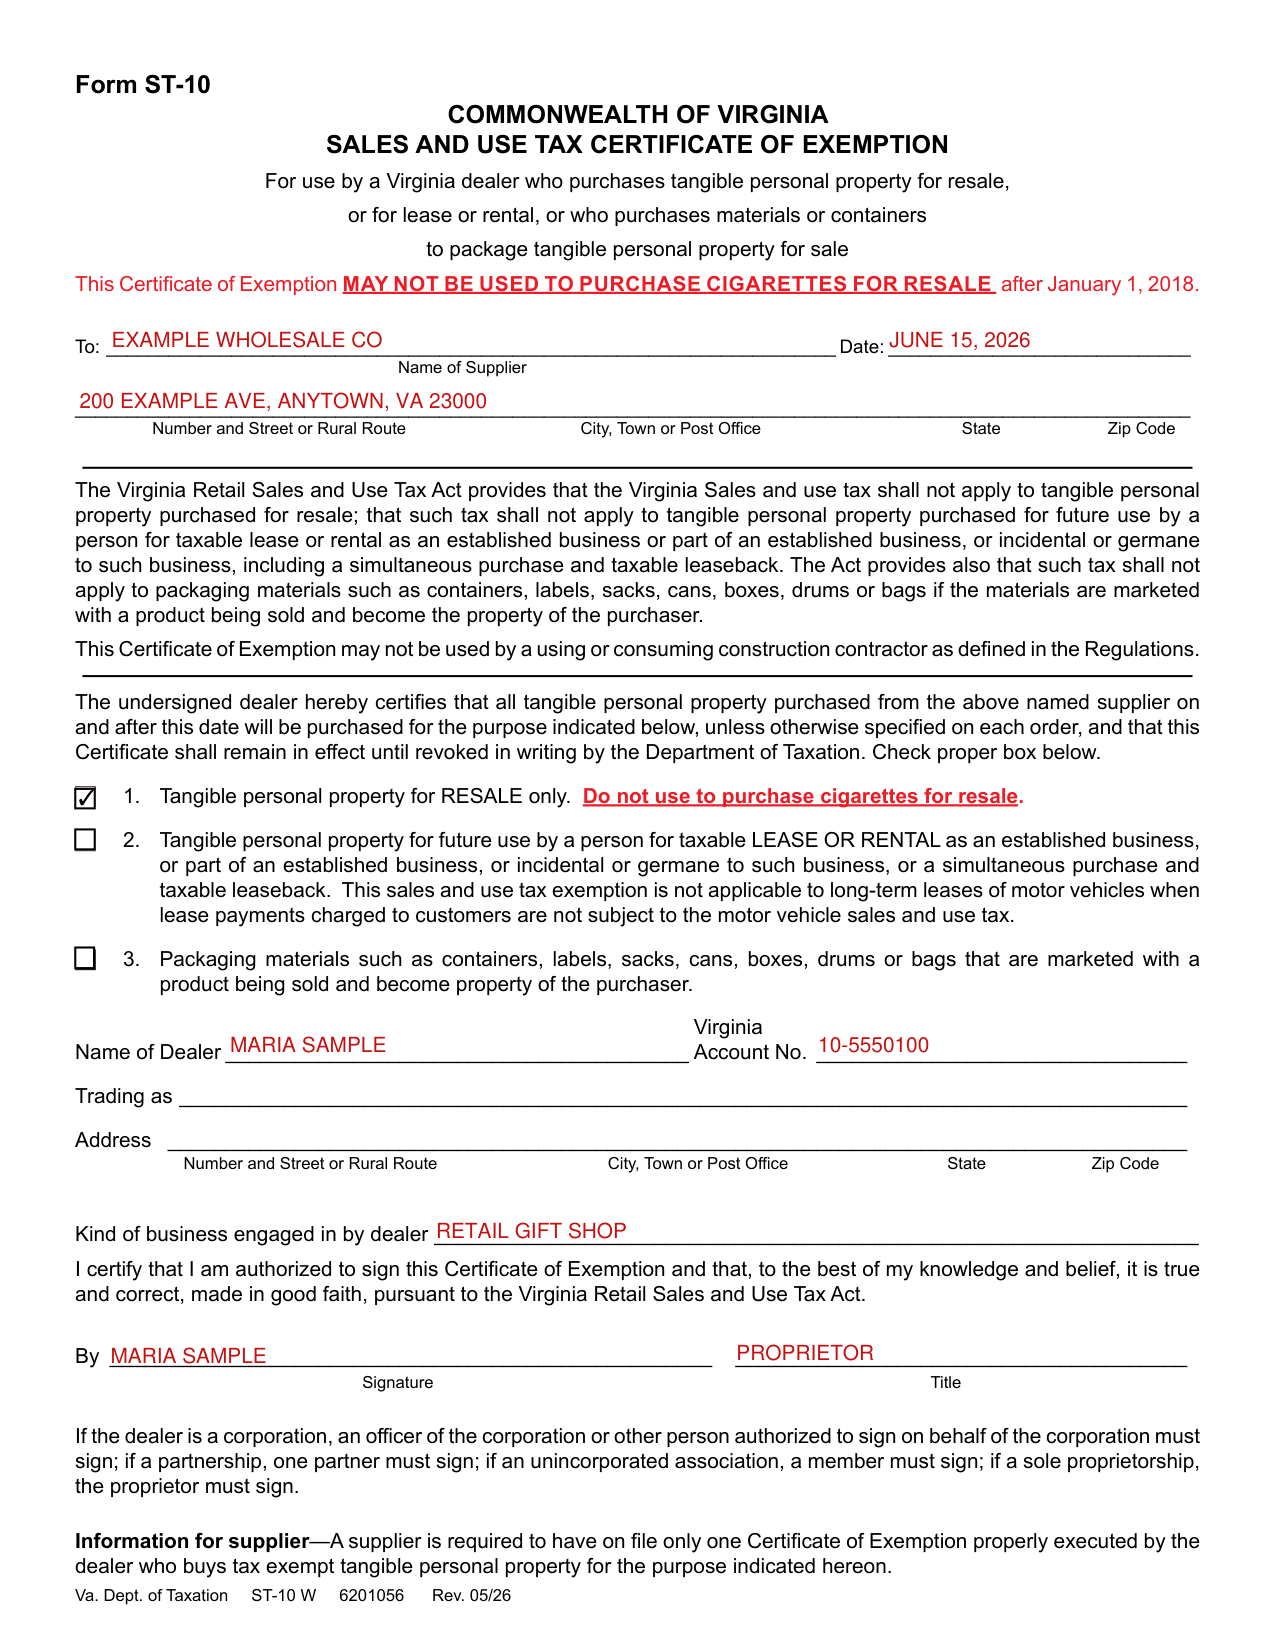
How to fill out Form ST-10, box by box
To: Name of Supplier and Date
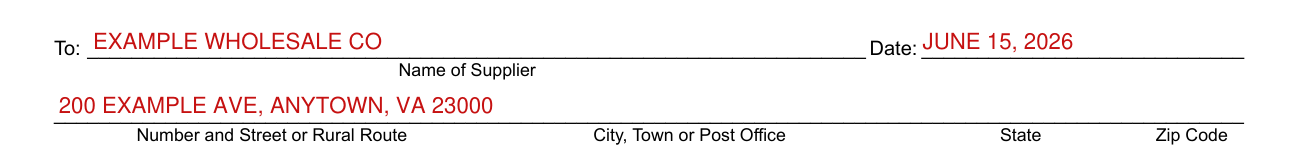
After To, enter the Name of Supplier and the Number and Street or Rural Route, and enter the Date.
The undersigned dealer certifies that all tangible personal property purchased from the named supplier on and after this date will be purchased for the purpose indicated by the box checked, unless otherwise specified on each order, and that this Certificate shall remain in effect until revoked in writing by the Department of Taxation. Check proper box.
Check proper box below
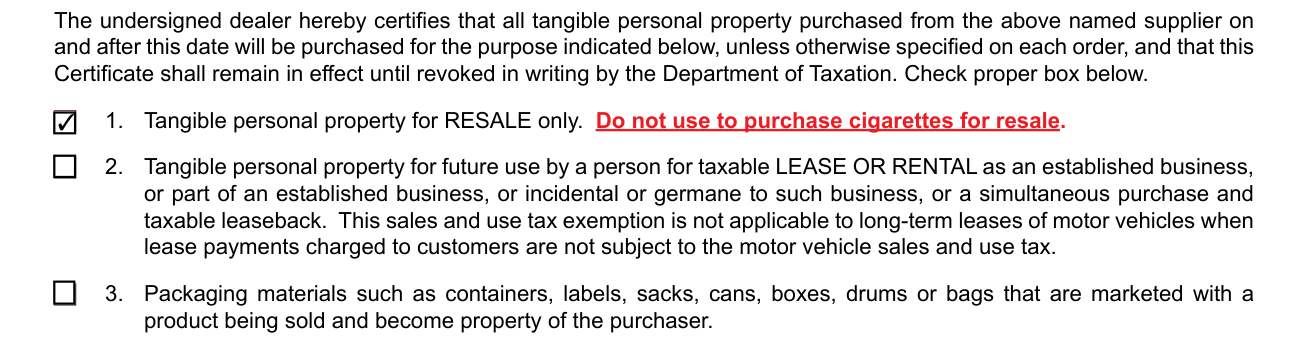
Check box 1 for tangible personal property for RESALE only. Do not use to purchase cigarettes for resale.
Check box 2 for tangible personal property for future use by a person for taxable LEASE OR RENTAL as an established business, or part of an established business, or incidental or germane to such business, or a simultaneous purchase and taxable leaseback. This sales and use tax exemption is not applicable to long-term leases of motor vehicles when lease payments charged to customers are not subject to the motor vehicle sales and use tax.
Check box 3 for packaging materials such as containers, labels, sacks, cans, boxes, drums or bags that are marketed with a product being sold and become property of the purchaser.
This Certificate of Exemption may not be used to purchase cigarettes for resale after January 1, 2018.
This Certificate of Exemption may not be used by a using or consuming construction contractor as defined in the Regulations.
Virginia Name of Dealer, Trading as and Address
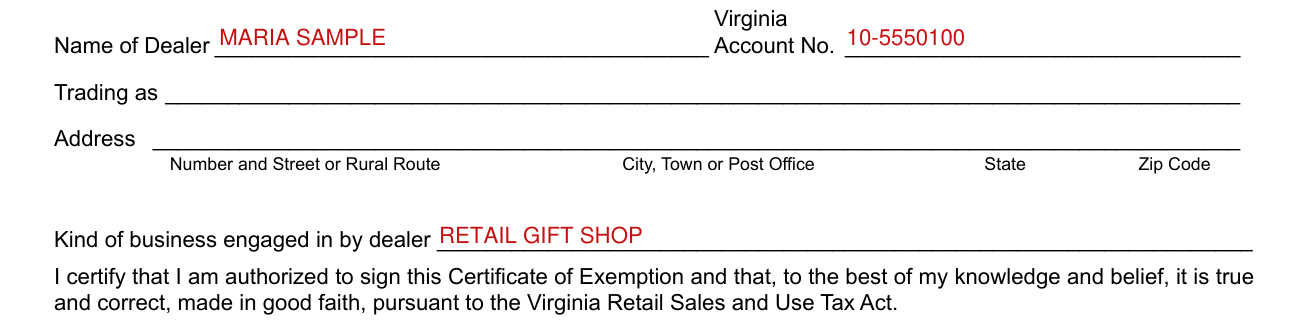
Enter the Virginia Name of Dealer and the Account No.
Enter the Trading as line, and the Address with Number and Street or Rural Route, City, Town or Post Office, State and Zip Code.
Enter the Kind of business engaged in by dealer.
Signing: By and Title
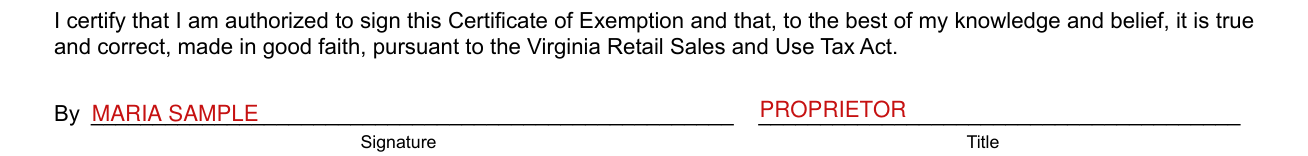
By signing, you certify that you are authorized to sign this Certificate of Exemption and that, to the best of your knowledge and belief, it is true and correct, made in good faith, pursuant to the Virginia Retail Sales and Use Tax Act.
Sign on the By line and enter the Title.
More rules for Form ST-10
A supplier is required to have on file only one Certificate of Exemption properly executed by the dealer who buys tax exempt tangible personal property for the purpose indicated hereon.
Common questions about Form ST-10
What is a ST-10 form in Virginia?
Form ST-10 is the Commonwealth of Virginia Sales and Use Tax Certificate of Exemption. The Virginia Retail Sales and Use Tax Act provides that the Virginia Sales and use tax shall not apply to tangible personal property purchased for resale; that such tax shall not apply to tangible personal property purchased for future use by a person for taxable lease or rental as an established business or part of an established business, or incidental or germane to such business, including a simultaneous purchase and taxable leaseback. The Act provides also that such tax shall not apply to packaging materials such as containers, labels, sacks, cans, boxes, drums or bags if the materials are marketed with a product being sold and become the property of the purchaser.
Sources
[1] Form ST-10 (Rev. 05/26), Sales and Use Tax Certificate of Exemption, Virginia Department of Taxation (the Official source link on this page).
