

Good Faith Estimate (GFE) at a glance
What it is: The Good Faith Estimate (GFE) gives you an estimate of your settlement charges and loan terms if you are approved for this loan.
A filled-in Good Faith Estimate (GFE) example: a lender prepares an estimate
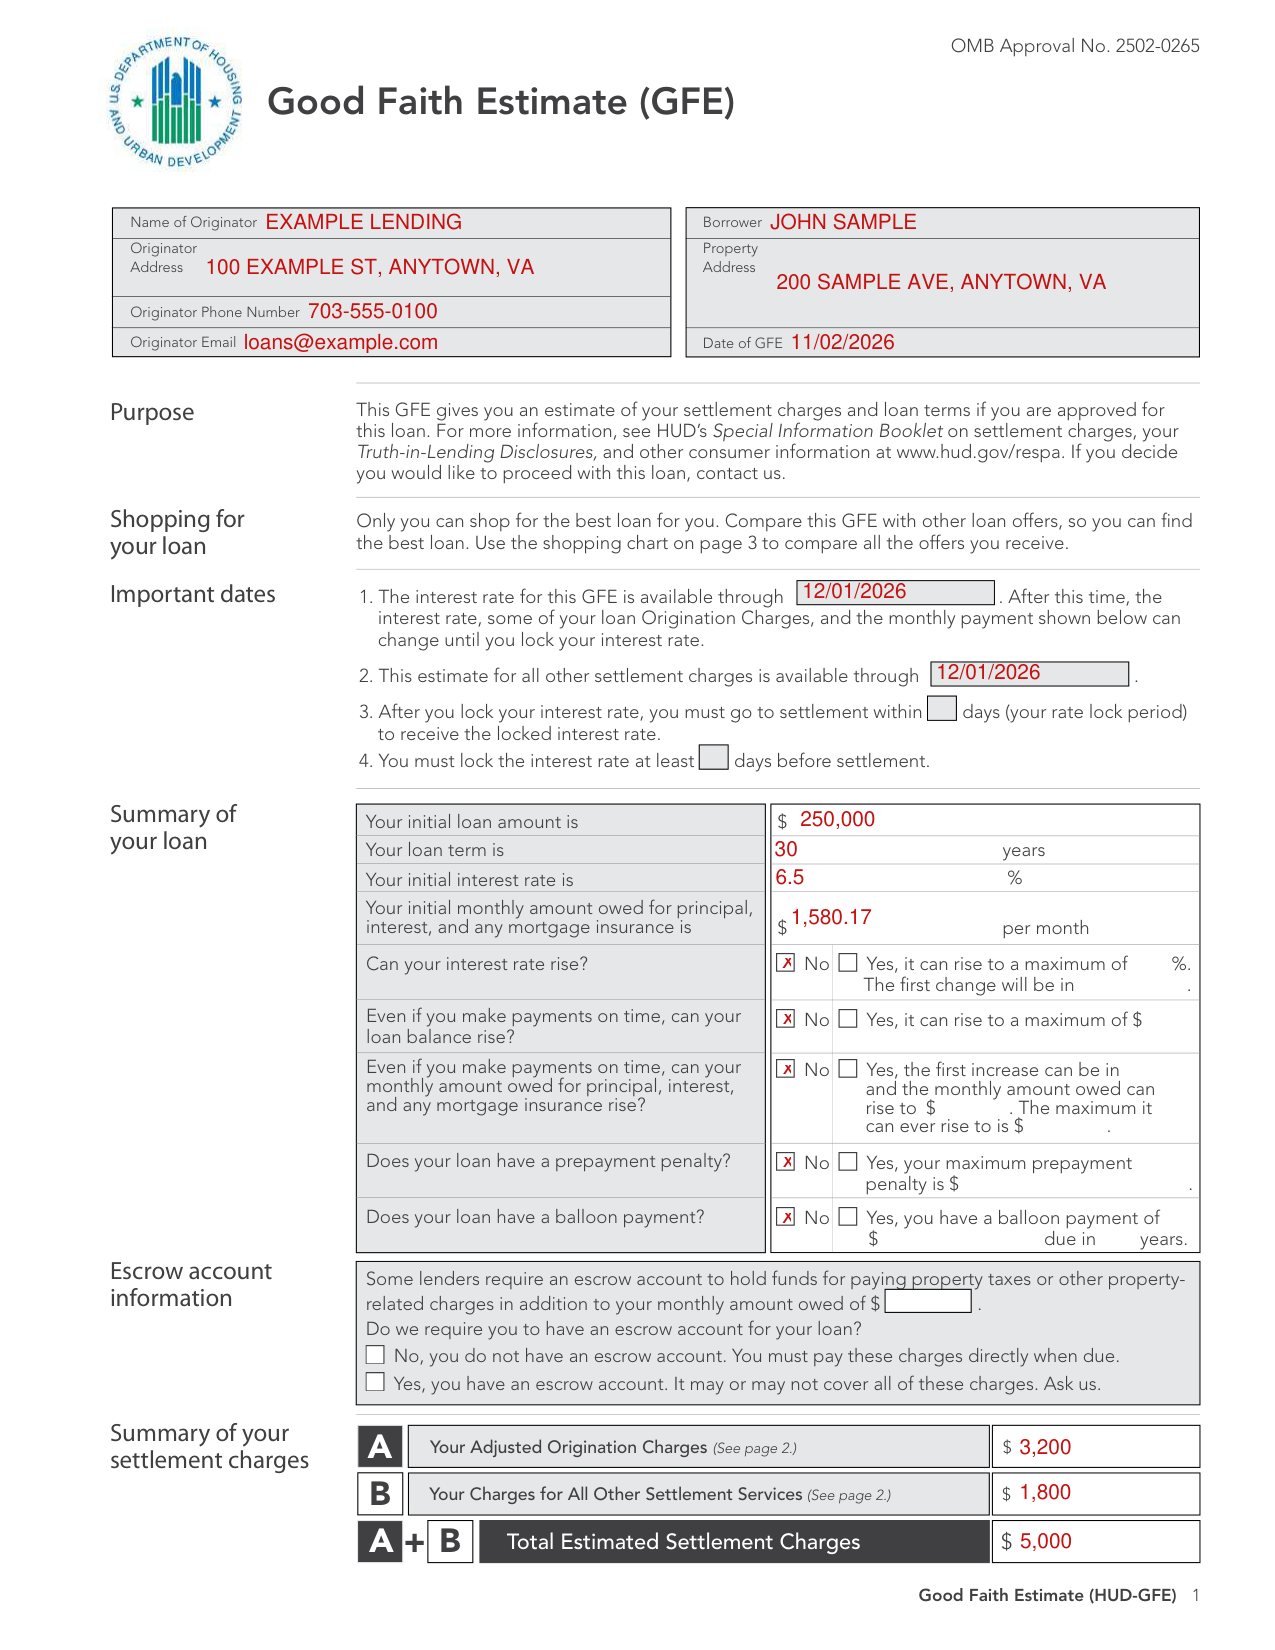
How to fill out Good Faith Estimate (GFE), box by box
Name of Originator, Borrower and Date of GFE
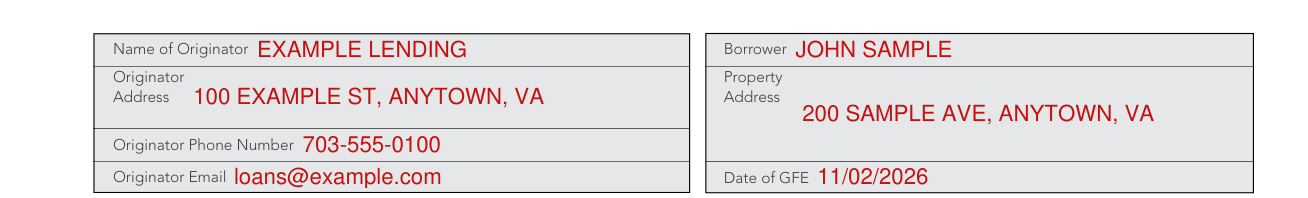
Enter the Name of Originator, Borrower, Originator Address, Property Address, Originator Phone Number, Originator Email and Date of GFE.
Important dates
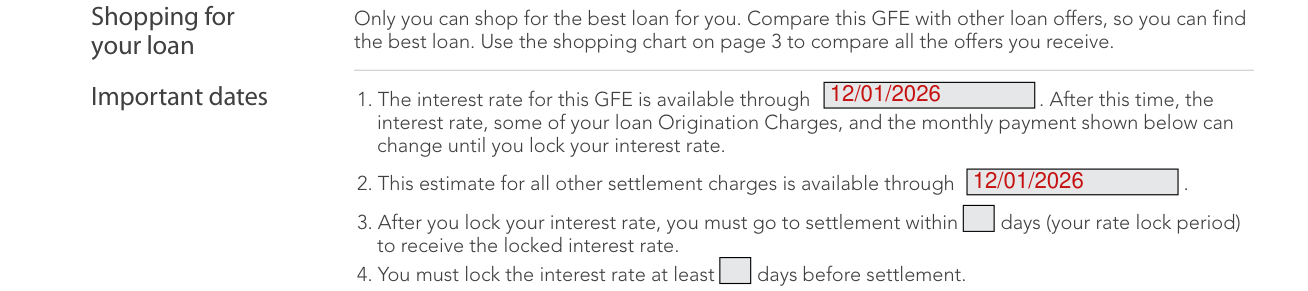
Box 1: the interest rate for this GFE is available through the time you enter. After this time, the interest rate, some of your loan Origination Charges, and the monthly payment can change until you lock your interest rate.
Box 2: this estimate for all other settlement charges is available through what you enter.
Box 3: after you lock your interest rate, you must go to settlement within the days you enter (your rate lock period) to receive the locked interest rate. Box 4: you must lock the interest rate at least the days you enter before settlement.
Summary of your loan
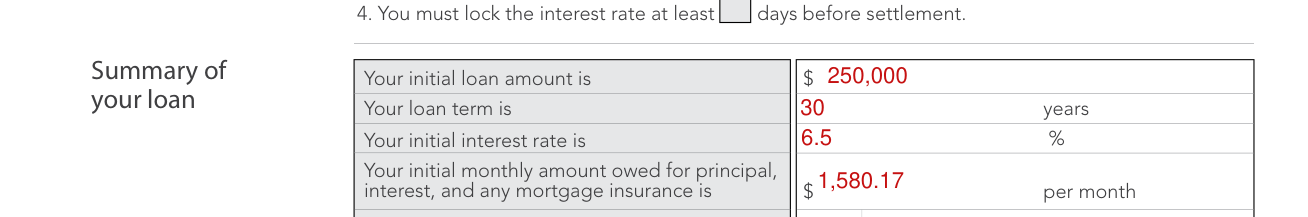
Enter your initial loan amount, your loan term in years, your initial interest rate in %, and your initial monthly amount owed for principal, interest, and any mortgage insurance in $ per month.
Can your loan change?
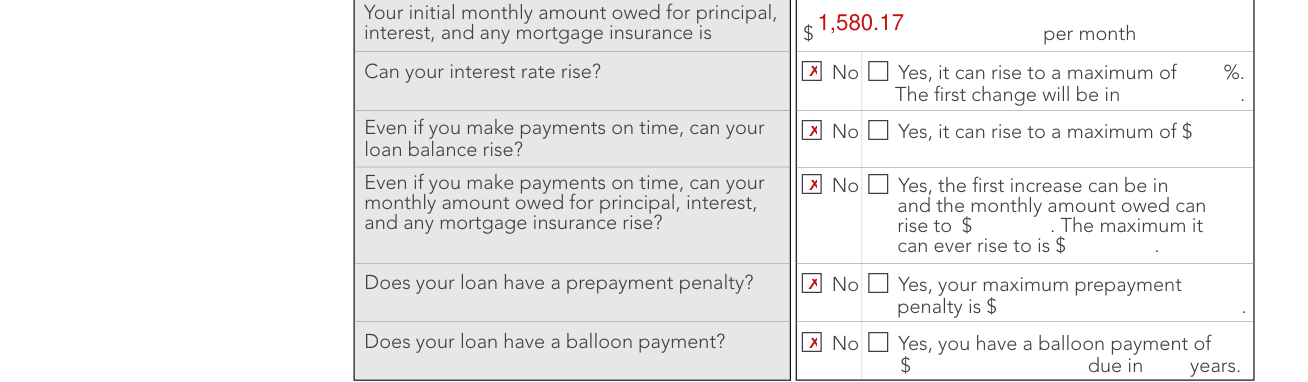
Can your interest rate rise? Check No, or check Yes: it can rise to a maximum of %. The first change will be in.
Even if you make payments on time, can your loan balance rise? Check No, or Yes. If Yes, it can rise to a maximum of $.
Even if you make payments on time, can your monthly amount owed for principal, interest, and any mortgage insurance rise? Check No, or check Yes: the first increase can be in the time you enter and the monthly amount owed can rise to $. The maximum it can ever rise to is $.
Does your loan have a prepayment penalty? Check No, or check Yes: your maximum prepayment penalty is $.
Does your loan have a balloon payment? Check No, or check Yes: you have a balloon payment of $ due in years.
Summary of your settlement charges
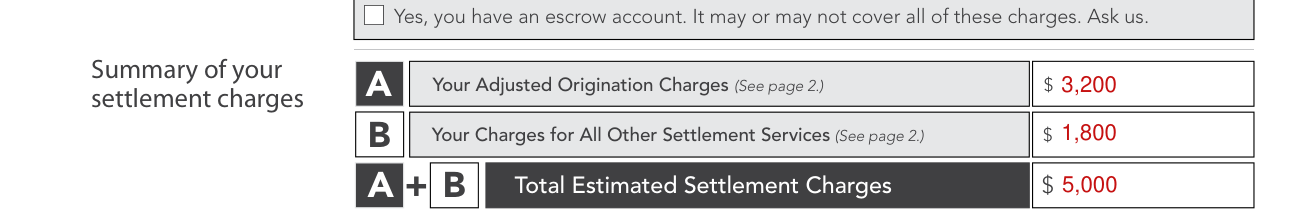
Enter Your Adjusted Origination Charges (See page 2.), Your Charges for All Other Settlement Services (See page 2.) and the Total Estimated Settlement Charges.
Using the shopping chart
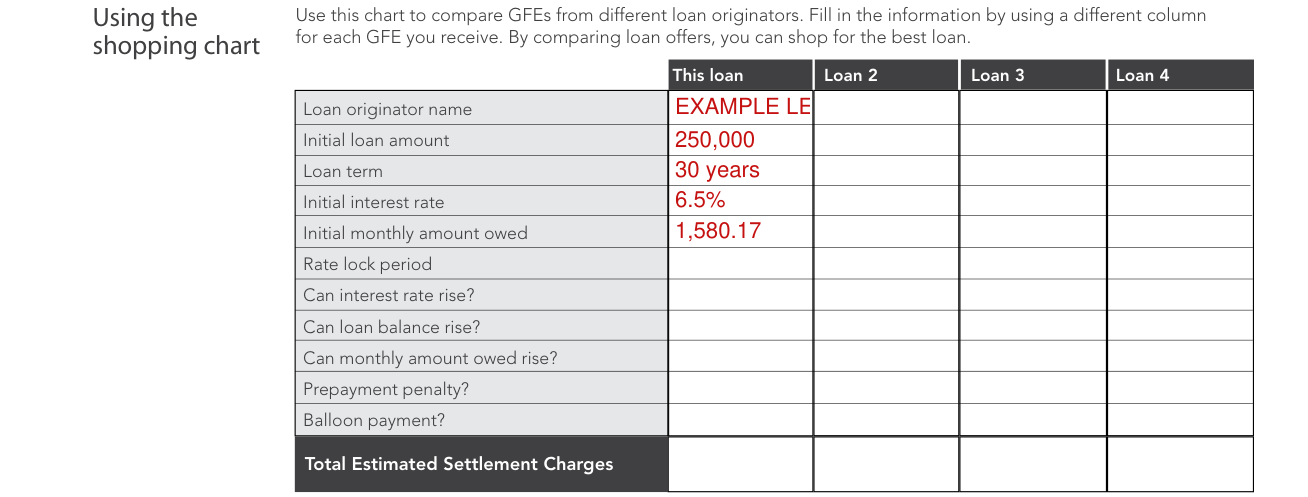
Use this chart to compare GFEs from different loan originators. Fill in the information by using a different column for each GFE you receive.
In the chart, fill in each column (This loan, Loan 2, Loan 3 and Loan 4) with: Loan originator name, Initial loan amount, Loan term, Initial interest rate, Initial monthly amount owed, Rate lock period, Can interest rate rise?, Can loan balance rise?, Can monthly amount owed rise?, Prepayment penalty?, Balloon payment? and Total Estimated Settlement Charges.
More rules for Good Faith Estimate (GFE)
Some lenders require an escrow account to hold funds for paying property taxes or other property-related charges in addition to your monthly amount owed of $. Is an escrow account required for your loan? Check No: you do not have an escrow account, and you must pay these charges directly when due. Or check Yes: you have an escrow account, and it may or may not cover all of these charges.
Origination charge: this charge is for getting this loan for you.
Your credit or charge (points) for the specific interest rate chosen. Check one box: The credit or charge for the interest rate of % is included in the origination charge. (See item 1.) Or You receive a credit of $ for this interest rate of %. This credit reduces your settlement charges. Or You pay a charge of $ for this interest rate of %. This charge (points) increases your total settlement charges.
The tradeoff table on page 3 shows that you can change your total settlement charges by choosing a different interest rate for this loan.
3. Required services: these charges are for services required to complete your settlement.
4. Title services and lender's title insurance: this charge includes the services of a title or settlement agent, for example, and title insurance to protect the lender, if required.
5. Owner's title insurance: you may purchase an owner's title insurance policy to protect your interest in the property.
6. Required services that you can shop for: these charges are for other services that are required to complete your settlement. You can shop for them yourself.
7. Government recording charges: these charges are for state and local fees to record your loan and title documents.
8. Transfer taxes: these charges are for state and local fees on mortgages and home sales.
9. Initial deposit for your escrow account: this charge is held in an escrow account to pay future recurring charges on your property.
10. Daily interest charges: this charge is for the daily interest on your loan from the day of your settlement until the first day of the next month or the first day of your normal mortgage payment cycle. This amount is $ per day for the days you enter.
11. Homeowner's insurance: this charge is for the insurance you must buy for the property to protect from a loss, such as fire.
This GFE estimates your settlement charges. At your settlement, you will receive a HUD-1, a form that lists your actual costs. Compare the charges on the HUD-1 with the charges on this GFE.
Charges can change if you select your own provider and do not use the companies identified.
This GFE offers you this loan with a particular interest rate and estimated settlement charges. However: If you want to choose this same loan with lower settlement charges, then you will have a higher interest rate. If you want to choose this same loan with a lower interest rate, then you will have higher settlement charges.
If you would like to choose an available option, you must ask for a new GFE. Loan originators have the option to complete this table. Please ask for additional information if the table is not completed.
Fill in Your initial loan amount, Your initial interest rate and Your initial monthly amount owed for The loan in this GFE, The same loan with lower settlement charges and The same loan with a lower interest rate.
Change in the monthly amount owed from this GFE: No change, You will pay $ more every month, or You will pay $ less every month.
Change in the amount you will pay at settlement with this interest rate: No change, Your settlement charges will increase by $, or Your settlement charges will be reduced by $. Then enter How much your total estimated settlement charges will be.
1: For an adjustable rate loan, the comparisons are for the initial interest rate before adjustments are made.
Some lenders may sell your loan after settlement. Any fees lenders receive in the future cannot change the loan you receive or the charges you paid at settlement.
Only you can shop for the best loan for you. Compare this GFE with other loan offers, so you can find the best loan. Use the shopping chart on page 3 to compare all the offers you receive.
Sources
[1] Good Faith Estimate (GFE), OMB Approval No. 2502-0265, U.S. Department of Housing and Urban Development (the Official source link on this page).
