

Form 500D at a glance
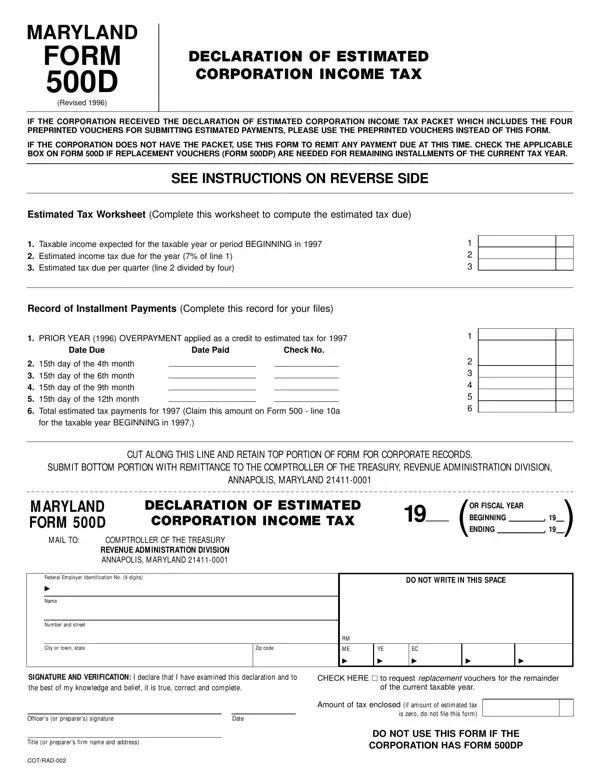
What it is: Form 500D, COM/RAD-002 05/25, 2026, is the Maryland Corporation Declaration of Estimated Income Tax, used by a corporation to declare and remit estimated income tax.
Where and when to file: Make check or money order payable to and mail to: Comptroller Of Maryland Revenue Administration Division 110 Carroll Street Annapolis, Maryland 21411-0001
Every corporation that reasonably expects its Maryland taxable income to develop a tax in excess of $1,000 for the tax year or period must make estimated income tax payments. (checked November 8, 2026)
Corporations expected to be subject to estimated tax requirements should use Form 500D to remit any payment due.
What to bring and attach to Form 500D
Include a check or money order made payable to Comptroller of Maryland.
DO NOT SEND CASH.
All payments must indicate the FEIN, type of tax and tax year beginning and ending dates. 3) Mailing Instructions Write your FEIN, tax type, and tax year on check or money order using blue or black ink. Failure to include this information will delay the processing of your payment.
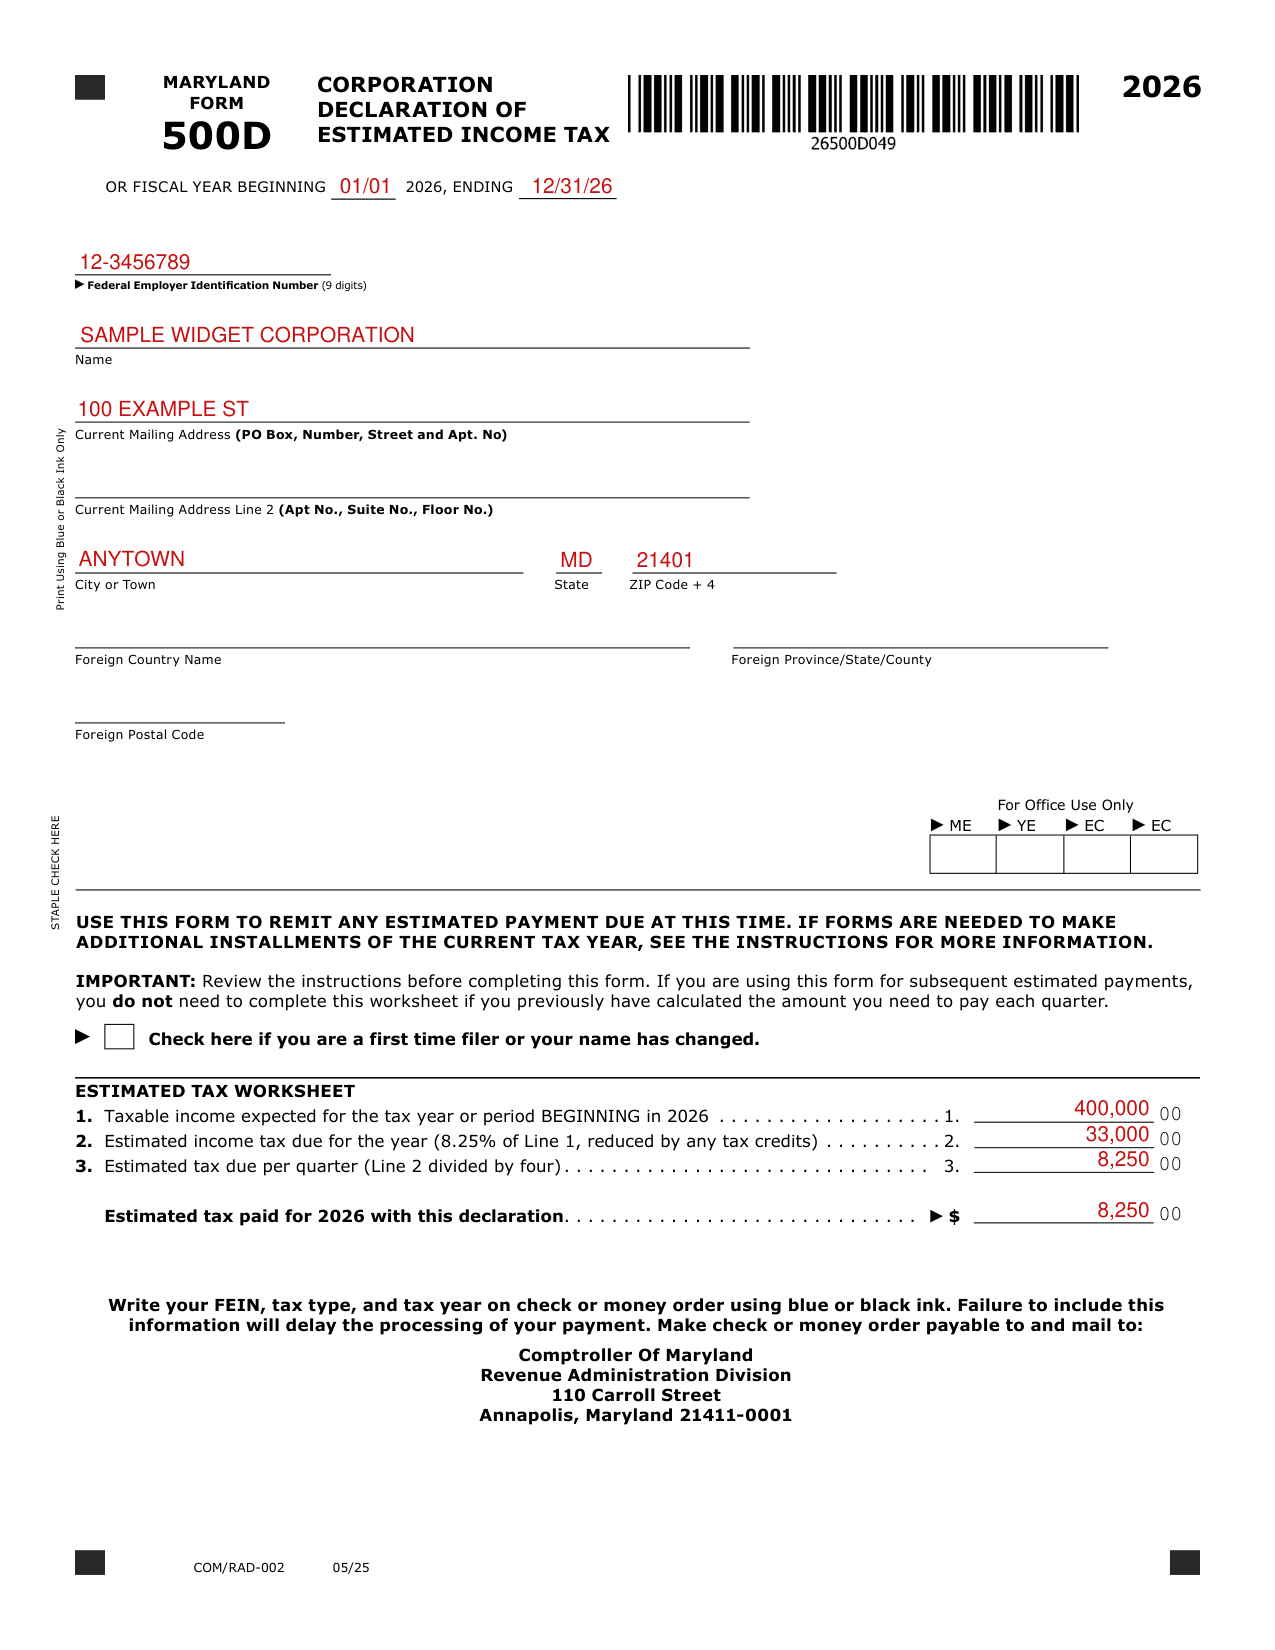
A filled-in Form 500D example: a corporation pays one quarter of its estimated tax
How to fill out Form 500D, box by box
Tax year or period

Enter the beginning and ending dates of the tax year in the space provided.
The same tax year or period used for the federal return must be used for Form 500D.
Federal Employer Identification Number and Name
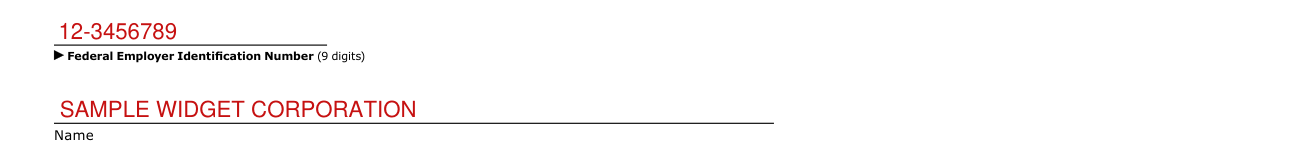
Enter the Federal Employer Identification Number (FEIN).
If the FEIN has not been secured, enter “APPLIED FOR” followed by the date of application.
If a FEIN has not been applied for, do so immediately.
Enter the name exactly as specified in the Articles of Incorporation, or as amended, and continue with any “Trading As” (T/A) name if applicable.
Current mailing address
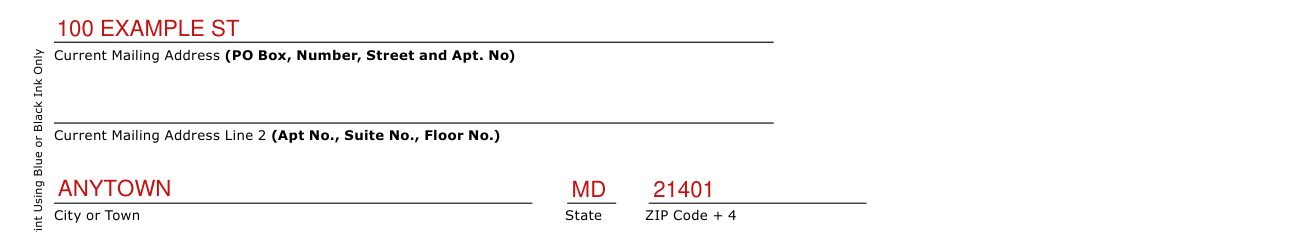
Type or print the required information in the designated area.
Print Using Blue or Black Ink Only in Current Mailing Address (PO Box, Number, Street and Apt. No), Current Mailing Address Line 2 (Apt No., Suite No., Floor No.), City or Town, State and ZIP Code + 4.
Foreign Country Name and Postal Code
If you enter a Foreign Country Name, fill in Foreign Province/State/County and Foreign Postal Code.
First time filer or name change

Check here if you are a first time filer or your name has changed.
Estimated tax worksheet

IMPORTANT: Review the instructions before completing this form. If you are using this form for subsequent estimated payments, you do not need to complete this worksheet if you previously have calculated the amount you need to pay each quarter.
Line 1: Taxable income expected for the tax year or period BEGINNING in 2026.
Line 2: Estimated income tax due for the year (8.25% of Line 1, reduced by any tax credits).
Line 3: Estimated tax due per quarter (Line 2 divided by four).
Estimated tax paid with this declaration

Estimated tax paid for 2026 with this declaration.
Enter the amount of estimated tax paid in the space provided.
More rules for Form 500D
The total estimated tax payments for the year must be at least 90% of the tax developed for the current year or 110% of the tax that was developed for the prior year to avoid interest and/or penalty.
At least 25% of the total estimated tax must be remitted by each of the installment due dates.
The annualization method for calculating estimated tax is not permitted for corporations.
Other situations
Your tax period is short
In the case of a short tax period, the total estimated tax payment required is the same as for a regular tax year: 90% of the tax developed for the current (short) tax year or 110% of the tax that was developed for the prior tax year.
The minimum estimated tax for each of the installment due dates is the total estimated tax required divided by the number of installment due dates occurring during the short tax year.
However, if the corporation has a short tax period of less than 4 months, it does not have to pay estimated tax nor file Form 500D.
If it is necessary to amend the estimate
If it is necessary to amend the estimate, recalculate the amount of estimated tax required using the estimated tax worksheet provided.
Adjust the amount of the next installment to reflect any previous underpayment or overpayment.
The remaining installments must be at least 25% of the amended estimated tax due for the year.
You file as an affiliated corporation
Consolidated returns are not allowed under Maryland law.
Affiliated corporations that file a consolidated federal return must file separate Maryland declarations for each member corporation.
Payments by electronic methods
1) Electronic Funds Transfer: taxpayers must register before using this method. To obtain a registration form, visit marylandcomptroller.gov or call 410-260-7980. If payment is made by electronic funds transfer, do not mail Form 500D; retain it with the company's records.
2) Filing Electronically: taxpayers may file using the Modernized Electronic Filing method (software provider must be approved by the IRS and Revenue Administration Division). If filed electronically, do not mail Form 500D; retain it with the company's records.
You need to make additional payments for the current tax year
If you need to make additional payments for the current tax year, you may file electronically, or visit marylandcomptroller.gov and download another Form 500D.
You had an overpayment from the prior year
In addition to payments with Form 500D, the corporation may partially or fully apply any overpayment from the prior year Form 500 - Maryland Corporation Income Tax Return to the estimated tax obligation for this year.
Common questions about Form 500D
Is there a deadline?
File Form 500D on or before the 15th day of the 4th, 6th, 9th, and 12th months following the beginning of the tax year or period.
Where do I file it?
Mail payment and completed Form 500D to: Comptroller of Maryland Revenue Administration Division 110 Carroll Street Annapolis, MD 21411-0001. Taxpayers making payments of $10,000 or more must use one of these two electronic methods: Electronic Funds Transfer or Filing Electronically. (checked November 8, 2026)
Is there a penalty?
Maryland law provides for the accrual of interest and imposition of penalty for failure to pay any tax when due.
When is this form not the right one?
NOTE: Do not use this form to remit estimated tax for Forms 510, 511 or to remit employer withholding tax.
Sources
[1] Form 500D (COM/RAD-002 05/25), Comptroller of Maryland (the Official source link on this page).