


Form TTD at a glance
What it is: Form TTD is the Asset Transfer Tax Declaration under N.J.S.A. 54:50-38, which instructs the Director, Division of Taxation, to notify the purchaser, transferee or assignee of business assets of any possible claim for State taxes.
Who signs: Line 12, Estimated Tax on Gain Due (line 10 multiplied by line 11). Will there be installment proceeds? Yes or No (if yes, give details on reverse side.) Taxpayer's Declaration: Taxpayer's Declaration: "I declare that all the information on this declaration is correct. I am aware that if any of the foregoing information provided by me is knowingly false, I am subject to punishment." Date, Owner/Partner/Member Signature, Print, Title.
A filled-in Form TTD example: a seller declares the gain on an asset sale
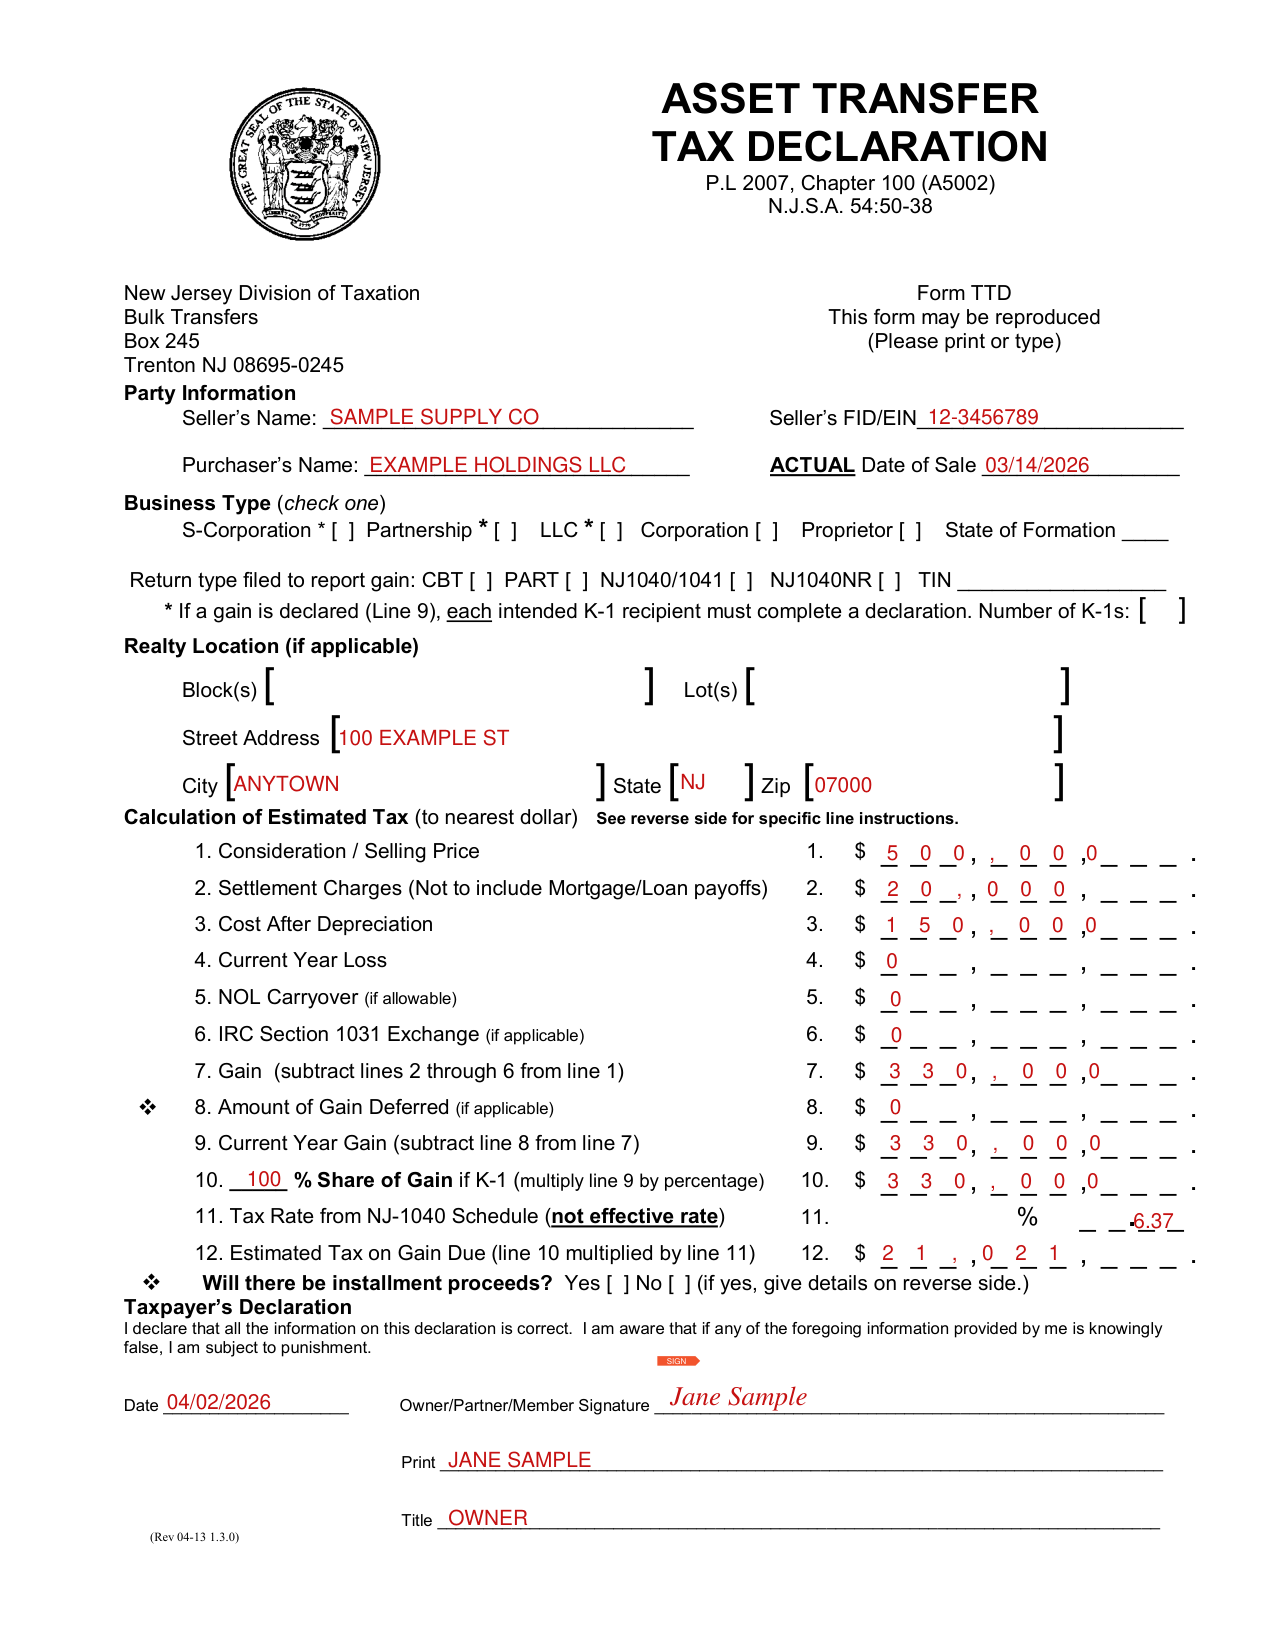
How to fill out Form TTD, box by box
Party Information
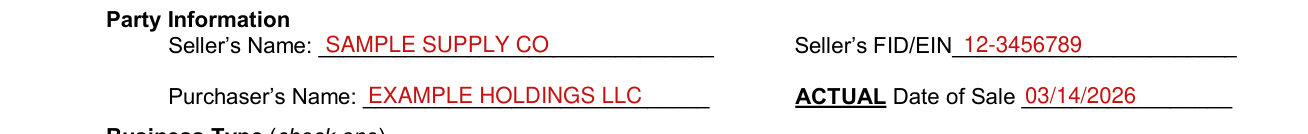
Under Party Information, enter the Seller's Name, Seller's FID/EIN, Purchaser's Name and ACTUAL Date of Sale.
Realty Location
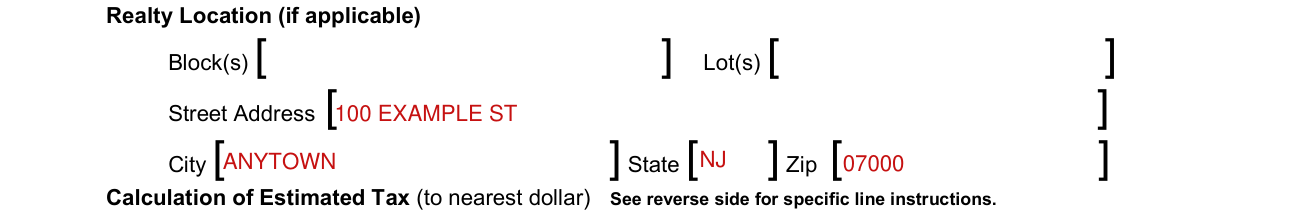
Under Realty Location (if applicable), enter Block(s), Lot(s), Street Address, City, State and Zip.
Calculation of Estimated Tax
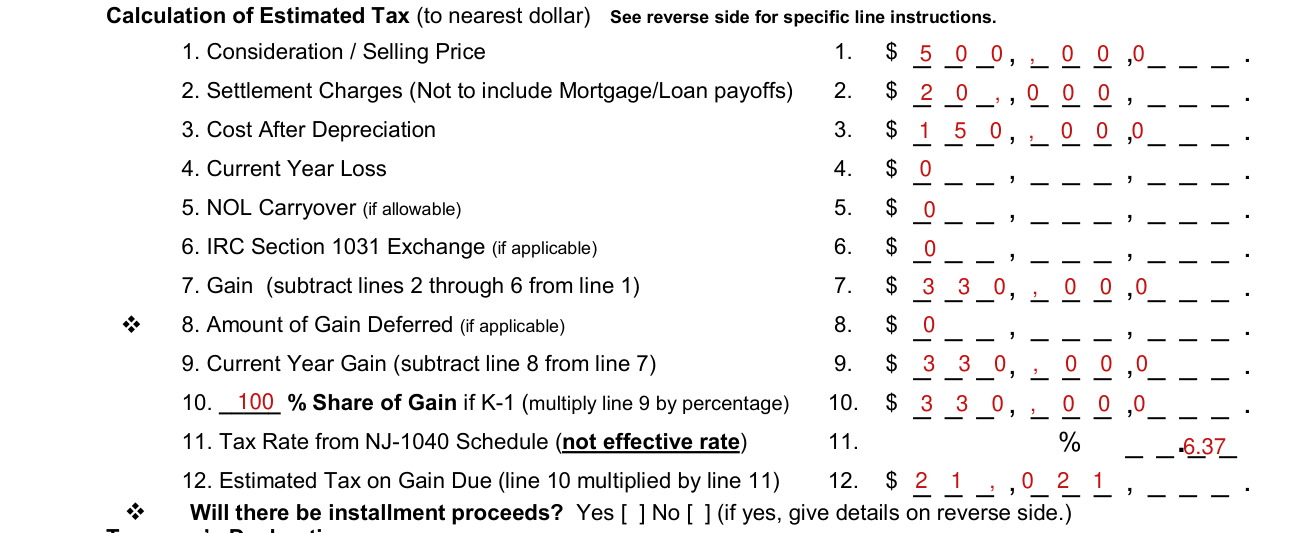
Line 1, Consideration / Selling Price: total sale price or consideration of all assets currently being transferred.
Line 2: Total amount of settlement charges to transferor associated with this transaction.
Line 2, Settlement Charges, is not to include Mortgage/Loan payoffs.
Line 3: If fully depreciated enter zero.
Line 7, Gain: subtract lines 2 through 6 from line 1.
Line 8: Calculate amount deferred based on installment or short term notes.
Line 9, Current Year Gain: subtract line 8 from line 7.
Line 9: For NJ1065 filers: If any member/partner is not an individual or if the number of nonresident member/partners exceeds five (5) stop here and attach the most current membership directory.
The Division will calculate and communicate the estimated tax for resident filers and/or withholding amount for nonresident filers.
Line 10, % Share of Gain if K-1: multiply line 9 by percentage.
Line 10 assigns share.
Line 11, Tax Rate from NJ-1040 Schedule (not effective rate): individual tax rates may be found in the most current NJ-1040 instructions.
Corporate tax rate 6.5% ($1-$50,000), 7.5% ($50,001-$100,000) or 9% (over $100,000). (checked November 14, 2026) Line 12: C-Corporation - use the greater of declared tax or minimum tax. ($500, $750, $1,000, $1,500 or $2,000 based on NJ Gross Receipts.) (checked November 14, 2026) S-Corporation - minimum tax applies in addition to any tax on gain.
More rules for Form TTD
Upon closing of the transaction, the escrow will be held by the transferee's attorney and the estimated tax on the gain portion of the escrow will be demanded by the Division to be applied to the appropriate tax type and year.
The taxpayer files their year end business tax return, claims credit for the payment and pays any additional tax due; they may request a refund or credit if an overpayment exists.
Sources
[1] Form TTD, Asset Transfer Tax Declaration (Rev 04-13 1.3.0), New Jersey Division of Taxation (the Official source link on this page).