

General Compilation Engagement Checklist 20,203 at a glance
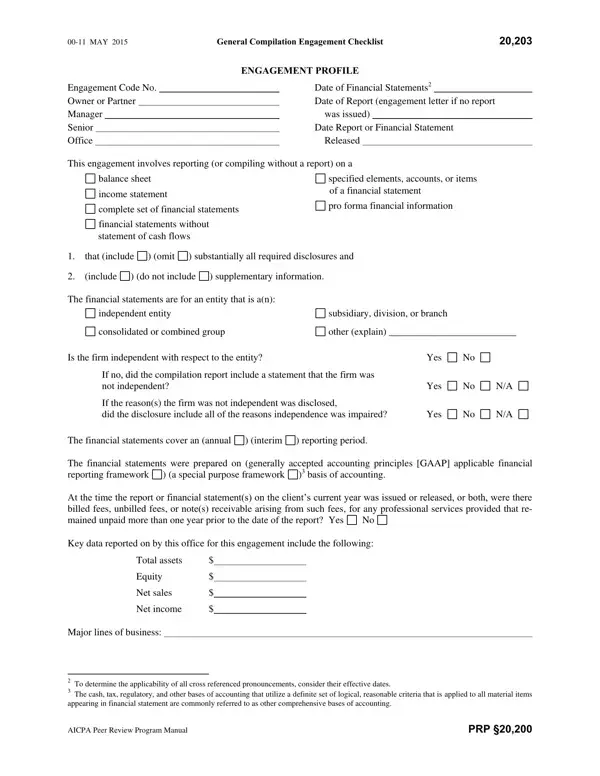
What it is: The General Compilation Engagement Checklist, with its ENGAGEMENT PROFILE, is part of the AICPA Peer Review Program Manual.
Who signs: Under SIGN, add the Reviewer Signature and the Team Captain Signature.
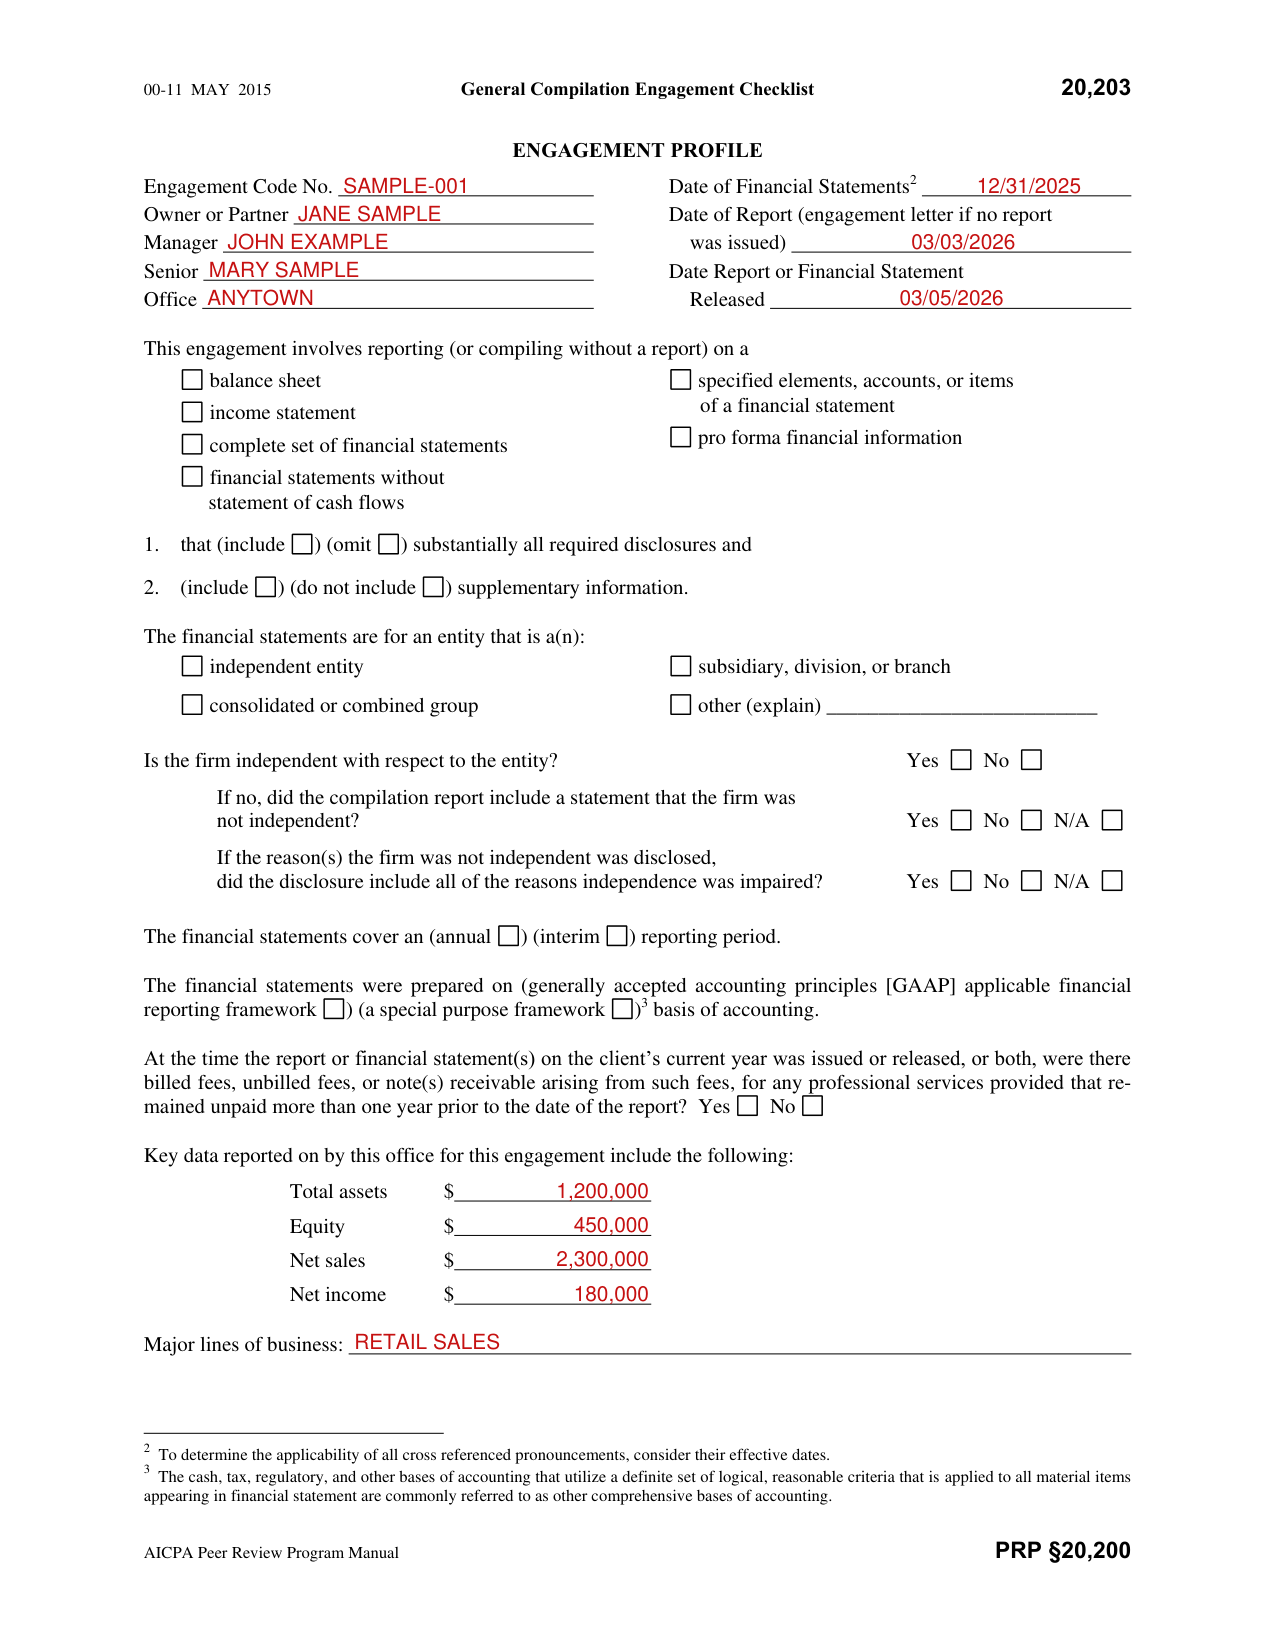
A filled-in General Compilation Engagement Checklist 20,203 example: a firm owner fills out the engagement profile
How to fill out General Compilation Engagement Checklist 20,203, box by box
ENGAGEMENT PROFILE and dates
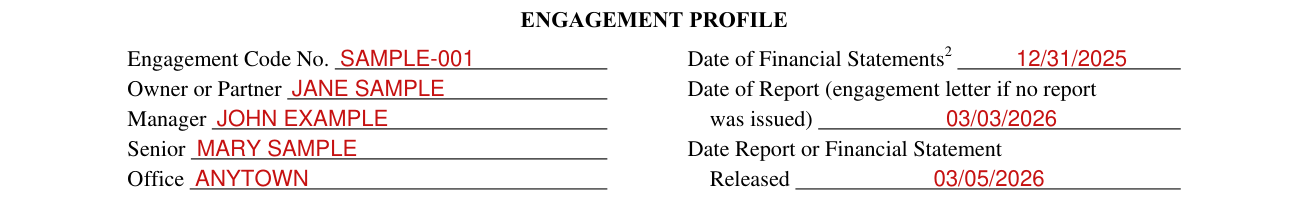
Under ENGAGEMENT PROFILE, enter the Engagement Code No., Owner or Partner, Manager, Senior and Office.
Enter the Date of Financial Statements, the Date of Report (engagement letter if no report was issued) and the Date Report or Financial Statement Released.
This engagement involves reporting, and the entity
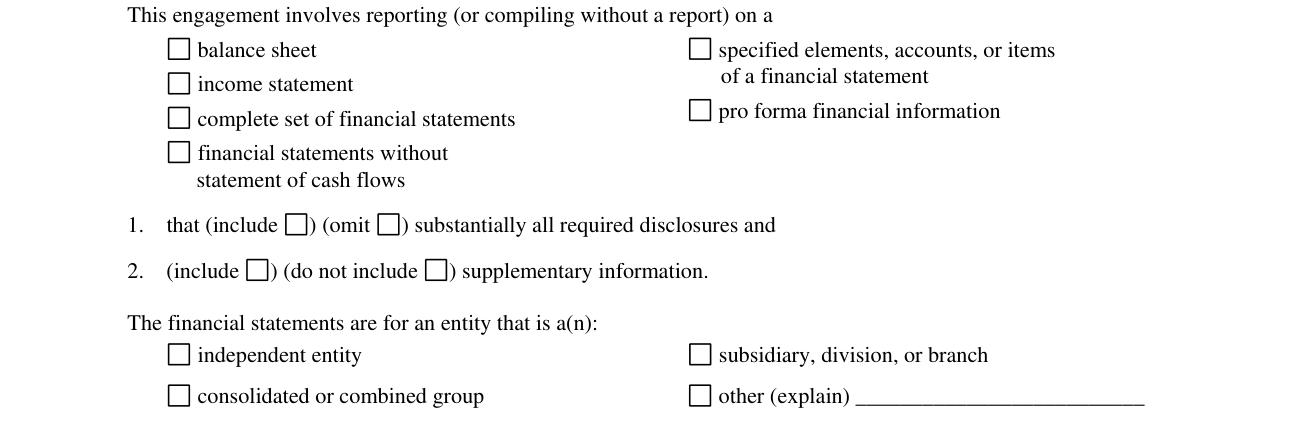
This engagement involves reporting (or compiling without a report) on a specified elements, accounts, or items of a financial statement, balance sheet, income statement, pro forma financial information, complete set of financial statements, or financial statements without statement of cash flows.
1. that (include) (omit) substantially all required disclosures and 2. (include) (do not include) supplementary information.
The financial statements are for an entity that is a(n): independent entity, subsidiary, division, or branch, consolidated or combined group, or other (explain).
Key data and major lines of business
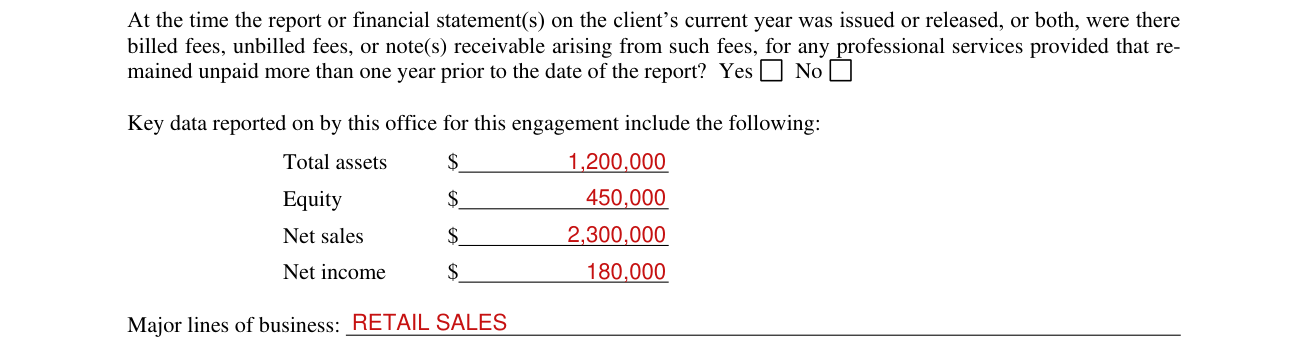
Enter Total assets, Equity, Net sales and Net income as the Key data reported on for this engagement.
Enter the Major lines of business.
Types of non-attest services for this client
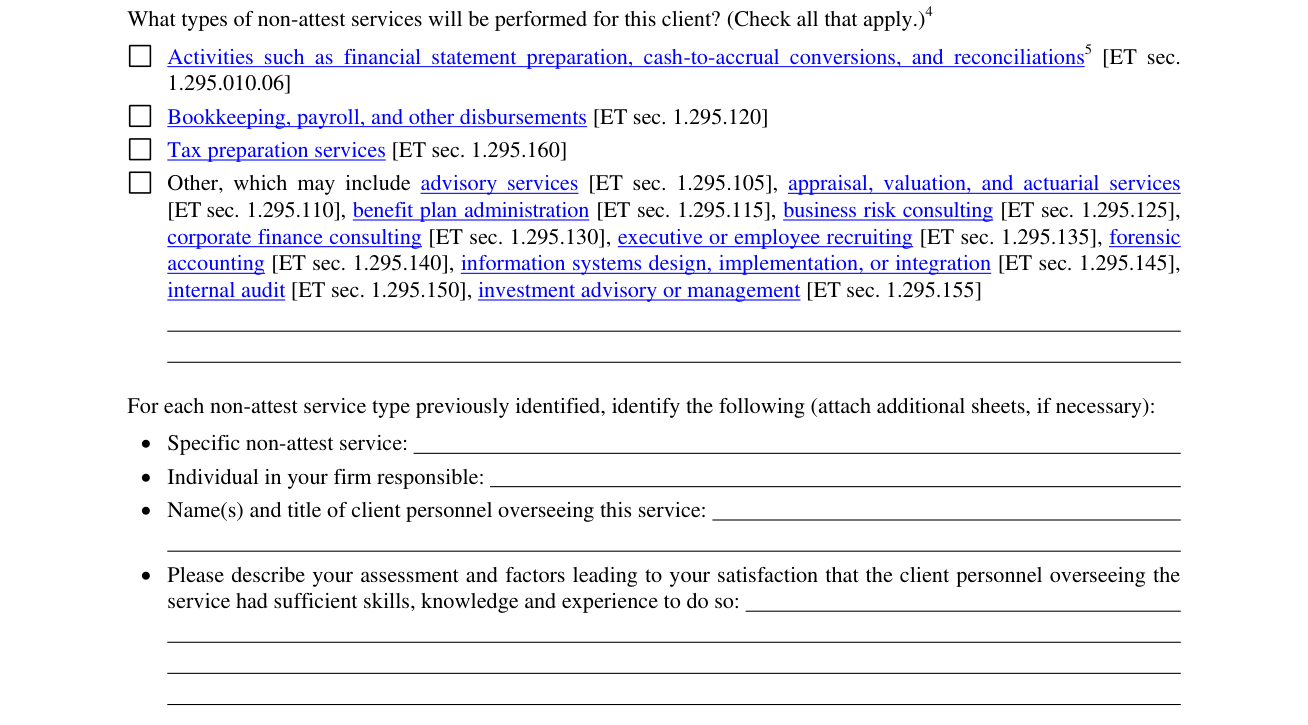
Check all that apply for the types of non-attest services that will be performed for this client: Activities such as financial statement preparation, cash-to-accrual conversions, and reconciliations [ET sec. 1.295.010.06]; Bookkeeping, payroll, and other disbursements [ET sec. 1.295.120]; Tax preparation services [ET sec. 1.295.160].
Other, which may include advisory services [ET sec. 1.295.105], appraisal, valuation, and actuarial services [ET sec. 1.295.110], benefit plan administration [ET sec. 1.295.115], business risk consulting [ET sec. 1.295.125], corporate finance consulting [ET sec. 1.295.130], executive or employee recruiting [ET sec. 1.295.135], forensic accounting [ET sec. 1.295.140], information systems design, implementation, or integration [ET sec. 1.295.145], internal audit [ET sec. 1.295.150], investment advisory or management [ET sec. 1.295.155].
Effective for periods beginning after December 15, 2014, activities such as financial statement preparation, cash-to-accrual conversions, and reconciliations are considered outside the scope of the attest engagement and, therefore, constitute a non-attest service.
For each non-attest service type previously identified, identify the following (attach additional sheets, if necessary):
Specific non-attest service, Individual in your firm responsible, and Name(s) and title of client personnel overseeing this service.
Please describe your assessment and factors leading to your satisfaction that the client personnel overseeing the service had sufficient skills, knowledge and experience to do so.
Non-attest services that involve leading and directing the entity
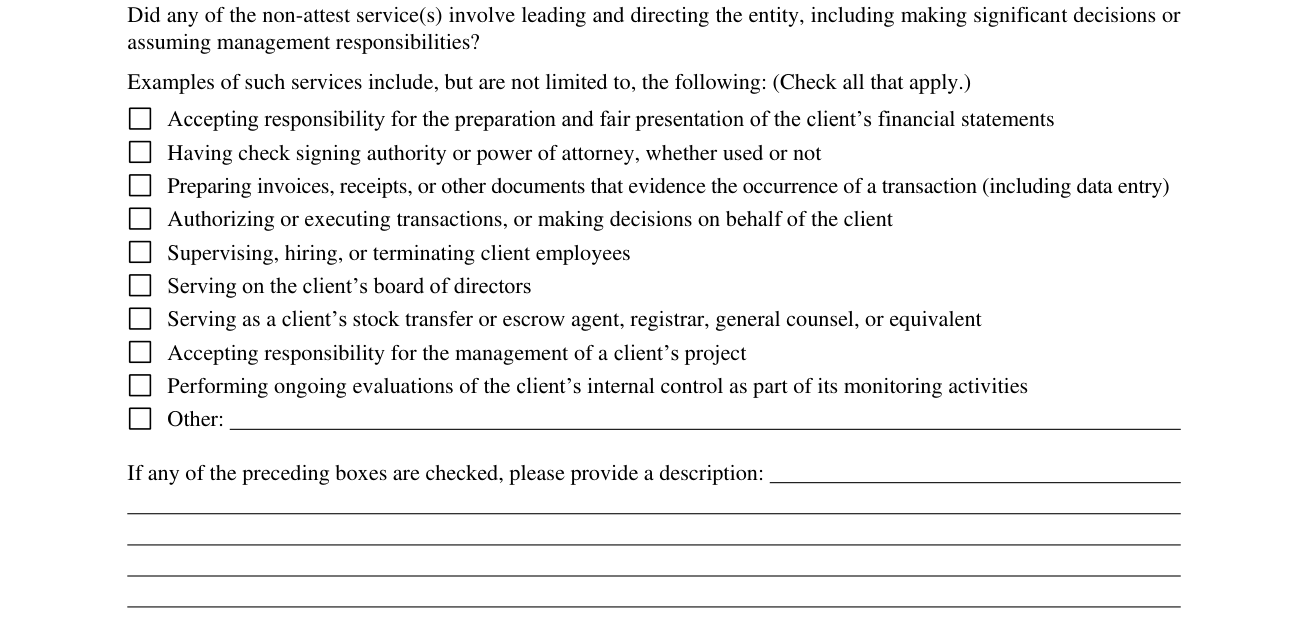
Did any of the non-attest service(s) involve leading and directing the entity, including making significant decisions or assuming management responsibilities?
Examples of such services include, but are not limited to, the following (check all that apply): Accepting responsibility for the preparation and fair presentation of the client's financial statements; Having check signing authority or power of attorney, whether used or not; Preparing invoices, receipts, or other documents that evidence the occurrence of a transaction (including data entry); Authorizing or executing transactions, or making decisions on behalf of the client; Supervising, hiring, or terminating client employees; Serving on the client's board of directors; Serving as a client's stock transfer or escrow agent, registrar, general counsel, or equivalent; Accepting responsibility for the management of a client's project; Performing ongoing evaluations of the client's internal control as part of its monitoring activities; Other.
If any of the preceding boxes are checked, please provide a description.
Engagement areas and compilation hours
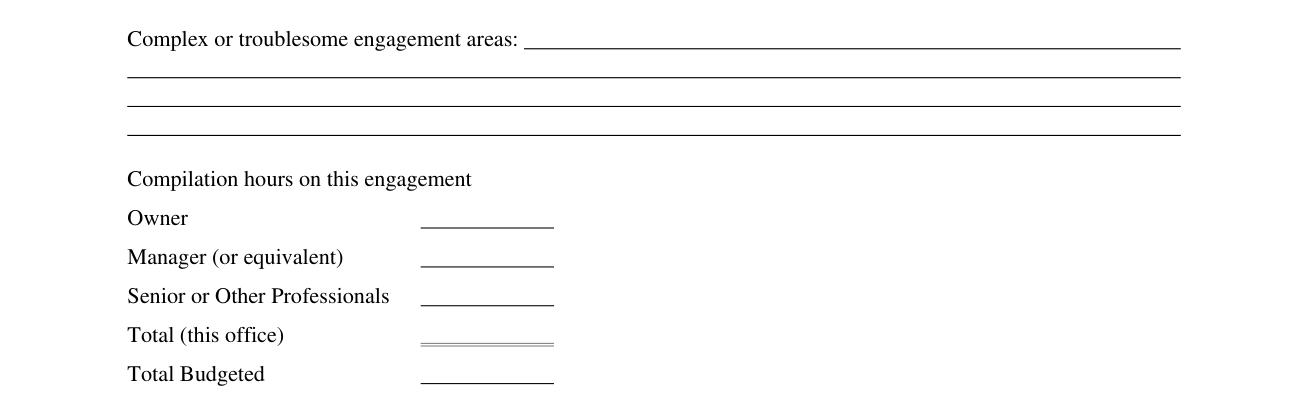
Enter the Complex or troublesome engagement areas.
Under Compilation hours on this engagement, enter the hours for Owner, Manager (or equivalent), Senior or Other Professionals, the Total and Total Budgeted.
Personnel Continuity, review dates and SIGN
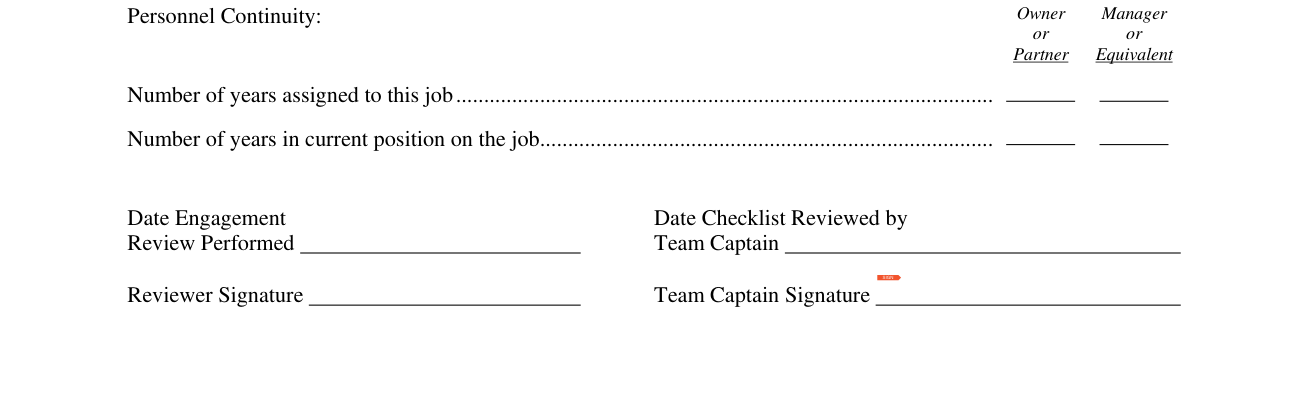
Under Personnel Continuity, for the Owner or Partner and the Manager or Equivalent, enter the Number of years assigned to this job and the Number of years in current position on the job.
Enter the Date Engagement Review Performed and the Date Checklist Reviewed by Team Captain.
Under SIGN, add the Reviewer Signature and the Team Captain Signature.
More rules for General Compilation Engagement Checklist 20,203
Is the firm independent with respect to the entity? Yes No. If no, did the compilation report include a statement that the firm was not independent? Yes No N/A. If the reason(s) the firm was not independent was disclosed, did the disclosure include all of the reasons independence was impaired? Yes No N/A.
The financial statements cover an annual or interim reporting period.
The financial statements were prepared on a generally accepted accounting principles [GAAP] applicable financial reporting framework or a special purpose framework basis of accounting. 2 To determine the applicability of all cross referenced pronouncements, consider their effective dates. 3 The cash, tax, regulatory, and other bases of accounting that utilize a definite set of logical, reasonable criteria that is applied to all material items appearing in financial statement are commonly referred to as other comprehensive bases of accounting.
At the time the report or financial statement(s) on the client's current year was issued or released, or both, were there billed fees, unbilled fees, or note(s) receivable arising from such fees, for any professional services provided that remained unpaid more than one year prior to the date of the report? Yes No.
4 To determine the applicability of all cross-referenced Code sections, consider their effective dates.
Sources
[1] General Compilation Engagement Checklist 20,203 (MAY 2015), AICPA Peer Review Program Manual PRP §20,200 (the Official source link on this page).