

Form ST-125 at a glance
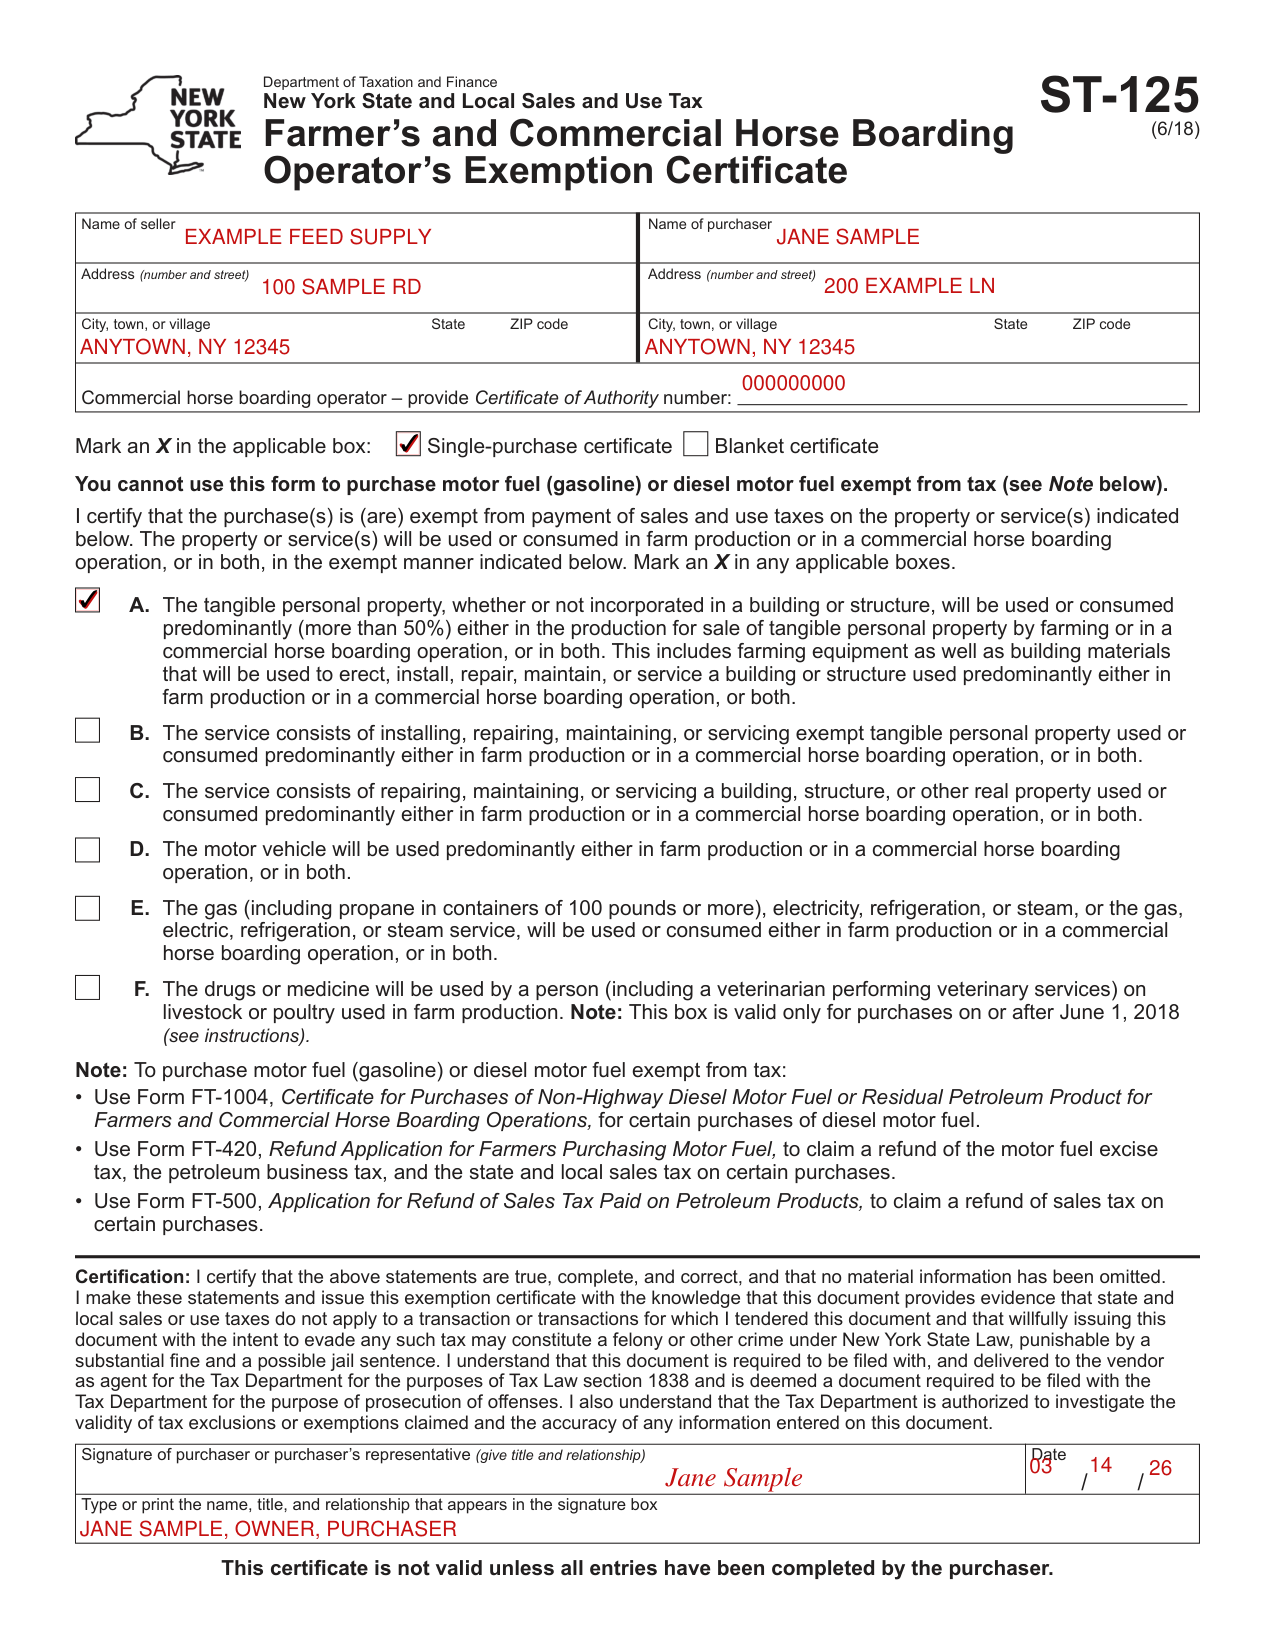
What it is: Form ST-125 is the Department of Taxation and Finance New York State and Local Sales and Use Tax Farmer's and Commercial Horse Boarding Operator's exemption form.
Who signs: The purchaser or purchaser's representative signs and enters the date; give title and relationship.
A filled-in Form ST-125 example: a horse boarding operator buys stall mats
How to fill out Form ST-125, box by box
Seller and purchaser
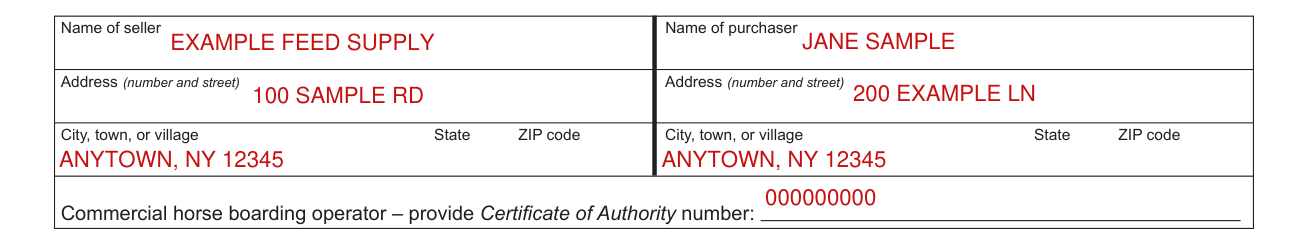
Enter the name of seller and the name of purchaser, each with an address (number and street) and a city, town, or village, state, and ZIP code.
Commercial horse boarding operator

Commercial horse boarding operator: provide the Certiicate of Authority number.
Single-purchase or Blanket

Mark an X in the applicable box: Single-purchase or Blanket.
A blanket certiicate remains in effect until the purchaser gives you written notice of revocation, or until the Tax Department notiies you that the purchaser may not make exempt purchases.
Boxes A to F, how the property or service will be used
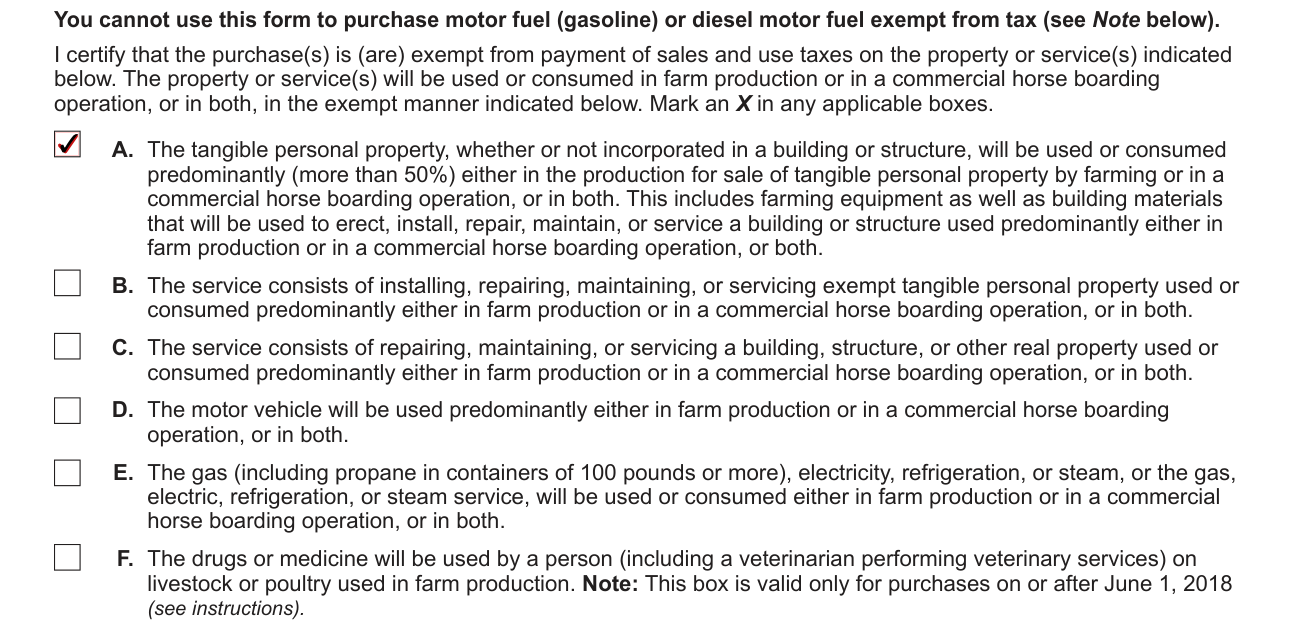
The purchaser certifies that the purchases are exempt from payment of sales and use taxes on the property or services indicated. The property or services will be used or consumed in farm production or in a commercial horse boarding operation, or in both, in the exempt manner indicated. Mark an X in any applicable boxes.
A. The tangible personal property, whether or not incorporated in a building or structure, will be used or consumed predominantly (more than 50%) either in the production for sale of tangible personal property by farming or in a commercial horse boarding operation, or in both. This includes farming equipment as well as building materials that will be used to erect, install, repair, maintain, or service a building or structure used predominantly either in farm production or in a commercial horse boarding operation, or both.
B. The service consists of installing, repairing, maintaining, or servicing exempt tangible personal property used or consumed predominantly either in farm production or in a commercial horse boarding operation, or in both.
C. The service consists of repairing, maintaining, or servicing a building, structure, or other real property used or consumed predominantly either in farm production or in a commercial horse boarding operation, or in both.
D. The motor vehicle will be used predominantly either in farm production or in a commercial horse boarding operation, or in both.
E. The gas (including propane in containers of 100 pounds or more), electricity, refrigeration, or steam, or the gas, electric, refrigeration, or steam service, will be used or consumed either in farm production or in a commercial horse boarding operation, or in both.
F. The drugs or medicine will be used by a person (including a veterinarian performing veterinary services) on livestock or poultry used in farm production. Note: This box is valid only for purchases on or after June 1, 2018.
Common mistake: Box F is not valid for purchases of drugs or medicine made before June 1, 2018, and the purchaser must use Form AU-11, Application for Credit or Refund of Sales and Use Tax, to request a refund or credit of any sales taxes paid for such purchases.
Farm production means the production of tangible personal property for sale by farming.
Predominantly means more than 50%, measured, for example, by hours of usage or by miles traveled.
Commercial horse boarding operation means an agricultural enterprise of at least seven acres and boarding at least 10 horses, regardless of ownership, that receives $10,000 or more in gross receipts annually from fees generated either through the boarding of horses or through the production for sale of crops, livestock, and livestock products, or through both such boarding and such production. Under no circumstances shall this include an operation whose primary on-site function is horse racing. (checked October 21, 2026)
The signature box
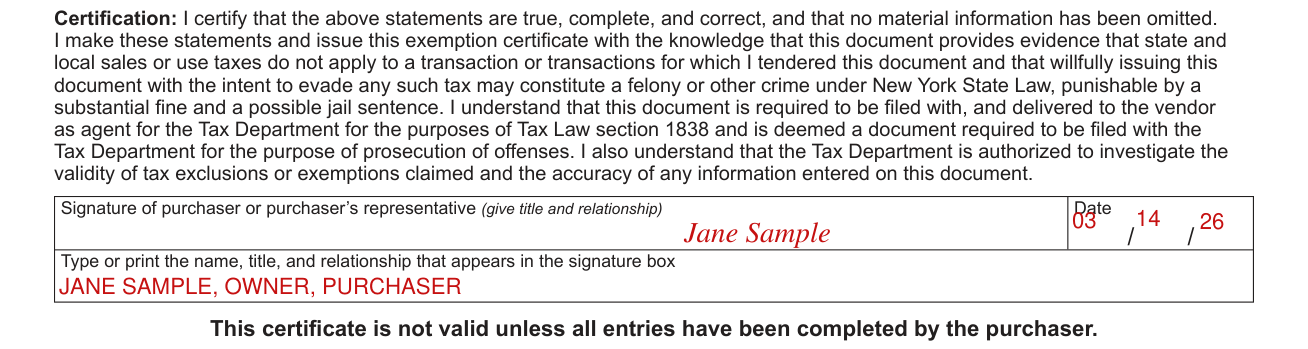
You certify that the statements are true, complete, and correct, and that no material information has been omitted. You make these statements with the knowledge that this document provides evidence that state and local sales or use taxes do not apply to a transaction for which you tendered this document and that willfully issuing this document with the intent to evade any such tax may constitute a felony or other crime under New York State Law. You understand that this document is required to be delivered to the vendor as agent for the Tax Department for the purposes of Tax Law section 1838, and that the Tax Department is authorized to investigate the validity of tax exclusions or exemptions claimed and the accuracy of any information entered on this document.
Type or print the name, title, and relationship that appears in the signature box.
Common mistake: This is not valid unless all entries have been completed by the purchaser.
More rules for Form ST-125
Misuse of this exemption may subject you to serious civil and criminal sanctions in addition to the payment of any tax and interest due.
To the seller
To the seller
To the seller: When making purchases that qualify for exemption from sales and use tax, the purchaser must provide you with this exemption with all entries completed to establish the right to the exemption.
As a New York State registered vendor, you may accept an exemption certiicate in lieu of collecting tax and be protected from liability for the tax if the certiicate is valid. The certiicate will be considered valid if it is: accepted in good faith; in your possession within 90 days of the transaction; and properly completed (all required entries were made).
An exemption certiicate is accepted in good faith when you have no knowledge that the exemption certiicate is false or is fraudulently given, and you exercise reasonable ordinary due care.
Failure to collect sales or use tax, as a result of accepting an improperly completed exemption or receiving it more than 90 days after the sale, will make you personally liable for the tax plus any penalty and interest charges due.
If the blanket certiicate box is marked, you may consider this certiicate part of any order received from the purchaser during the period that the blanket certiicate remains in effect.
You must maintain a method of associating an invoice (or other source document) for an exempt sale with the exemption document from the purchaser. You must keep this document at least three years after the due date of your sales tax return to which it relates, or the date the return was iled, if later.
Common questions about Form ST-125
Is there a deadline?
If you do not receive a properly completed certiicate within 90 days after the delivery of the property or service, you will share with the purchaser the burden of proving the sale was exempt.
Is there a penalty?
These include: a penalty equal to 100% of the tax due; a $50 penalty for each fraudulent exemption issued; criminal felony prosecution; and revocation of your authority, if you are required to be registered as a vendor. (checked October 21, 2026)
When is this form not the right one?
You cannot use this form to purchase motor fuel (gasoline) or diesel motor fuel exempt from tax. To purchase motor fuel (gasoline) or diesel motor fuel exempt from tax: Use Form FT-1004 for certain purchases of diesel motor fuel. Use Form FT-420, Refund Application for Farmers Purchasing Motor Fuel, to claim a refund of the motor fuel excise tax, the petroleum business tax, and the state and local sales tax on certain purchases. Use Form FT-500, Application for Refund of Sales Tax Paid on Petroleum Products, to claim a refund of sales tax on certain purchases.
Sources
[1] Form ST-125 (6/18), Farmer's and Commercial Horse Boarding Operator's Exemption Certificate, New York State Department of Taxation and Finance (the Official source link on this page).
