

Form TP-584.1 at a glance
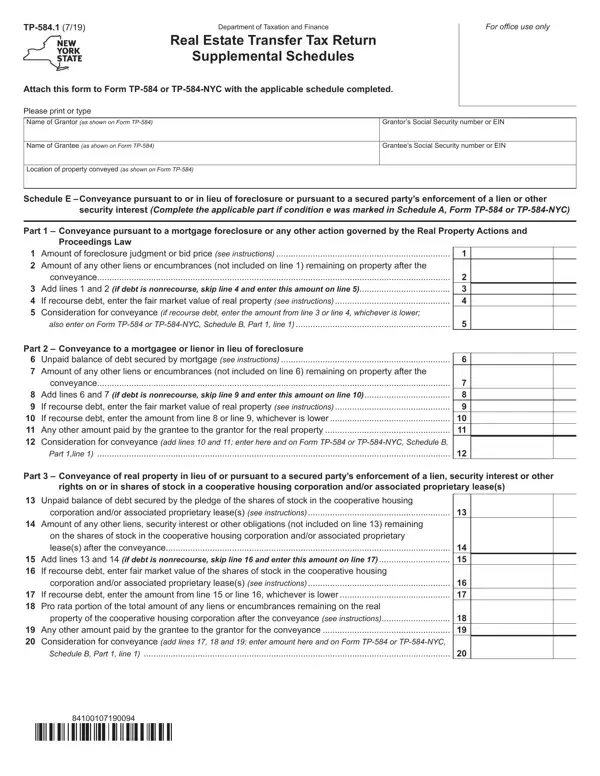
What it is: TP-584.1 is the Real Estate Transfer Tax Return Supplemental Schedules from the Department of Taxation and Finance.
Instructions, Purpose of Form TP-584.1 (7/19), page 3: This form must be completed and filed with Form TP-584 or TP-584-NYC for all conveyances that are pursuant to or in lieu of foreclosure or any other action governed by the Real Property Actions and Proceedings Law and for conveyances pursuant to a secured party's enforcement of a lien or other security interest, except for such conveyances where part of the debt is recourse and part of the debt is nonrecourse (see Schedule E), for conveyances that consist in whole or in part of a mere change of identity or form of ownership or organization (see Schedule F), and for conveyances for which a credit will be claimed for tax previously paid (see Schedule G).
A filled-in Form TP-584.1 example: a company reports a mere change of ownership
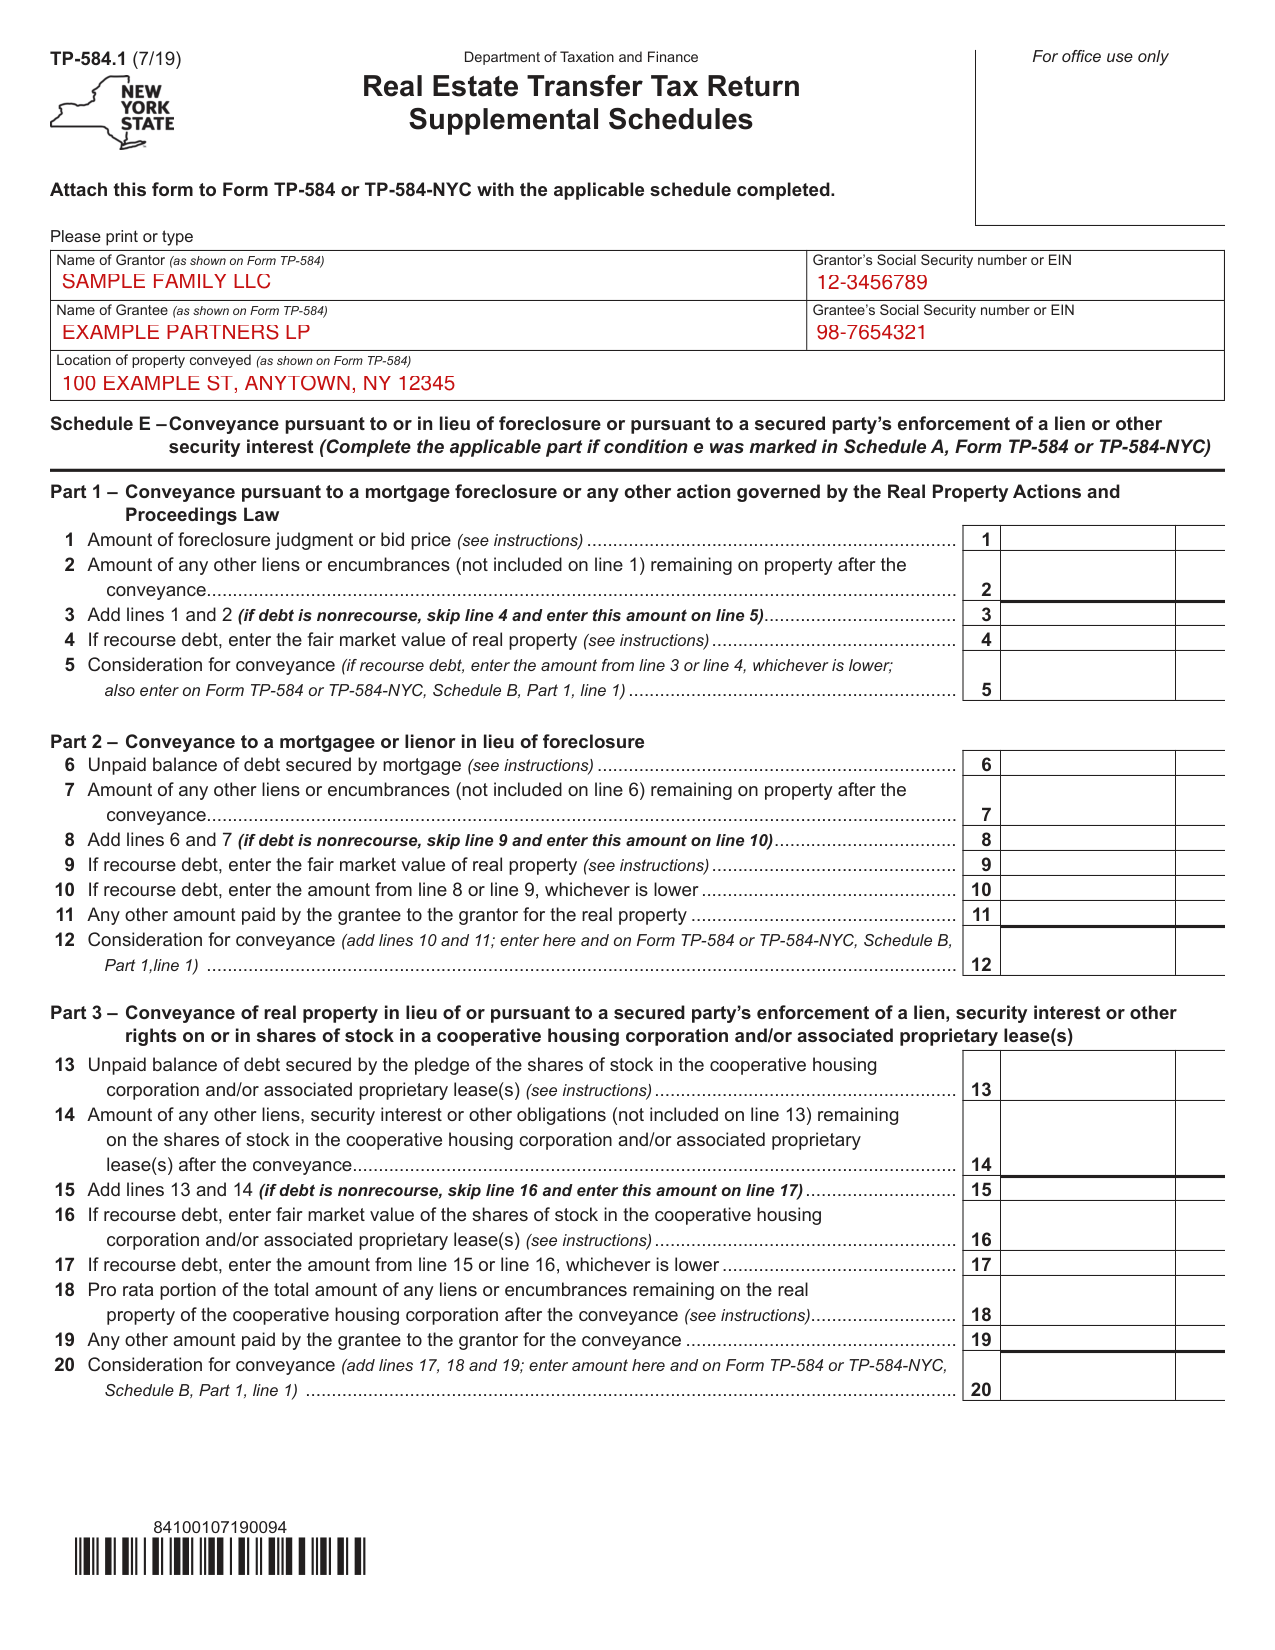
How to fill out Form TP-584.1, box by box
Name of Grantor, Name of Grantee and Location of property conveyed
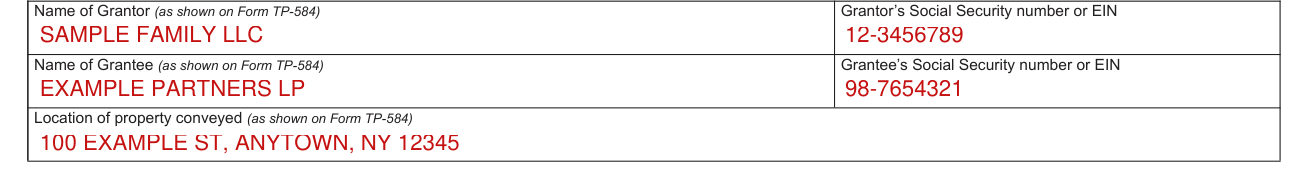
Please print or type the Name of Grantor (as shown on Form TP-584) and the Grantor's Social Security number or EIN, the Name of Grantee (as shown on Form TP-584) and the Grantee's Social Security number or EIN, and the Location of property conveyed (as shown on Form TP-584).
Schedule E, Part 1: conveyance pursuant to a mortgage foreclosure
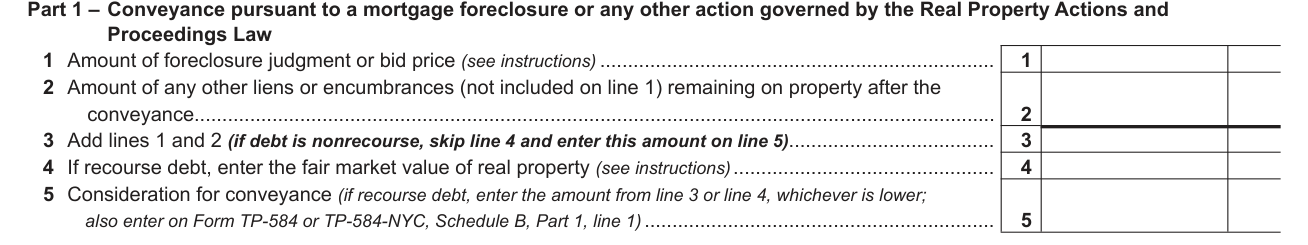
Part 1 Line 1 - If real property is being conveyed pursuant to a mortgage foreclosure or any other action governed by the Real Property Actions and Proceedings Law and the grantee is the mortgagee or lienor, its agent, nominee or an entity wholly owned by the mortgagee or lienor, enter the amount of judgment of foreclosure or the bid price, whichever is higher. The amount of judgment of foreclosure includes any interest accrued through the date of transfer. If the grantee is a person unrelated to the mortgagee or lienor, regardless whether the debt is recourse or nonrecourse, enter the bid price. Line 2 - Enter the amount of any continuing liens. Do not include the amount of any liens or encumbrances included on line 1.
Line 3 - Add lines 1 and 2. If debt is nonrecourse or if the grantee is a person unrelated to the mortgagee or lienor, skip line 4 and enter the line 3 amount on line 5. Line 4 - Where the debt is recourse debt and the grantee is the mortgagee or lienor, its agent, nominee or an entity wholly owned by the mortgagee or lienor, enter the fair market value of the real property.
Line 5 - If debt is recourse, enter line 3 or line 4, whichever is lower. If debt is nonrecourse or if the grantee is a person unrelated to the mortgagee or lienor, enter the amount from line 3. This is the amount of consideration to be entered on Form TP-584 or TP-584-NYC, Schedule B, Part 1, line 1. Attach a copy of the referee's report of sale, if available.
Schedule E, Part 2: conveyance to a mortgagee or lienor in lieu of foreclosure
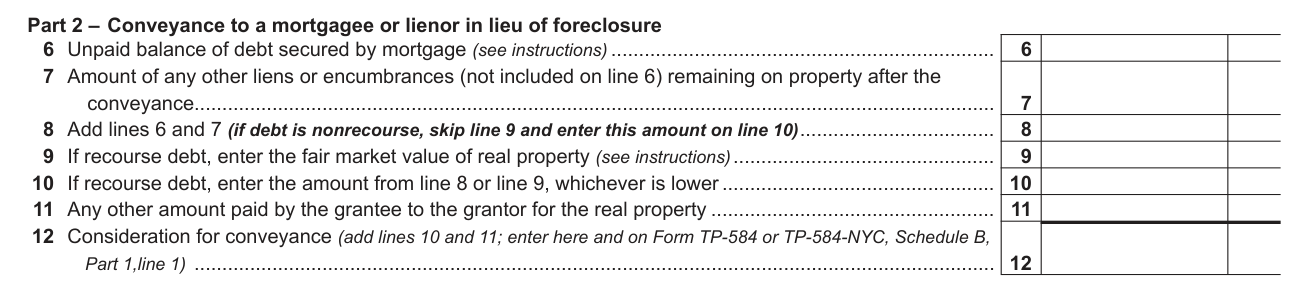
Part 2 Line 6 - If real property is being conveyed to a mortgagee or lienor, or its agent, nominee or an entity wholly owned by the mortgagee or lienor, in lieu of an action to foreclose a mortgage or lien, enter the unpaid balance of the debt secured by the mortgage or lien. The unpaid balance of the debt includes the principal, interest and other accruals secured by the mortgage or lien. Line 7 - Enter the amount of any continuing liens. Do not include the amount of any liens or encumbrances included on line 6.
Line 8 - Add lines 6 and 7. If debt is nonrecourse, skip line 9 and enter the line 8 amount on line 10. Line 9 - Where the debt is recourse, and the grantee is the mortgagee or lienor, its agent, nominee or an entity wholly owned by the mortgagee or lienor, enter the fair market value of the real property.
Line 10 - If debt is recourse, enter the amount from line 8 or line 9, whichever is lower. If debt is nonrecourse, enter the amount from line 8. Line 11 - Enter any other amount paid by the grantee to the grantor for the real property. Line 12 - Add lines 10 and 11.
Schedule F: mere change of identity or form of ownership or organization
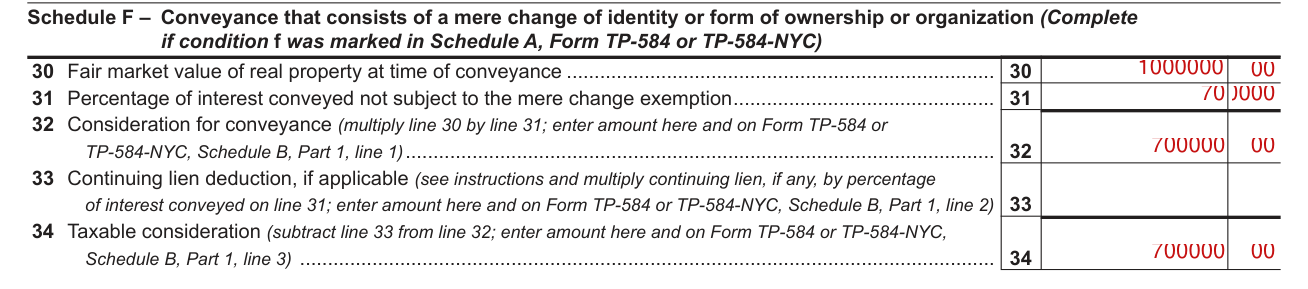
Schedule F Tax Law section 1405(b)6 provides exemption from the real estate transfer tax to the extent a conveyance consists in whole or in part of a mere change of identity or form of ownership or organization where there is no change in beneficial interest. To determine the consideration for the conveyance, multiply the fair market value of the real property at the time of conveyance by the percentage of interest not subject to the mere change exemption. When determining the taxable consideration, the consideration may be reduced by the amount of continuing liens remaining on the property at the time of conveyance multiplied by the percentage of interest not subject to the mere change exemption.
Generally, the fair market value of the real property is to be determined by appraisal. It is the amount a willing buyer would pay a willing seller for the real property. It is not the net fair market value, which deducts mortgages on the property from fair market value.
Line 30 - Enter the fair market value of the real property at the time of the conveyance. Attach evidence to support the fair market value.
Line 31 - Enter the percentage that represents the change in beneficial ownership. Round the percentage to four decimal places.
Line 32 - Multiply line 30 by line 31. This is the consideration for the conveyance. Enter this amount on Form TP-584 or TP-584-NYC, Schedule B, Part 1, line 1.
Line 33 - Enter the proportionate amount, if any, of the continuing lien deduction. The proportionate amount of continuing liens means the amount of any continuing lien multiplied by the percentage not subject to the mere change exemption. Enter this amount on Form TP-584 or TP-584-NYC, Schedule B, Part 1, line 2. A continuing lien is a mortgage or lien on the real property assumed or taken subject to and not an acquisition mortgage or lien placed on the real property by the grantee upon acquisition of the real property. See page 2 of Form TP-584-I or TP-584-NYC-I for additional criteria that must be met to claim the continuing lien deduction.
Line 34 - Subtract line 33 from line 32. This is the taxable consideration. Enter this amount on Form TP-584 or TP-584-NYC, Schedule B, Part 1, line 3.
Before you go
Attach this form to Form TP-584 or TP-584-NYC with the applicable schedule completed.
Complete the applicable part of Schedule E if condition e was marked in Schedule A, Form TP-584 or TP-584-NYC.
Pursuant to section 575.11(a)(2)(ii) of the real estate transfer tax regulations, a debt is recourse debt to the extent that, as of the date of conveyance, the grantor or a person related to the grantor, including any guarantor, bears the economic risk of loss for the debt beyond any loss attributable to the value of the property securing the debt.
Common questions about Form TP-584.1
When is this form not the right one?
Where the grantee is the mortgagee or lienor, as in the type of conveyances described in Parts 1 and 2 or the secured party, as in the type of conveyances described in Parts 3 and 4, or its agent, nominee or an entity wholly owned by such mortgagee, lienor or secured party, Schedule E may be used only if the debt, including continuing liens, is either all recourse or all nonrecourse. If the debt is not either all recourse or all nonrecourse, do not use Schedule E. Attach a separate schedule setting forth the method of computation.
Sources
[1] Form TP-584.1 (7/19), Real Estate Transfer Tax Return Supplemental Schedules, Department of Taxation and Finance (the Official source link on this page).