
Updated:
An appraisal contingency addendum is an attachment to a home purchase agreement. It lets the buyer end the purchase if the home appraises for less than the agreed price. Create yours online with the FormsPal template below, or download a PDF or Word file.
Build Your Document
Answer a few simple questions to make your document in minutes
Save and Print
Save progress and finish on any device, download and print anytime
Sign and Use
Your valid, lawyer-approved document is ready
An appraisal contingency addendum is a short attachment to a real estate purchase contract that lets the buyer cancel the sale if the home appraises below the contract price. You may also see it called an appraisal addendum, or an appraisal contingency addendum to the agreement of sale.
It is one kind of addendum to real estate purchase contract. It does not replace the home purchase agreement. It adds one condition to that agreement: the appraised value has to support the price, or the buyer gets a way out.
Most lenders order an appraisal before they approve a mortgage, and you have no control over the value that the appraiser assigns. The addendum deals with that uncertainty before it becomes a problem at closing.
An appraisal contingency works by tying the buyer’s duty to close to the appraised value, so a value below the contract price gives the buyer a choice instead of an obligation. The sequence below is the usual path through a deal.
Example with made-up figures: a buyer signs a contract at $400,000 and the home appraises at $385,000, a gap of $15,000. The buyer can ask the seller to come down to $385,000, bring $15,000 more in cash, or send written notice and cancel under the addendum.
An appraisal contingency addendum helps most when a buyer is financing the home and is unsure whether the appraised value will reach the agreed price. It acts as a safety net in these situations:
An appraisal contingency is not right for every purchase, and buyers most often skip it when they can cover a low appraisal themselves or when the appraised value matters less to the deal. Here are the common cases.
Think about your own situation before you decide to waive it. Without the contingency, you lose the safety net that protects you from buying a property that is not worth what you hoped. An FHA or VA loan can also bring its own appraisal clause into the contract, so ask your lender before you waive.
When an appraisal comes in low, the buyer and seller can question the value, change the price, change the cash in the deal, or end the sale under the contingency. That gap can cause major problems for the buyer and for the lender carrying the loan.
Either party can seek a different appraiser to look at the value of the property, but a value that a party obtains may not bind the lender, so the addendum should say which appraisal counts. If the new figure is low as well, each side has its own options.
A buyer facing a low appraisal can pay more, push back on the value, ask for a lower price, or leave the deal. Pick the one that fits your budget, your lender and how much you want the home.
A seller facing a low appraisal has fewer options than the buyer, and most of them cost money or time. A homeowner can take one of these routes:
Extending financing carries the most risk, because the seller ends up holding a loan on a home that appraised below its price. It can also bring legal duties: 12 CFR 1026.36(a)(4) and 12 CFR 1026.36(a)(5) list the criteria a seller financer meets to fall outside the federal term “loan originator”. The seller’s own mortgage matters too: under 12 CFR 191.2(b), a due-on-sale clause lets the lender, at its option, call the loan due if the property is sold or transferred without the lender’s prior written consent. A seller who wants the sale to close usually renegotiates the price.
An appraisal contingency addendum should name the buyer, the seller, the property and the purchase agreement, then set out how the buyer can cancel and by when. Your situation might call for more, but these are the basic items:
The appraisal contingency addendum consists of the buyer’s right to terminate the contract if the appraised value is less than the purchase price. In this case, the buyer will have to provide the seller with a written notice. What happens to the earnest money deposit then depends on the contract and the addendum, which should say that it goes back to the buyer. An escrow or closing agent, rather than the seller, may be the one holding it.
What follows when the buyer gives no notice is up to the addendum’s own wording. An addendum can treat the contingency as satisfied if the buyer gives no notice by its date, and the sale then proceeds.
To write an appraisal contingency, name the price being tested, the event that lets the buyer cancel, how the buyer gives notice, and what happens to the deposit. The sample below shows one way to phrase those points, and it is separate from the wording of the FormsPal template.
Example only, with made-up details: “Buyer’s duty to purchase 12 Sample Street depends on an appraised value of at least $400,000, the Purchase Price, in the appraisal ordered by Buyer’s lender. If that appraised value is lower, Buyer shall send Seller the appraisal and a written notice within 10 days of receiving it. If Buyer sends no notice within those 10 days, this contingency is deemed satisfied. After a timely notice, Seller has 4 days to reduce the Purchase Price to the appraised value. If Seller does not, Buyer may terminate this Agreement by written notice sent within 3 days after those 4 days end, and Buyer’s earnest money deposit shall be returned. If Buyer sends no termination notice within those 3 days, this contingency is deemed satisfied.”
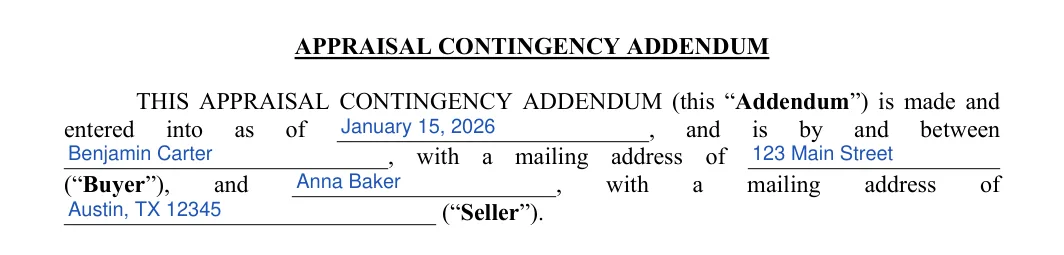
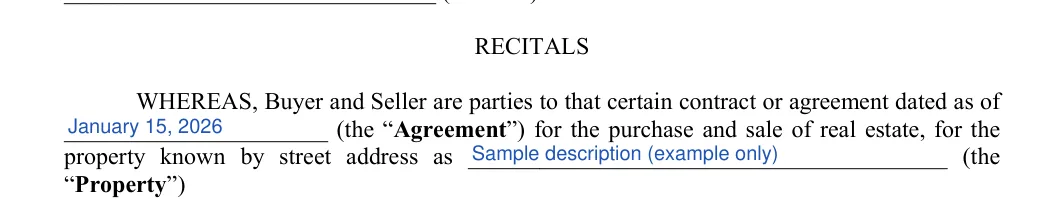
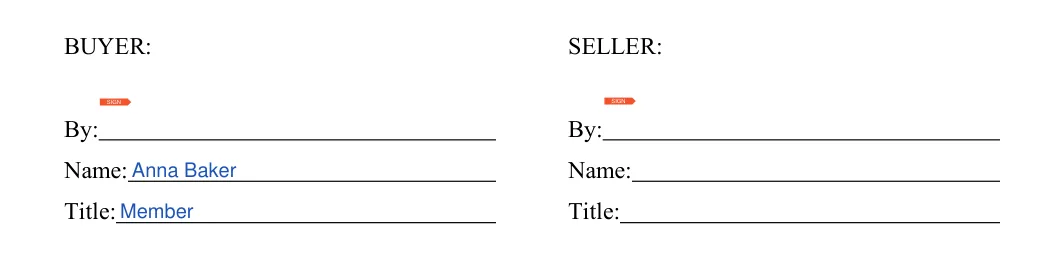
To fill out the appraisal contingency addendum, enter the date and the parties, add the agreement date and the property, and then have the buyer and seller sign. These steps follow the FormsPal template on this page. If you download the PDF, you can complete it with FormsPal’s PDF editor.
The screenshots under each step show the FormsPal Appraisal Contingency Addendum template filled with sample entries in blue, so you can see where each answer goes. The names, addresses, dates and amounts are examples only.
An appraisal contingency tests the home’s value, a financing contingency tests the buyer’s loan, and an appraisal gap clause has the buyer agree to cover some of a shortfall. A contract can hold more than one of these, so read each on its own terms.
| Term | What it turns on | What it does for the buyer |
|---|---|---|
| Appraisal contingency | The appraised value compared with the contract price | Gives a way out when the value is low |
| Financing contingency | Whether the buyer gets the loan | Gives a way out when the loan falls through |
| Appraisal gap clause | The difference between the appraised value and the price | Makes the offer stronger, with less protection against a low value |
The sources behind this page hold no statute on appraisal contingencies, so this page states no such state rule. The terms to follow start with the ones the buyer and seller write and sign, and an FHA or VA loan can add appraisal terms of its own. The nearest state rules in those sources deal with putting the sale contract itself in writing.
| State | Rule for a land sale contract, with its condition | Citation |
|---|---|---|
| Alabama | An agreement for the sale of land or an interest in it is void unless the agreement, or a note or memorandum expressing the consideration, is in writing and signed by the party to be charged or by a person that party authorized in writing. Leases for a term not longer than one year are excepted, and so is a sale where the purchase money or a portion of it is paid and the seller puts the purchaser in possession. | Ala. Code § 8-9-2 |
| Massachusetts | An action upon a contract for the sale of land or an interest in it depends on the contract, or a memorandum or note of it, being in writing and signed by the party to be charged or by a person that party lawfully authorized. | Mass. Gen. Laws ch. 259, § 1 |
| Utah | A contract for the sale of lands or an interest in lands, or for their lease for longer than one year, is void unless the contract, or a note or memorandum of it, is in writing and signed by the party making the sale or lease or by that party’s lawful agent authorized in writing. | Utah Code § 25-5-3 |
| West Virginia | A contract for the sale of land, or for its lease for more than one year, is not enforceable unless the contract, or a note or memorandum of it, is in writing and signed by the party to be charged or by that party’s agent. | W. Va. Code § 36-1-3 |
These sections speak of the sale contract and do not name an addendum. Other states are left out because the sources behind this page hold no such fact for them, which does not mean they have no writing rule. Keep the addendum in writing, signed by both parties, and attached to your purchase agreement. A local real estate attorney can tell you what applies where the home is located.
For an FHA loan, HUD Handbook 4000.1, Section II.A.1 calls for an amendatory clause if the borrower does not receive form HUD-92800.5B, the statement of appraised value, before signing the sales contract. HUD Handbook 4000.1, Section II.A.1 has the contract amended before closing in that case, with exceptions such as HUD REO sales, FHA 203(k) mortgages and sales to a buyer who will not occupy the home. The clause that HUD Handbook 4000.1, Section II.A.1 sets out frees the purchaser from completing the purchase or forfeiting earnest money unless a written statement sets the appraised value at no less than the amount the clause names, the sales price in the contract.
For a VA loan, 38 CFR 36.4303(k) applies when the contract price exceeds the reasonable value VA sets and the veteran signed before receiving notice of that value. In that case, 38 CFR 36.4303(k) allows no VA guaranty or insurance commitment unless the contract says, in substance, that the purchaser need not complete the purchase or forfeit earnest money. Under 38 CFR 36.4303(k), the purchaser can still choose to go ahead.
An appraisal contingency is a familiar term in financed home purchases, though this page holds no figure for how often buyers use one. It does the least for a buyer paying cash.
A buyer contingency addendum is an attachment that makes the buyer’s duty to close depend on a named event, and the appraisal contingency addendum is one example. Other contingencies can turn on the buyer’s loan or on an inspection.
An appraisal can come in at, above or below the asking price, and this page holds no figure for how often each happens. The appraiser reports a value of the home, and the seller’s asking price does not set it.
A seller can reasonably accept a contingent offer when its price and terms beat the other offers on the table and the condition looks likely to clear. Compare how each buyer is paying, what could end the deal, and how long the buyer has to decide. This page holds no figure for how many sellers accept such offers.
Waiving the contingency changes your contract with the seller, and it does not change what your lender asks for. A lender can still order an appraisal, and a low value can still affect the loan. You would then have no way out under this contingency, though a financing contingency or an FHA or VA clause in your contract may still give you one, so check your contract’s own terms.
The FormsPal addendum is a separate template, not the form that searchers call the PAR form ACA. PAR stands for the Pennsylvania Association of Realtors, so if your agent uses that group’s forms, ask your agent which addendum belongs in your deal.
Yes. Use the Create My Document button to answer a few questions and build the addendum online. You can also download the PDF or Word file and fill it in yourself.
General information, not legal or tax advice.
