
Updated:
Get Form Now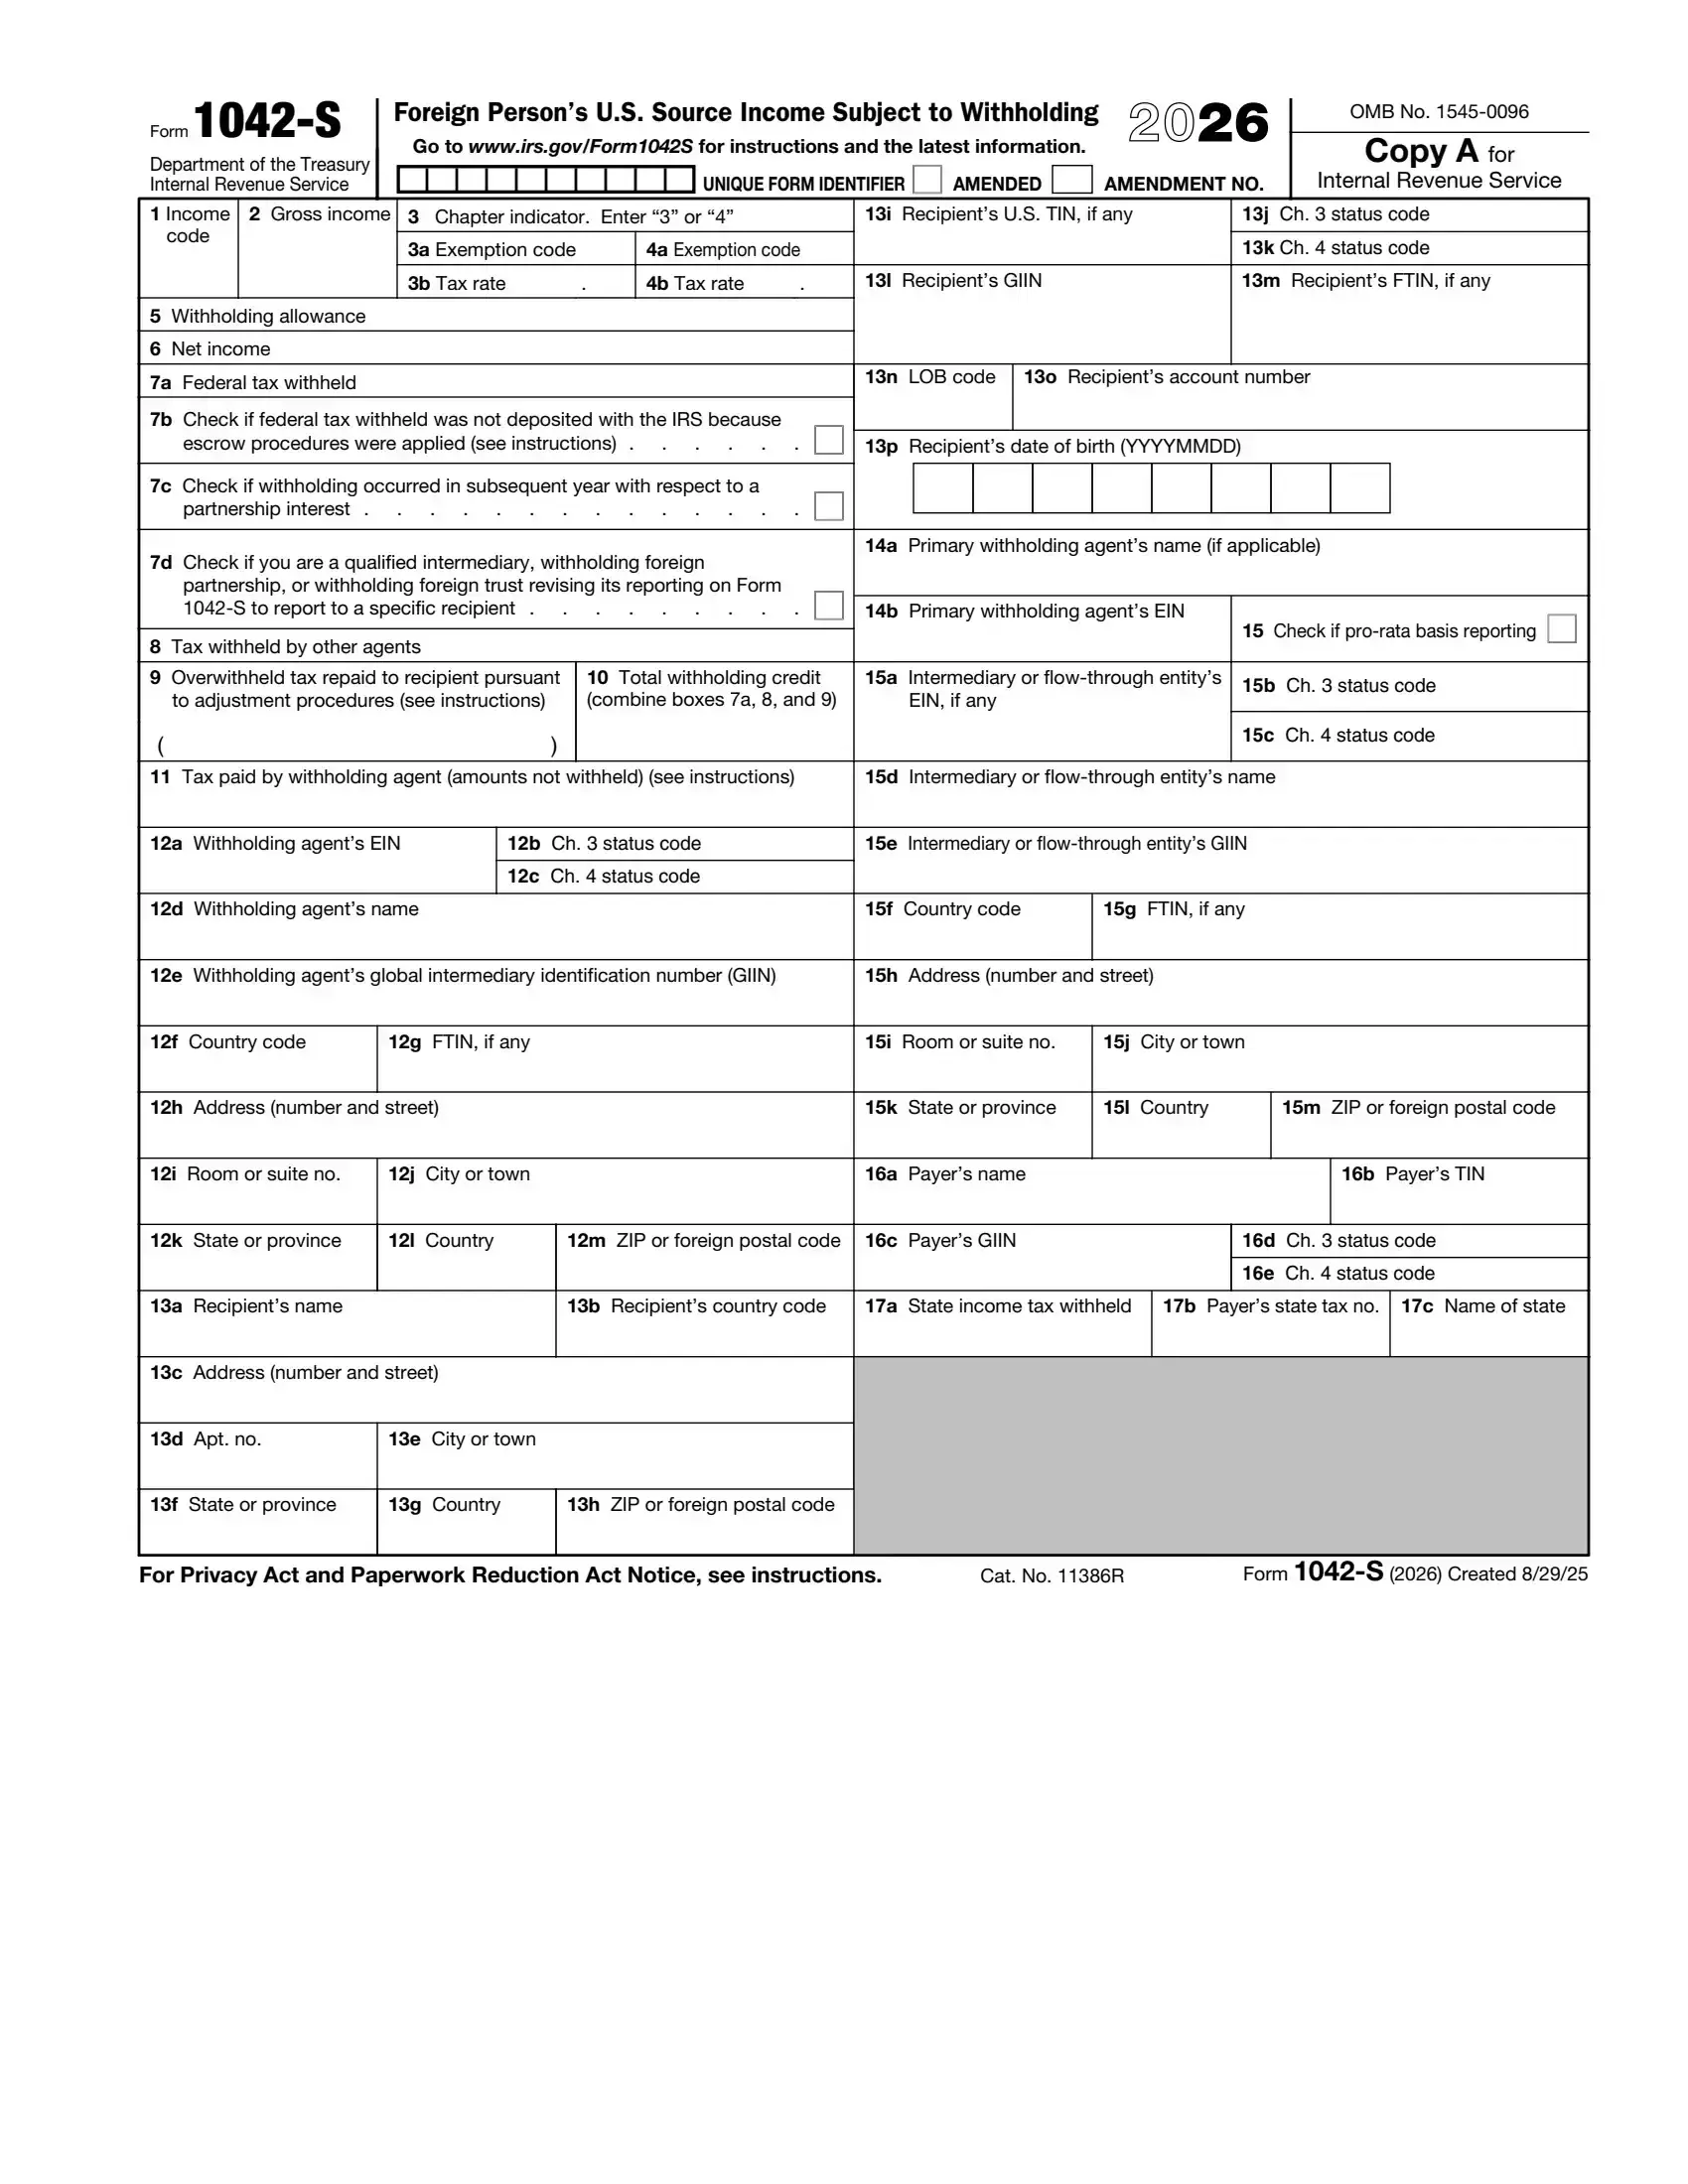
Form 1042-S is a tax document used by payers to report amounts paid to foreign individuals and entities subject to income tax withholding in the United States. This form is crucial for documenting various types of U.S. source income paid to non-residents, including royalties, dividends, scholarships, and service compensation. The purpose of Form 1042-S is to ensure compliance with U.S. tax laws regarding the taxation of income earned within the United States by individuals and entities that are not U.S. residents or citizens.
The key role of Form 1042-S is to provide the IRS with detailed information about the income paid and taxes withheld from payments to non-residents. This form helps manage and monitor U.S. payers’ tax obligations and withholding responsibilities to foreign parties. It’s a record for the IRS and an important document for income recipients, who may need it to comply with their country’s tax regulations or claim benefits under tax treaty agreements between their country and the United States. Proper use of Form 1042-S ensures that all parties accurately report international transactions, maintaining transparency and legality in cross-border financial activities.
Other IRS Forms for Individuals
On our website, you can find more IRS forms for foreign and US citizens that are used for various life occasions.
This form must be filed with the IRS by electronic services (through the FIRE system, specifically designed for accepting legal forms) or regular mail. If you file 10 or more information returns in total during the year (all types counted together) or you are a financial institution, you must file electronically. If you decide to send the form via mail, obtain the correct address of the IRS office.
Apart from Form 1042-S, you are to submit other relevant forms, such as Form 1042. To learn more about the filing process and required documents, visit irs.gov.
Another crucial thing to mention is the deadline. The due date is March 15 of the year after the payments, or the next business day when March 15 falls on a weekend or legal holiday. If you deliver all the copies and any corrections to the recipient and submit the form to the Internal Revenue Service by the deadline, you are likely to avoid penalties.
If you cannot file the document by March 15, obtain and complete Form 8809 to apply for the extension of the period. Keep in mind that the form should be submitted before the deadline.
What it is: Form 1042-S, Foreign Person's U.S. Source Income Subject to Withholding, reports amounts withheld under chapter 3 or chapter 4.[2]
Where to get it: You can download or print some of the forms and publications you may need at IRS.gov/Forms.[2]
Caution: If you file Form 1042-S, you must also file Form 1042, Annual Withholding Tax Return for U.S. Source Income of Foreign Persons.[2]
Provide Copies B, C, and D to the recipient of the income.[2]
All copies must match the copy filed with the IRS.[2]
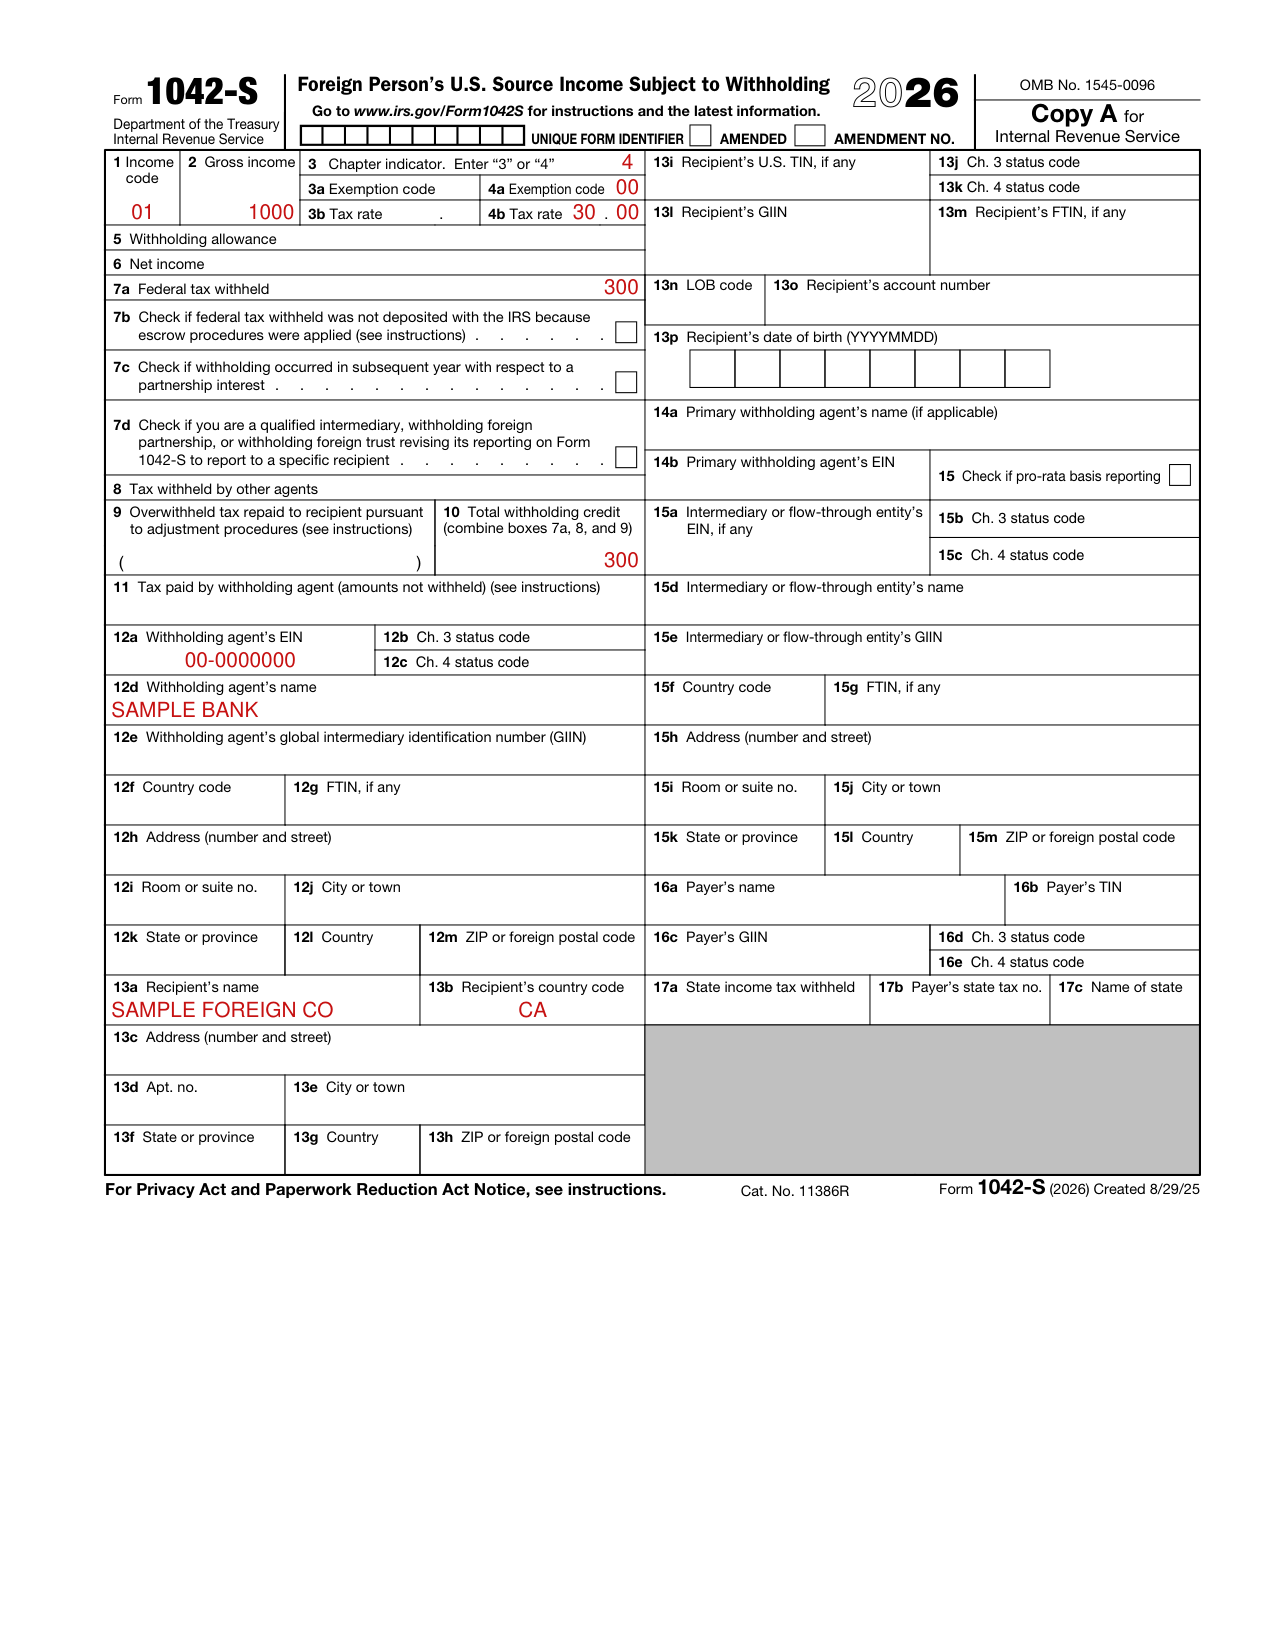
Income code 23 (other income) should be used only to report U.S. source FDAP income that is not reportable under any other available income code.
If you paid more than one type of income to or on behalf of the same recipient, you must complete a separate Form 1042-S for each income type.
Box 2: For each income type, enter the gross amount you paid (in whole dollars) to or on behalf of the recipient during the calendar year, including withheld tax.[2]
If you are reporting amounts in boxes 7 through 9, enter either “3” or “4” to indicate whether the amounts were withheld (or paid by the withholding agent) pursuant to chapter 3 or chapter 4.
Either “3” or “4” (but not both) must be entered on each Form 1042-S.
If you are not reporting amounts in boxes 7 through 9 because you did not withhold under chapter 3 or 4, you should enter “3.”
If you are reporting payments to U.S. payees, enter “3” and leave boxes 3a and 3b blank.
If an amount was withheld under chapter 4 (the tax rate you entered in box 4b is greater than zero and is not due to backup withholding), enter “00” in box 4a.
If the tax rate you entered in box 4b is 00.00, you must enter the applicable exemption code (13 through 21) in box 4a.
If an amount was withheld under chapter 3 (the tax rate you entered in box 3b is 30.00 and is not due to backup withholding), enter “00” in box 3a.
If the tax rate you entered in box 3b is due to backup withholding, leave box 3a blank.
Boxes 3b and 4b: Enter the correct rate of withholding that applies to the income in box 2 (gross income) or box 6 (net income), as appropriate.
In the case of a payment subject to chapter 4 withholding, the correct rate of withholding is “30.00.”
If the amount reported in box 2 is not subject to chapter 4 withholding or is not a withholdable payment, you must enter “00.00” in box 4b and provide the applicable exemption code in box 4a.
Enter the tax rate using the following format: two digits, a decimal point, and two digits (for example, “30.00” for 30%).
If the tax rate is less than 10%, enter a zero before the tax rate (for example, “04.00” for 4%).
If you withheld at more than one tax rate for a specific type of income that you paid to the same recipient, you must file a separate Form 1042-S for each amount to which a separate rate was applied.[2]
Enter the total amount of U.S. federal tax you actually withheld in box 7a under chapter 3 or 4.
If you did not withhold any tax, enter “-0-.”
Common mistake: Box 7a and box 10 must be completed in all cases, even if no tax has been deposited.
If you are a withholding agent filing a Form 1042-S to report income that has already been subject to withholding by another withholding agent, enter the amount actually withheld by the other agent(s) in box 8.
Enter in box 10 the combined amounts reported in box 7a (federal tax withheld), box 8 (tax withheld by other agents), and box 9 (overwithheld tax repaid to recipient pursuant to adjustment procedures).
Box 11, tax paid by withholding agent: Enter the total amount of tax paid by you and not withheld from the payment to the recipient.
For the withholding agent, any amount reported in box 11 must not be included in box 10.[2]
You are required to enter your EIN in box 12a as the withholding agent.
The withholding agent's EIN cannot be truncated.
If you don't have an EIN, you may apply for one online by going to IRS.gov/EIN.
You must enter both a chapter 3 and a chapter 4 withholding agent status code regardless of the type of payment being made.
If you are a U.S. financial institution, indicate your chapter 4 status code as 01, except when a foreign branch of a U.S. financial institution issues Form 1042-S (in such a case, indicate the chapter 4 status code as 50).
Box 12f, country code: You must enter the code (from the list at IRS.gov/CountryCodes) for the country for which you are resident under that country's tax laws.[2]
Enter the complete name of the recipient in box 13a.
If you do not know the name of the recipient, or are required to use the recipient status codes for an unknown recipient, enter “Unknown Recipient.”
In the case of foreign joint owners, Form 1042-S can only list one of the owners as the recipient in box 13a.
Form 1042-S must not be completed with more than one of the joint owners as the recipient.
Box 13b, recipient's country code: You must enter the code (from the list at IRS.gov/CountryCodes) for the country of which the recipient claims residency under that country's tax laws.
Enter “OC” (other country) only when the country of residence does not appear on the list or the payment is made to an international organization (for example, the United Nations).[2]
Withholding agents should retain a copy of the information returns filed with the IRS, or have the ability to reconstruct the data, for at least 3 years after the reporting due date.[2]
Do not use Form 1042-S to report an item required to be reported on any of the following forms.
Form W-2 (wages and other compensation made to employees (other than compensation for dependent personal services for which the beneficial owner is claiming treaty benefits), including wages in the form of group-term life insurance).
Form 1099 (except if indicated otherwise in these instructions).
Form 8288-A, Statement of Withholding on Certain Dispositions by Foreign Persons; or Form 8805, Foreign Partner's Information Statement of Section 1446 Withholding Tax.
Form 8966, FATCA Report.[2]
To request an extension of time to file Forms 1042-S, file Form 8809, Application for Extension of Time To File Information Returns.
You should request an extension as soon as you are aware that an extension is necessary, but no later than the due date for filing Form 1042-S.
By filing Form 8809, you will get an automatic 30-day extension to file Form 1042-S.
If you need more time, you may submit a second Form 8809 before the end of the initial extended due date.[2]
Forms 1042-S must be e-filed if you are a person (including a corporation, partnership, individual, trust, or estate) that is required to file 10 or more information returns during the year; or you are a partnership with more than 100 partners; or you are a financial institution (whether U.S. or foreign) regardless of the number of returns required to be filed.
Caution: If you e-file, do not file the same returns on paper.
Duplicate filing may cause penalty notices to be generated.[2]
Form 1042-S, Foreign Person's U.S. Source Income Subject to Withholding, reports amounts withheld under chapter 3 or chapter 4. Use Form 1042-S to report specified federal procurement payments paid to foreign persons that are subject to withholding under section 5000C.[2]
Every withholding agent must file an information return on Form 1042-S to report amounts paid during the preceding calendar year that are described under Amounts Subject to Reporting on Form 1042-S. However, withholding agents who are individuals are not required to report a payment on Form 1042-S if they are not making the payment as part of their trade or business and no withholding is required to be made on the payment.[2]
Copy C for Recipient: Attach to any federal tax return you file. Copy D for Recipient: Attach to any state tax return you file.
Forms 1042-S, whether filed on paper or electronically, must be filed with the IRS and be furnished to the recipient of the income by March 15 of the following calendar year. If the 15th falls on a Saturday, Sunday, or legal holiday in the District of Columbia or where the return is to be filed, the due date is the next business day.[2]
Copy A is filed with the IRS. Send all paper Forms 1042-S with Form 1042-T, Annual Summary and Transmittal of Forms 1042-S, to the address in the Form 1042-T instructions. You must use Form 1042-T to transmit paper Forms 1042-S. IRIS will be available beginning January 1, 2026, and must be used to e-file 2026 Forms 1042-S (due March 15, 2027).[2]
A penalty may be imposed for failure to file each correct and complete Form 1042-S when due (including extensions), unless you can show that the failure was due to reasonable cause and not willful neglect. The penalty is $60 per Form 1042-S if you correctly file within 30 days after the required filing date; the maximum penalty is $698,500 per year ($244,500 for a small business) (checked November 16, 2026). The penalty is $130 per Form 1042-S if you correctly file more than 30 days after the due date but by August 1; the maximum penalty is $2,095,500 per year ($698,500 for a small business) (checked November 16, 2026). The penalty is $340 per Form 1042-S if you file after August 1 or you do not file correct Forms 1042-S; the maximum penalty is $4,191,500 per year ($1,397,000 for a small business) (checked November 16, 2026). If you fail to provide Forms 1042-S to recipients and cannot show reasonable cause, a penalty of up to $340 may be imposed for each failure to furnish Form 1042-S to the recipient when due (checked November 16, 2026).[2]
You can also call the IRIS help desk at 866-937-4130 (toll free) or 470-769-5100 (not a toll-free number).[2]
Do not call the IRIS help desk for tax law questions.[2]
If you have tax law questions pertaining to Form 1042-S, call 267-941-1000 (not a toll-free number).[2]
[1] Form 1042-S (2026), Internal Revenue Service (the Official source link on this page).
[2] Instructions for Form 1042-S (2026), Internal Revenue Service.