
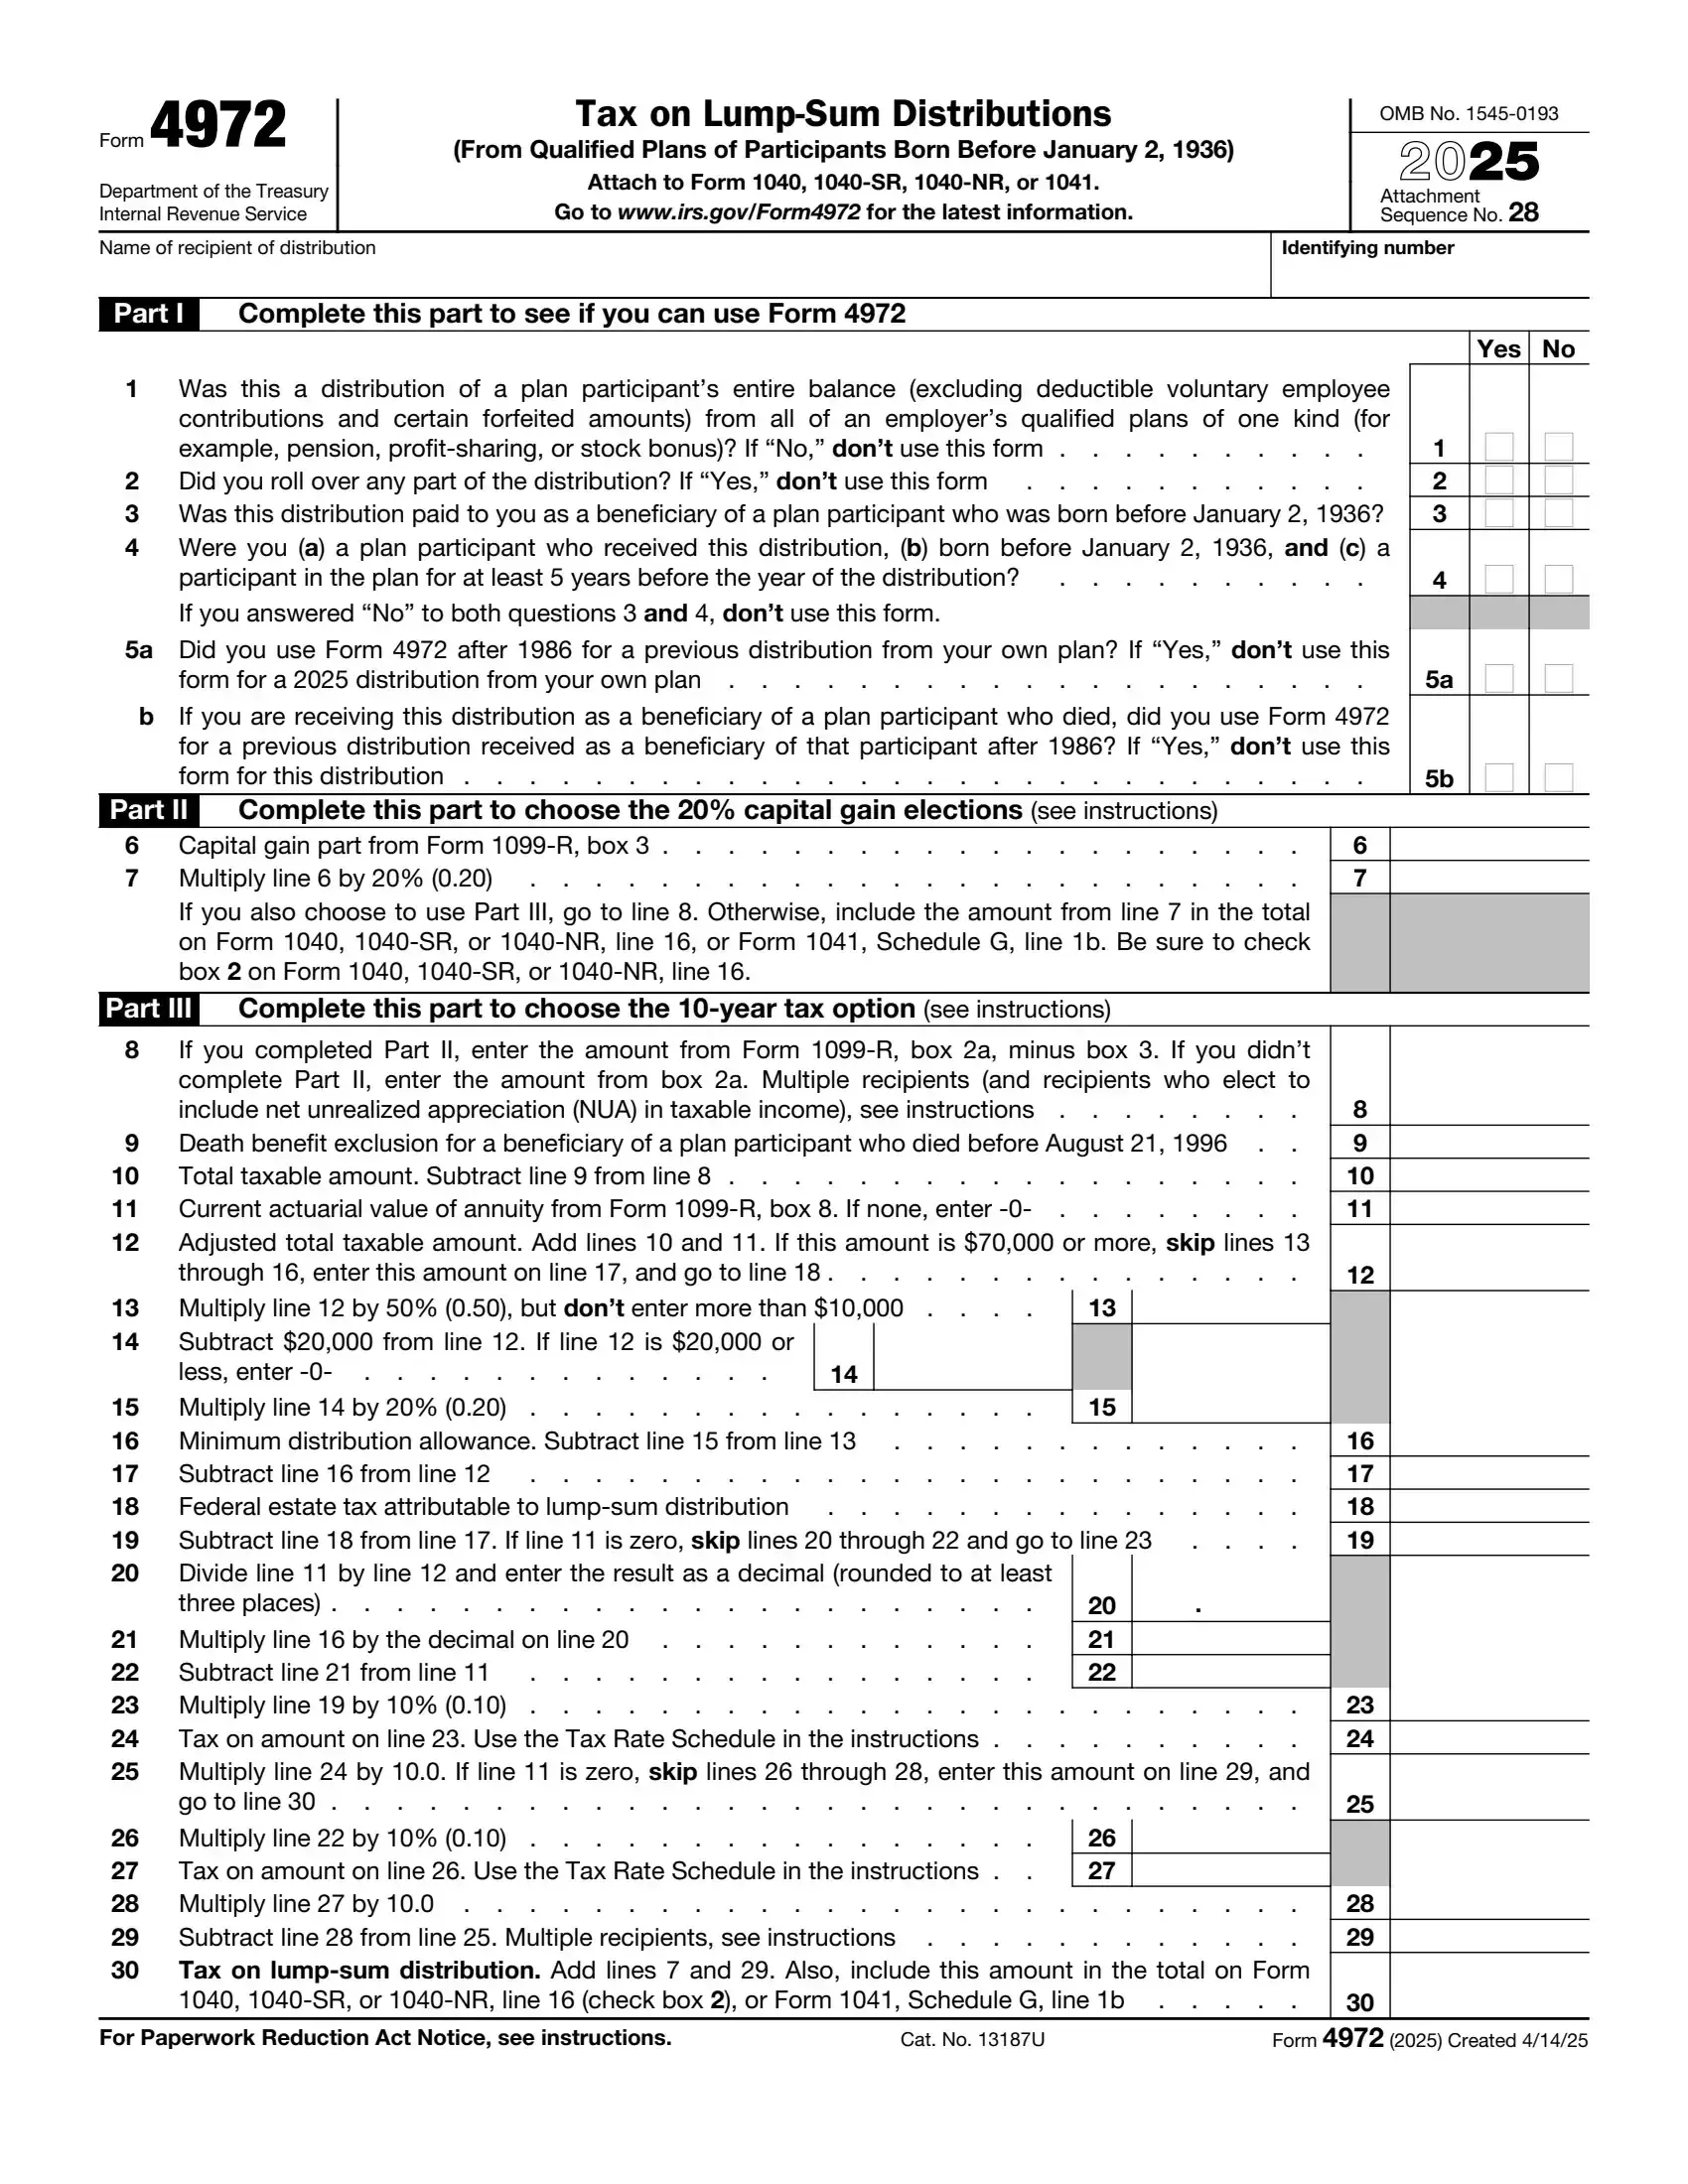
IRS Form 4972, “Tax on Lump-Sum Distributions,” is used to figure the tax on a qualified lump-sum distribution from a qualified retirement plan with the 20% capital gain election, the 10-year tax option, or both; it is available only when the plan participant was born before January 2, 1936. Distributions from IRAs do not qualify, and the additional tax on early distributions is figured on Form 5329, not on this form. Form 4972 lets an eligible taxpayer figure the tax on the distribution separately from the rest of the income on the return, which can lower the total tax.
To use it, the taxpayer needs the amounts from Form 1099-R, including the capital gain part and any net unrealized appreciation in employer securities.