
Updated:
Get Form Now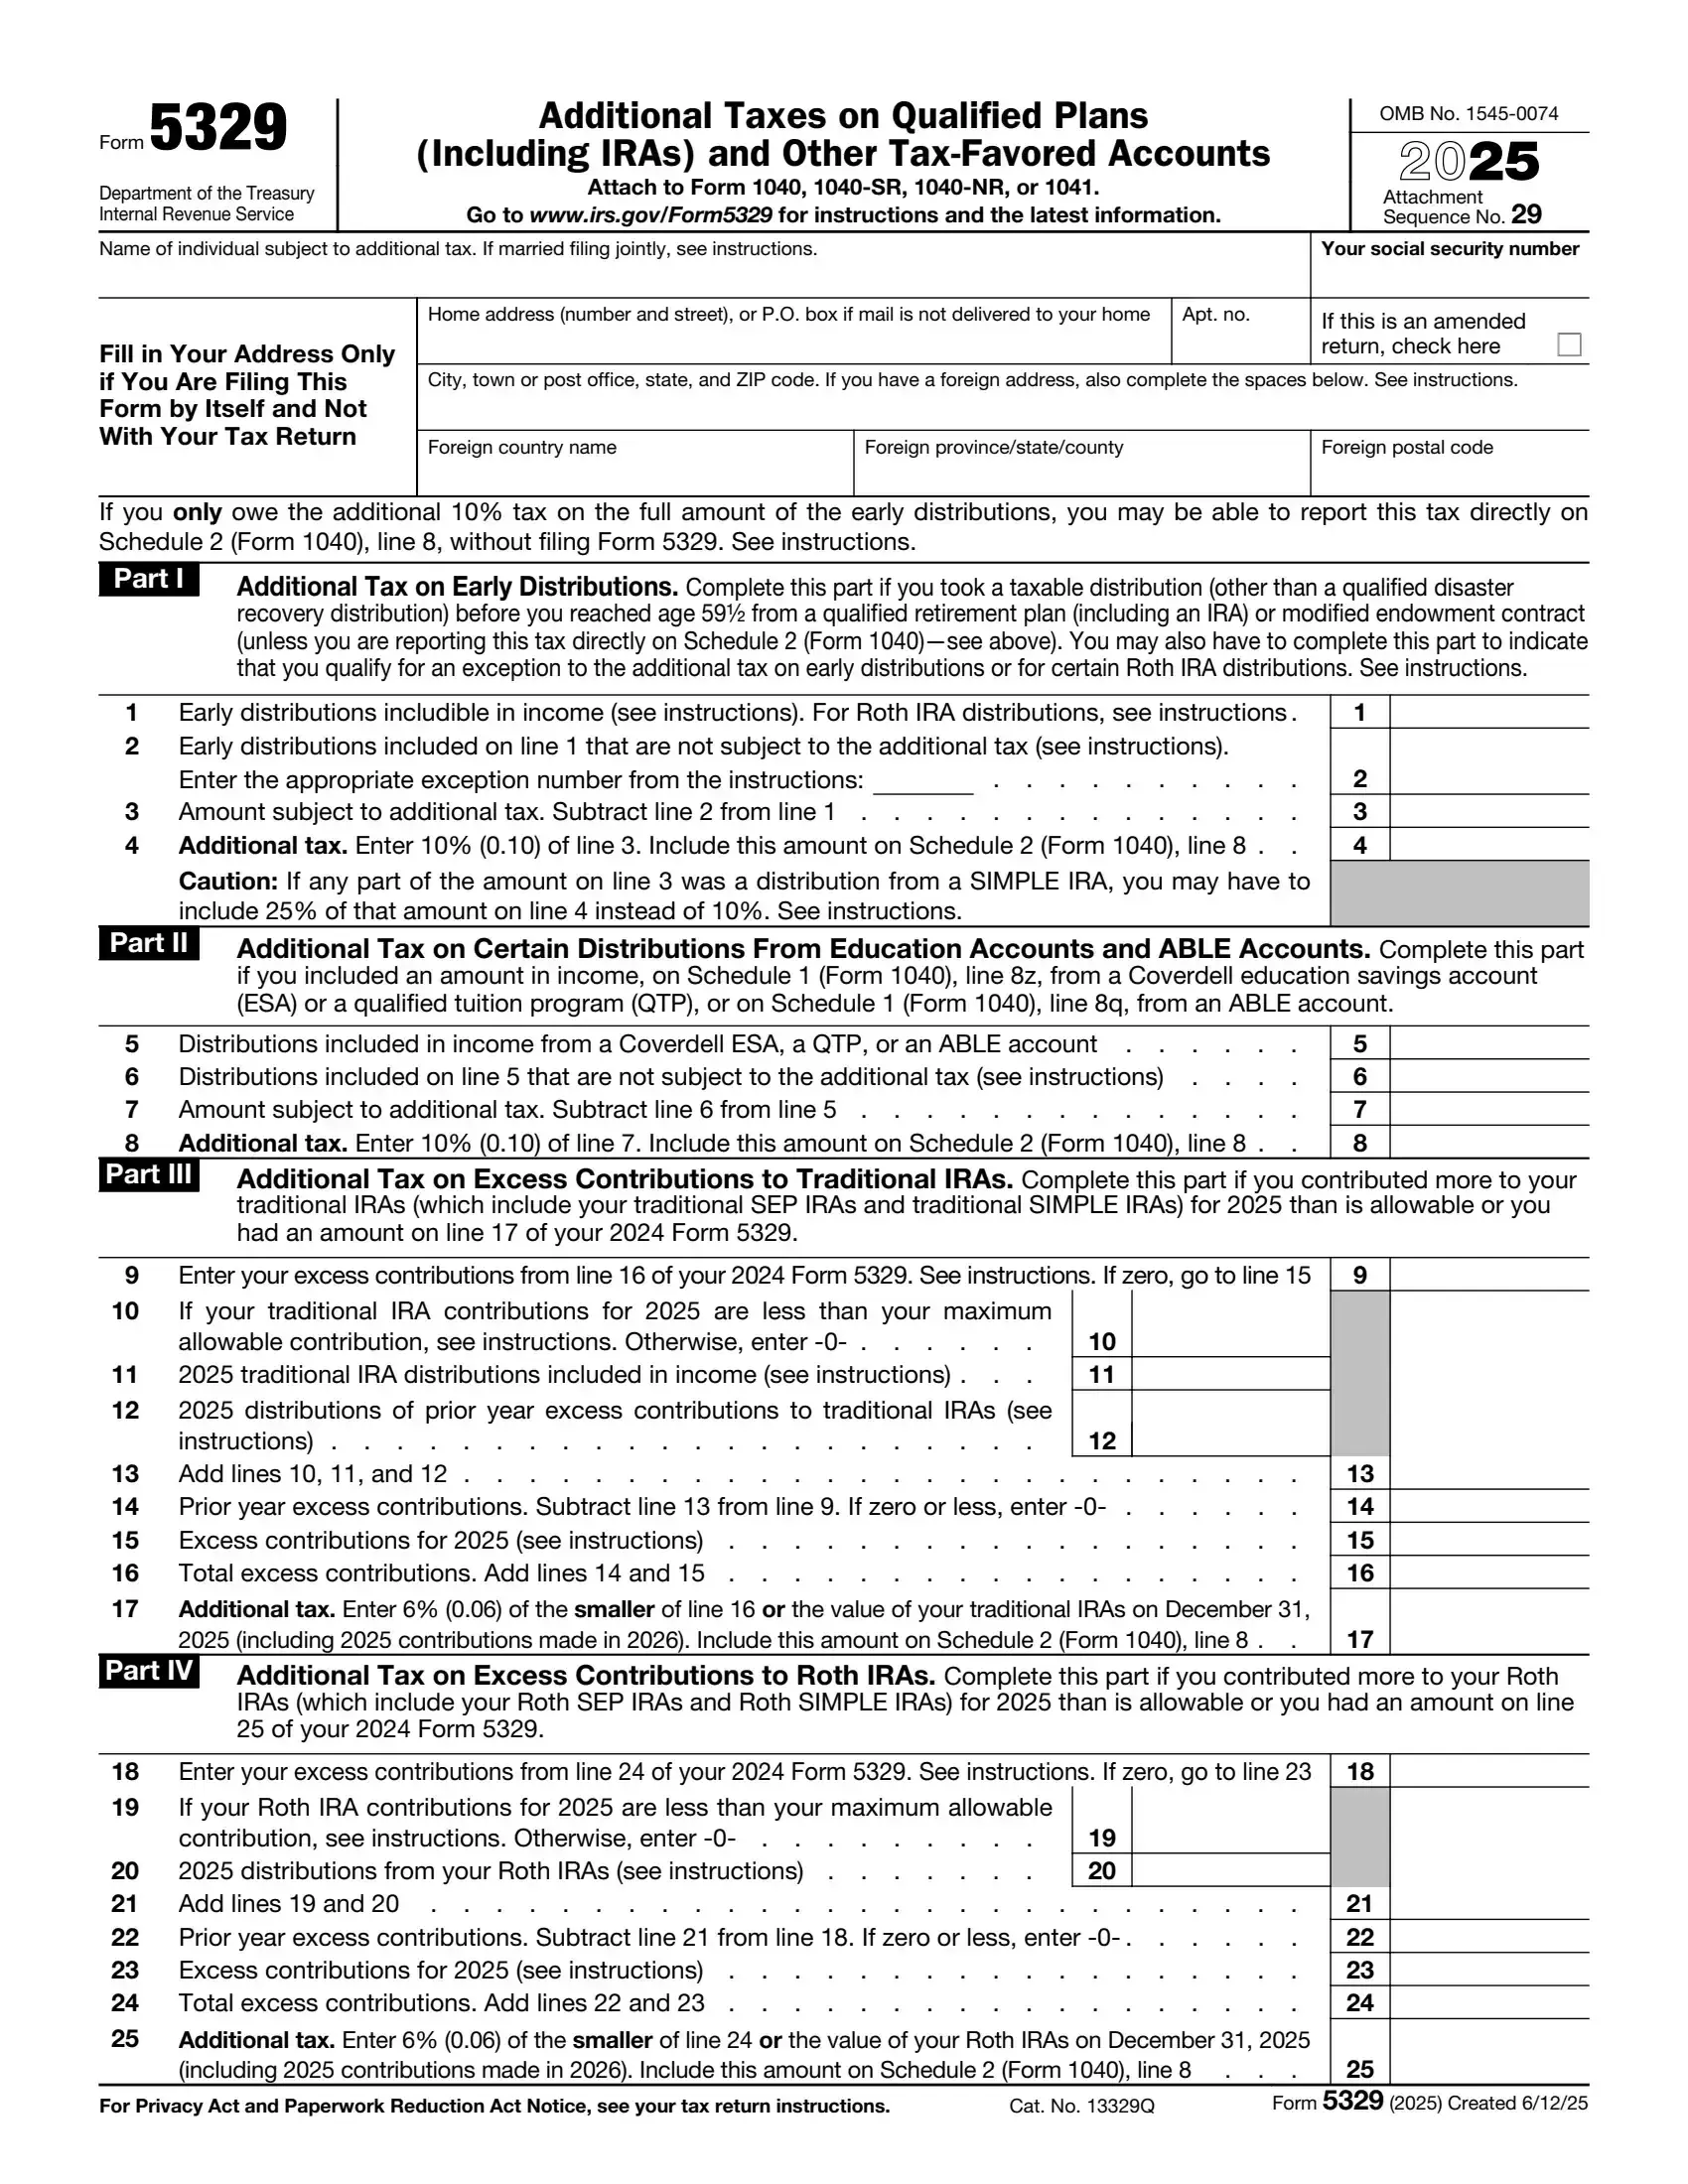
Form 5329 is an Internal Revenue Service (IRS) attachment used to report additional taxes on withdrawals or contributions to certain tax-advantaged retirement accounts. These accounts include IRAs, traditional 401(k) plans, Health Savings Accounts (HSAs), and Coverdell Education Savings Accounts (ESAs).
Essentially, it’s a form you file if you did something with your retirement savings that triggered an IRS penalty. Common reasons for needing Form 5329 include taking an early distribution from your IRA or exceeding contribution limits to your IRA or HSA. The form helps you calculate any taxes or penalties owed and allows you to attach it to your tax return.
What it is: Form 5329 is Additional Taxes on Qualified Plans (Including IRAs) and Other Tax-Favored Accounts for 2025.
Who signs: Sign here only if you are filing this form by itself and not with your tax return.
Use Form 5329 to report additional taxes on IRAs, other qualified retirement plans, modified endowment contracts, Coverdell ESAs, QTPs, Archer MSAs, HSAs, or ABLE accounts.[2]
You must file Form 5329 if any of the following apply.[2]
You received a distribution from a Roth IRA and either the amount on line 25c of Form 8606, Nondeductible IRAs, is more than zero, or the distribution includes a recapture amount subject to the 10% additional tax, or it's a qualified first-time homebuyer distribution (see Distributions from Roth IRAs, later).[2]
You received a distribution subject to the tax on early distributions from a qualified retirement plan (other than a Roth IRA).[2]
You received a distribution subject to the tax on early distributions from a qualified retirement plan (other than a Roth IRA) and you meet an exception to the tax on early distributions from the list shown later, but box 7 of your Form 1099-R doesn't indicate an exception or the exception doesn't apply to the entire distribution.[2]
You received taxable distributions from Coverdell ESAs, QTPs, or ABLE accounts.[2]
The contributions for 2025 to your traditional IRAs, Roth IRAs, Coverdell ESAs, Archer MSAs, HSAs, or ABLE accounts exceed your maximum contribution limit, or you had a tax due from an excess contribution on line 17, 25, 33, 41, or 49 of your 2024 Form 5329.[2]
You didn't receive the minimum required distribution from your qualified retirement plan. This also includes trusts and estates that didn't receive this amount.[2]
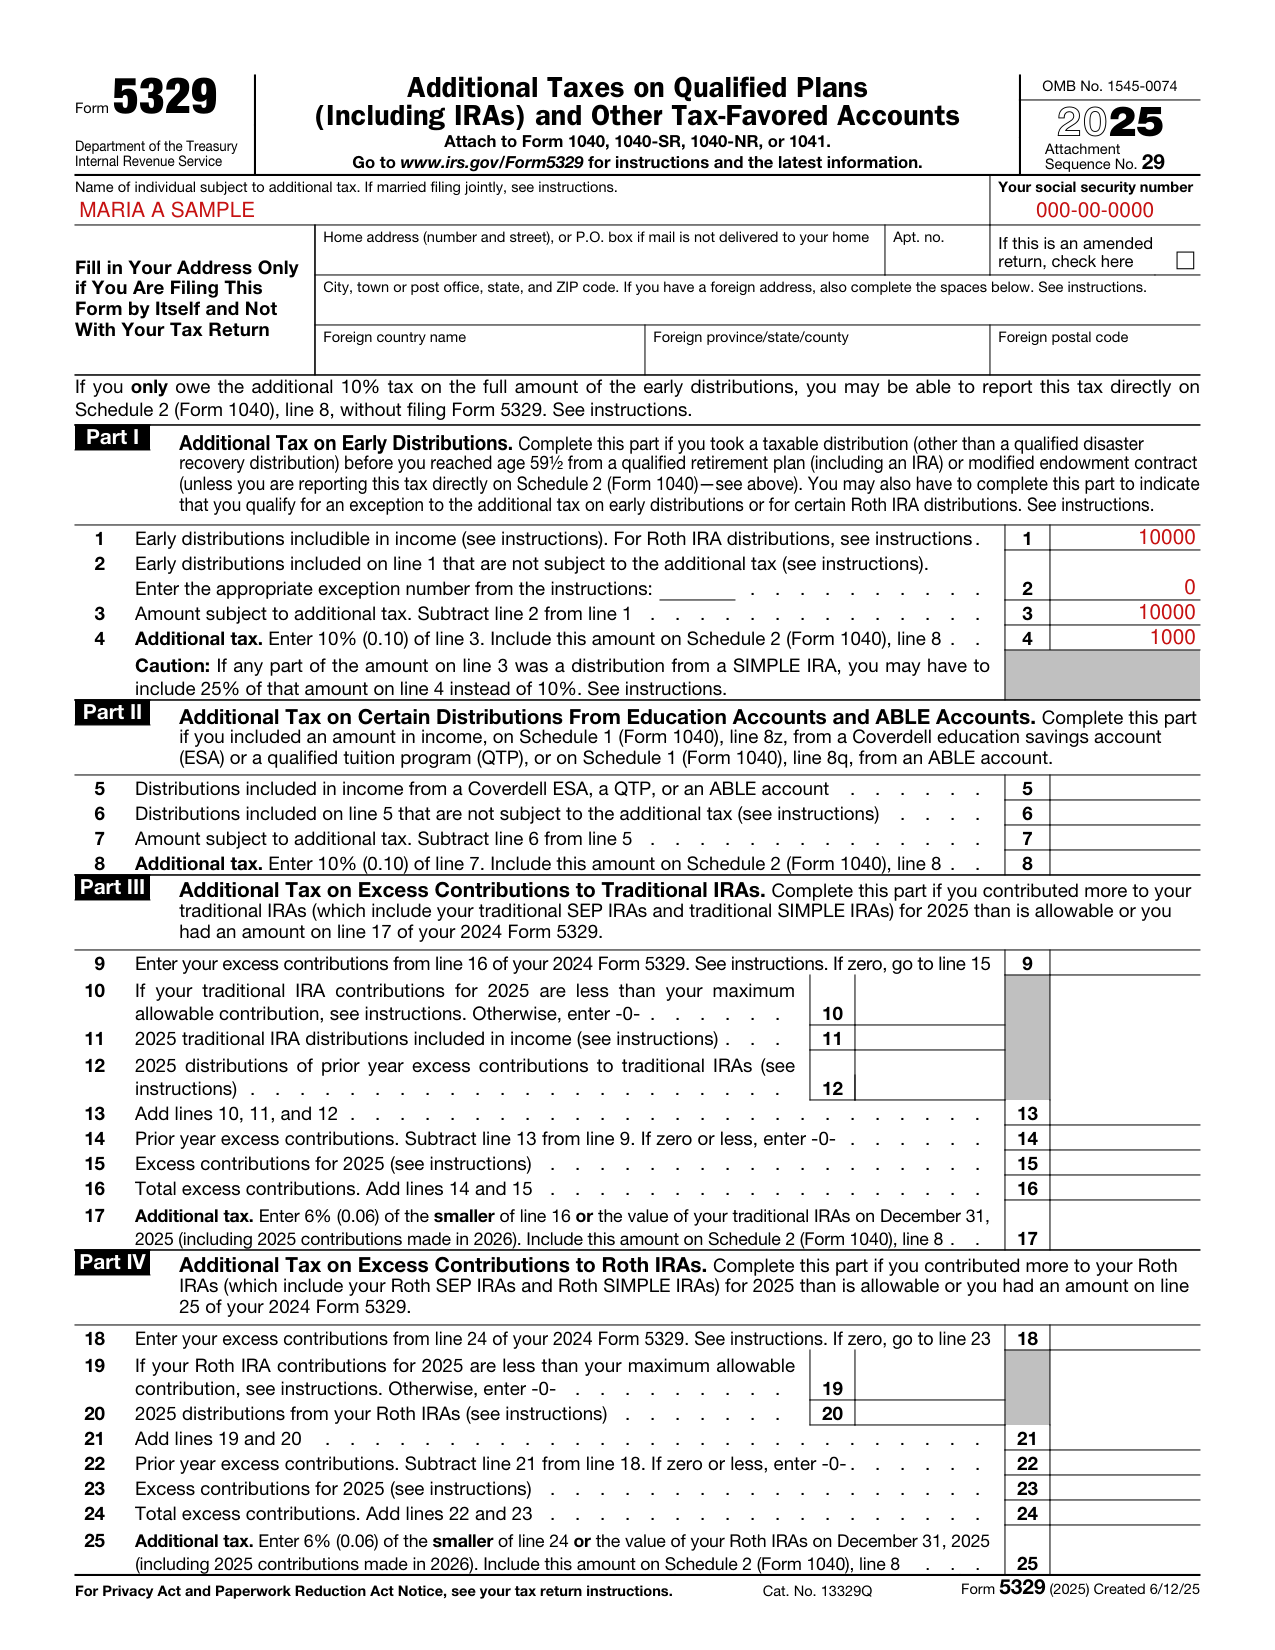

If both you and your spouse are required to file Form 5329, complete a separate form for each of you. Include the combined tax on Schedule 2 (Form 1040), line 8.[2]
If you are filing an amended 2025 Form 5329, check the box at the top of page 1 of the form. Don't use the 2025 Form 5329 to amend your return for any other year.[2]
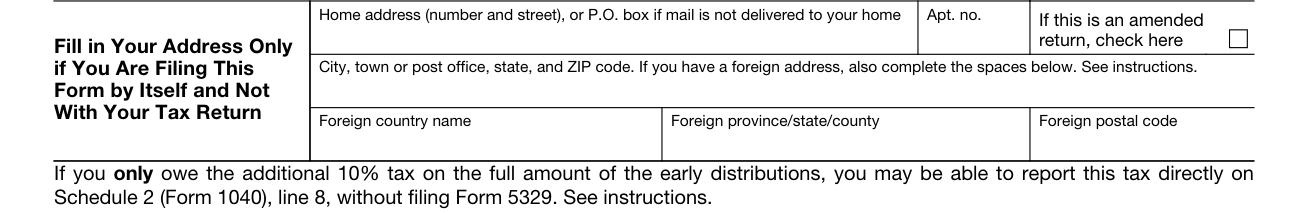
Fill in your address only if you are filing this form by itself and not with your tax return.
Be sure to include your address on page 1 of the form and your signature and the date on page 3 of the form.
If you have a foreign address, also complete the Foreign country name, Foreign province/state/county and Foreign postal code spaces.[2]
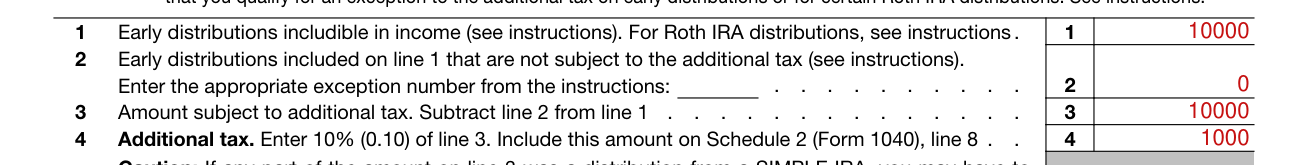
Complete this part if you took a taxable distribution (other than a qualified disaster recovery distribution) before you reached age 59½ from a qualified retirement plan (including an IRA) or modified endowment contract (unless you are reporting this tax directly on Schedule 2 (Form 1040)).
Line 1: enter the amount of early distributions includible in income (other than qualified disaster recovery distributions) that you received from a qualified retirement plan including earnings on withdrawn excess contributions to your IRAs included in income in 2025, or from a modified endowment contract.
Enter on line 2 the amount that you can exclude.
In the space provided, enter the applicable exception number (01-23). If more than one exception applies, enter 99.
Line 3, amount subject to additional tax: subtract line 2 from line 1. Line 4, additional tax: enter 10% (0.10) of line 3. Include this amount on Schedule 2 (Form 1040), line 8.
Line 4: if any amount on line 3 was a distribution from a SIMPLE IRA received within 2 years from the date you first participated in the SIMPLE IRA plan, you must multiply that amount by 25% instead of 10%.[2]
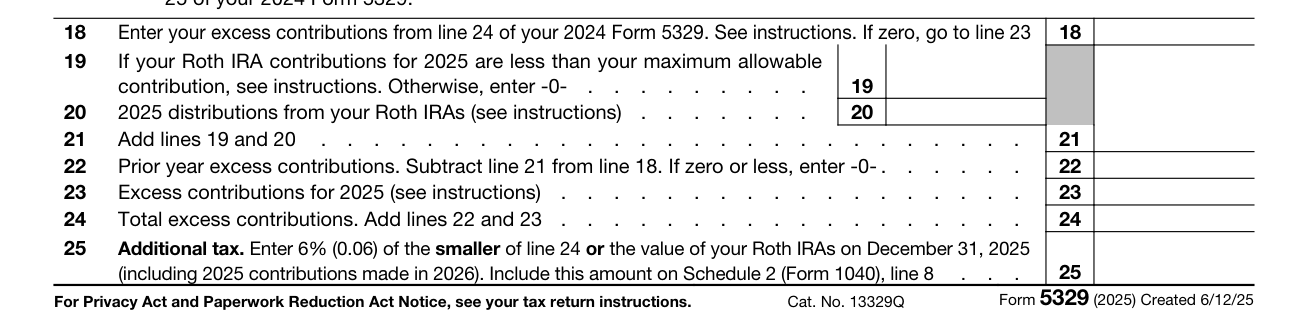
If you contributed more to your Roth IRA for 2025 than is allowable or you had an amount on line 25 of your 2024 Form 5329, you may owe this tax. But you may be able to avoid the tax on any 2025 excess contributions (see the instructions for line 23).
Line 23: enter the excess of your contributions to Roth IRAs for 2025 (unless withdrawn) over your contribution limit for Roth IRAs. Don't include rollovers in figuring your excess contributions.
You can withdraw some or all of your excess contributions for 2025 and they will be treated as not having been contributed if you make the withdrawal by the due date, including extensions, of your 2025 tax return; and you withdraw any earnings on the withdrawn contributions and include the earnings in gross income (see the Instructions for Form 8606 for details).
If you hadn't reached age 591/2 at the time of the withdrawal, include the earnings as an early distribution on line 1 of Form 5329 for the year in which you report the earnings. Report this amount on line 2 and enter exception number 21.
Line 25, additional tax: enter 6% (0.06) of the smaller of line 24 or the value of your Roth IRAs on December 31, 2025 (including 2025 contributions made in 2026).[2]
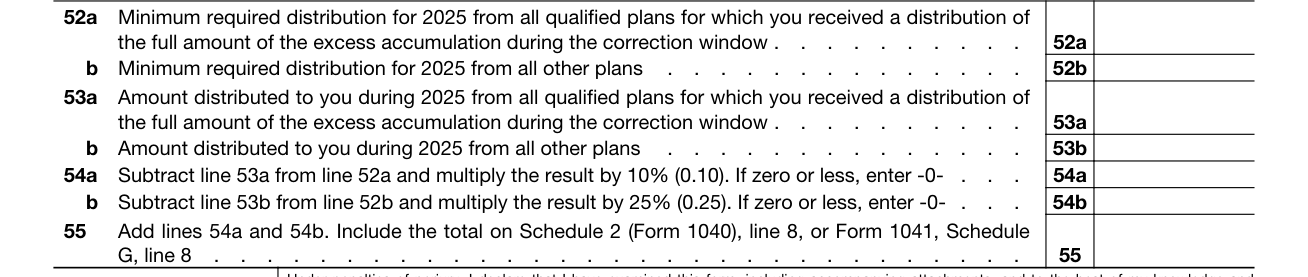
Complete this part if you did not receive the minimum required distribution from your qualified retirement plan.
You owe this tax if you don't receive the minimum required distribution from your qualified retirement plan, including an IRA or an eligible section 457 deferred compensation plan. The additional tax is 25% of the excess accumulation, which is the difference between the amount that was required to be distributed and the amount that was actually distributed.
You may be eligible for a reduced tax rate of 10% if, during the correction window, you: 1. receive a distribution of the amount that resulted in the excess accumulation from the plan for which the tax was imposed; and 2. submit a return reflecting the additional tax.
Line 52a: minimum required distribution for 2025 from all qualified plans for which you received a distribution of the full amount of the excess accumulation during the correction window. Line 52b: minimum required distribution for 2025 from all other plans. Line 53a: amount distributed to you during 2025 from all qualified plans for which you received a distribution of the full amount of the excess accumulation during the correction window. Line 53b: amount distributed to you during 2025 from all other plans.
Common mistake: Enter the amount distributed towards the required minimum distribution from all plans. Do not include on line(s) 53a and/or 53b, any distribution(s) received after the deadline for taking the minimum required distribution or during the correction window.
Line 54a: subtract line 53a from line 52a and multiply the result by 10% (0.10). If zero or less, enter -0-. Line 54b: subtract line 53b from line 52b and multiply the result by 25% (0.25). If zero or less, enter -0-.
Line 55: add lines 54a and 54b. Include the total on Schedule 2 (Form 1040), line 8, or Form 1041, Schedule G, line 8.[2]
Sign here only if you are filing this form by itself and not with your tax return.
Under penalties of perjury, I declare that I have examined this form, including accompanying attachments, and to the best of my knowledge and belief, it is true, correct, and complete.
If you are filing Form 5329 for a prior year, you must use the prior year's version of the form.[2]
File Form 5329 with your 2025 Form 1040, 1040-SR,1040-NR, or 1041 by the due date, including extensions, of your tax return.[2]
If you don't have to file a 2025 income tax return, complete and file Form 5329 by itself at the time and place you would be required to file Form 1040, 1040-SR, or 1040-NR. If you file Form 5329 by itself, then it can't be filed electronically.[2]
However, if distribution code 1 is correctly shown in box 7 of all your Forms 1099-R and you owe the additional tax on the full amount shown on each Form 1099-R, you don't have to file Form 5329. Instead, see the instructions for Schedule 2 (Form 1040), line 8, in the Instructions for Form 1040, or the Instructions for Form 1040-NR, for how to report the 10% additional tax directly on that line.[2]
[1] Form 5329 (2025), Additional Taxes on Qualified Plans (Including IRAs) and Other Tax-Favored Accounts, Internal Revenue Service (the Official source link on this page).
[2] Instructions for Form 5329 (2025), Internal Revenue Service.