
Updated:
Get Form Now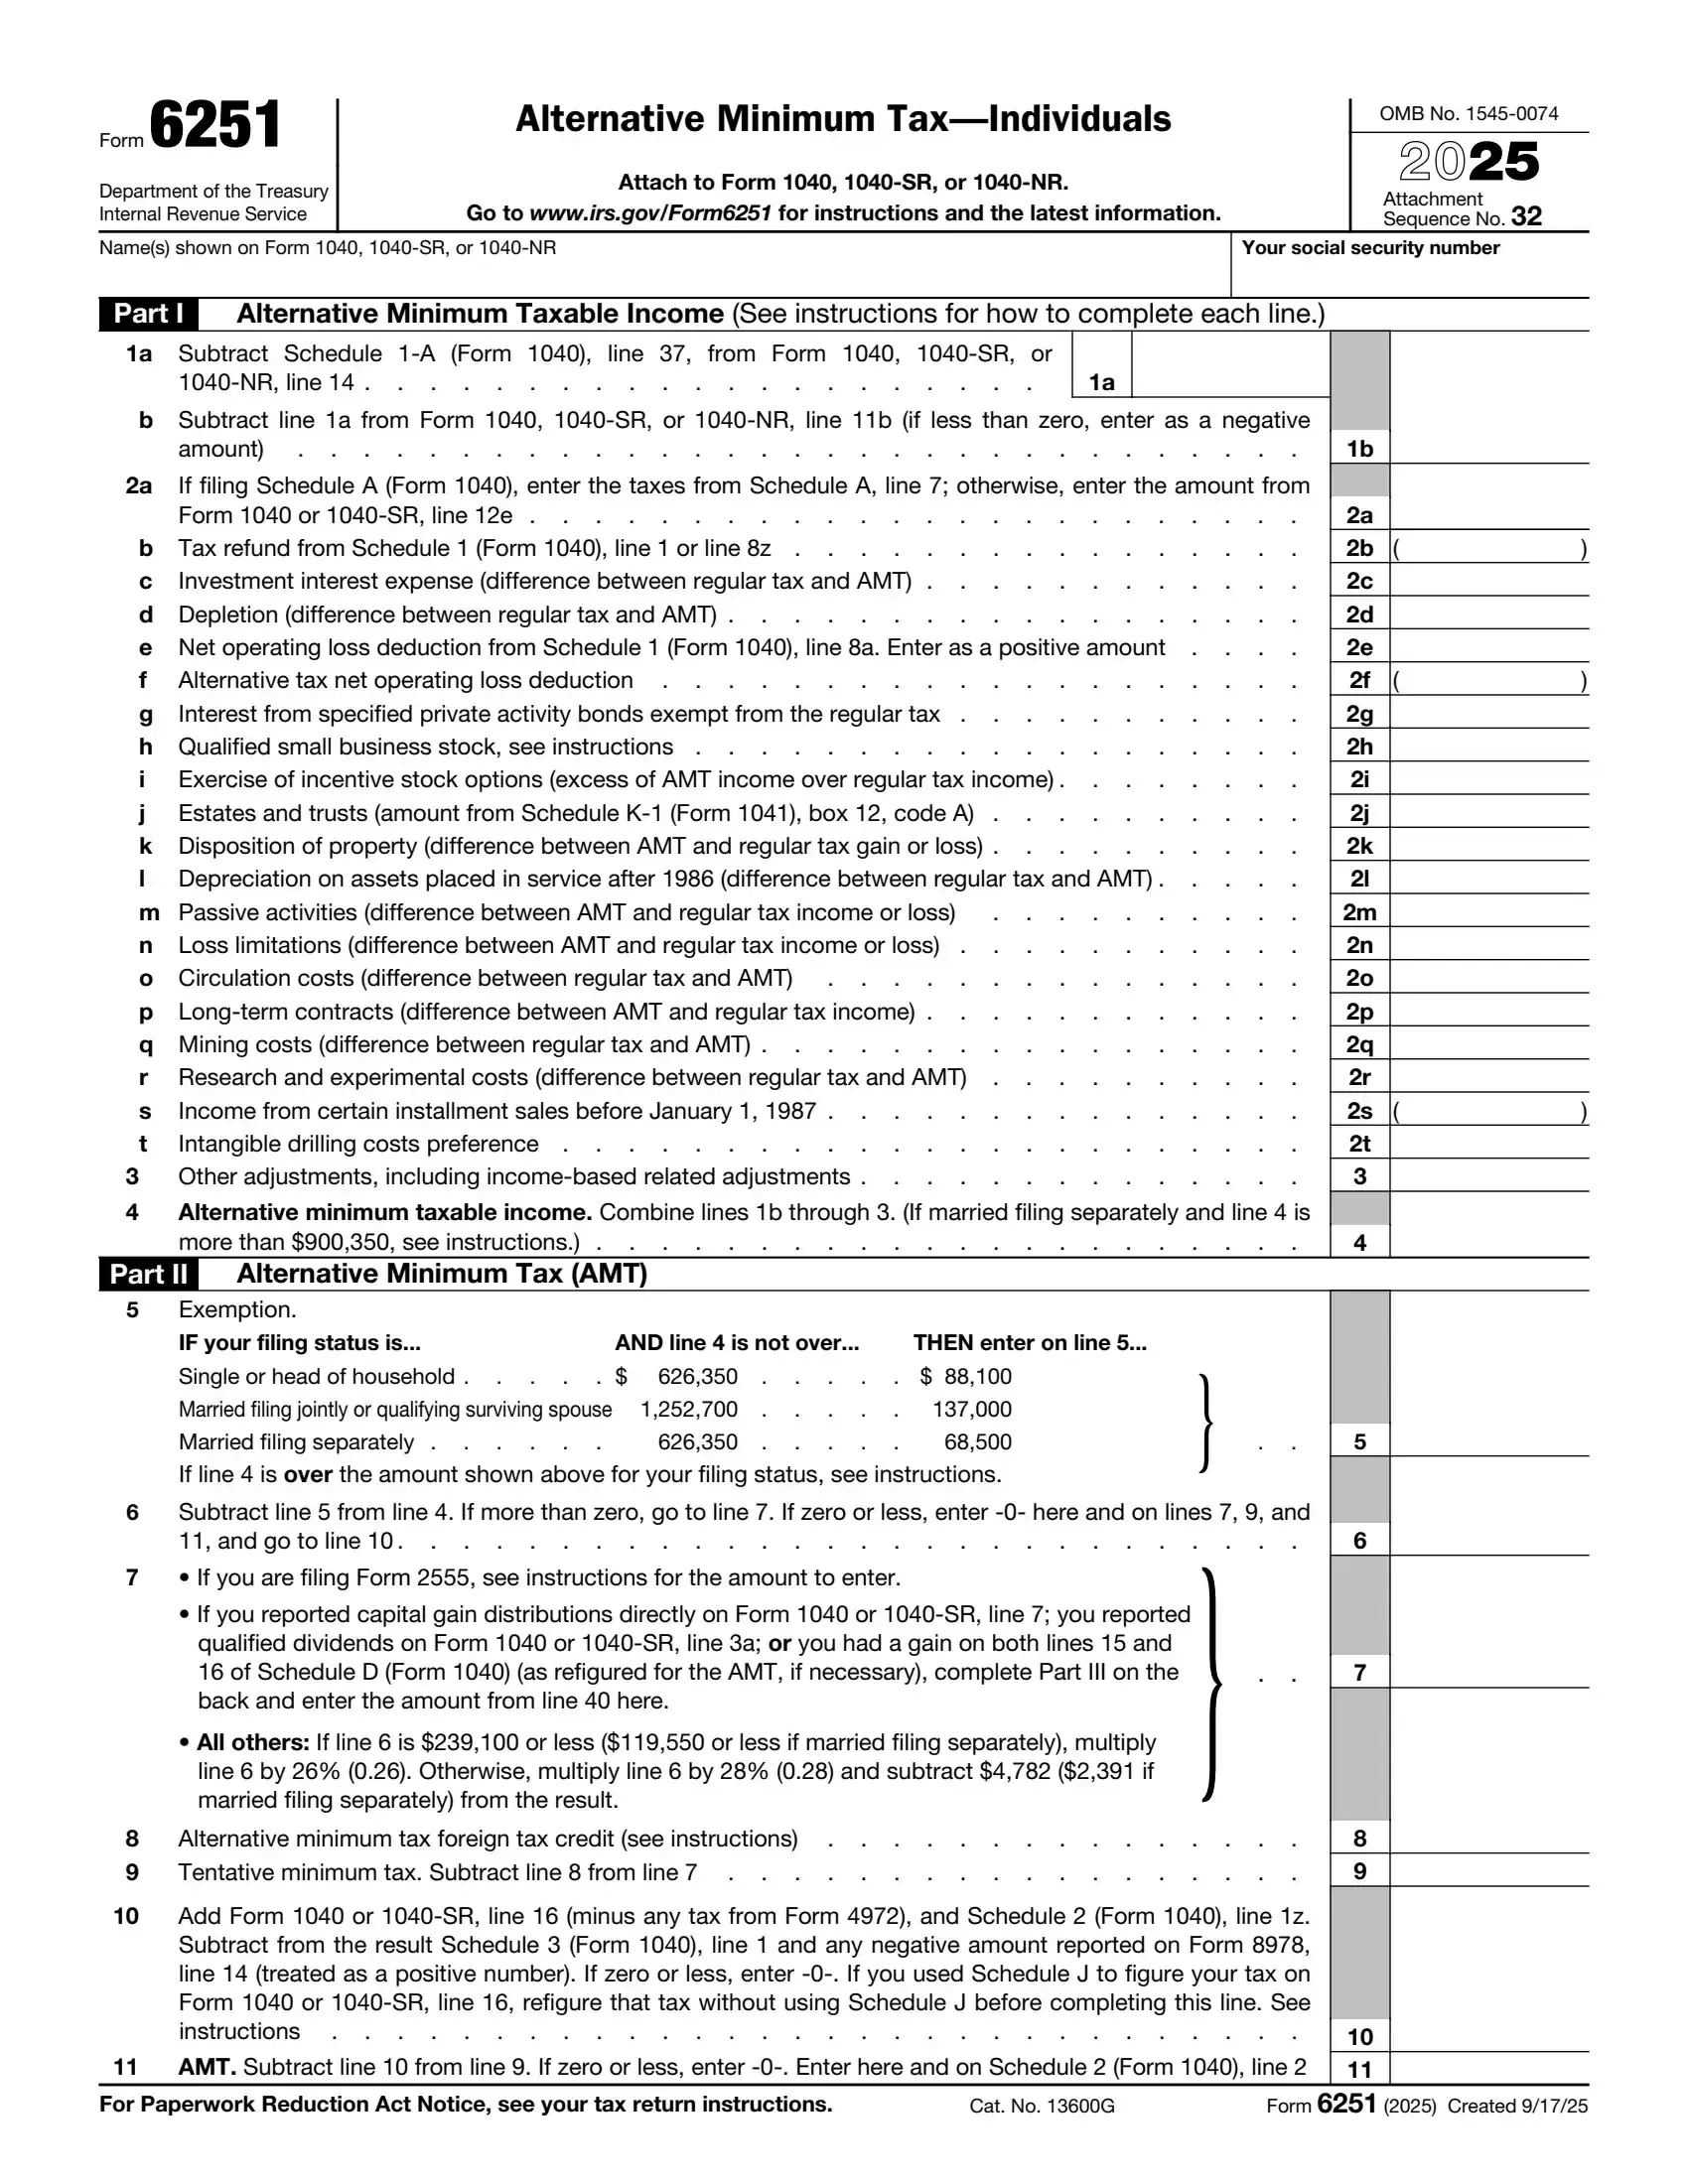
IRS Form 6251 is a tax form certain taxpayers use to calculate their alternative minimum tax (AMT). The AMT ensures that individuals who benefit from certain exclusions, deductions, or credits pay at least a minimum level of federal income tax. This form assesses potential income and allowable deductions adjustments, comparing standard tax calculations with AMT provisions. The taxpayer must pay the difference if the AMT is higher than the regular tax liability.
The purpose of Form 6251 is to identify items that are treated differently for AMT than for regular income tax purposes, such as the state and local tax deduction, incentive stock options, and interest from private activity bonds. By completing this form, taxpayers can determine whether they owe AMT and ensure compliance with tax laws, thus avoiding potential penalties for underpayment. This process helps maintain fairness in the tax system by minimizing the chances that individuals with higher incomes can significantly lower their tax obligations through various tax benefits.
Other IRS Forms for Individuals
We offer you to look at more IRS forms to make sure you didn’t miss out on any form you need to file with the Internal Revenue Service.
What it is: Form 6251, Alternative Minimum Tax-Individuals, is the form for figuring the amount, if any, of your alternative minimum tax (AMT).[2]
Where and when to file: Attach Form 6251 to Form 1040, 1040-SR, or 1040-NR.
The AMT is a separate tax that is imposed in addition to your regular tax. It applies to taxpayers who have certain types of income that receive favorable treatment or who qualify for certain deductions under the tax law.[2]
Attach Form 6251 to your return if any of the following statements are true: Form 6251, line 7, is greater than line 10.[2]
Attach Form 6251 to your return if any of the following statements are true: You claim any general business credit, and either line 6 (in Part I) of Form 3800 or line 25 of Form 3800 is more than zero.[2]
Attach Form 6251 to your return if any of the following statements are true: You claim the qualified electric vehicle credit (Form 8834), the personal-use part of the alternative fuel vehicle refueling property credit (Form 8911), or the credit for prior year minimum tax (Form 8801).[2]
Attach Form 6251 to your return if any of the following statements are true: The total of Form 6251, lines 2c through 3, is negative and line 7 would be greater than line 10 if you didn't take into account lines 2c through 3.[2]
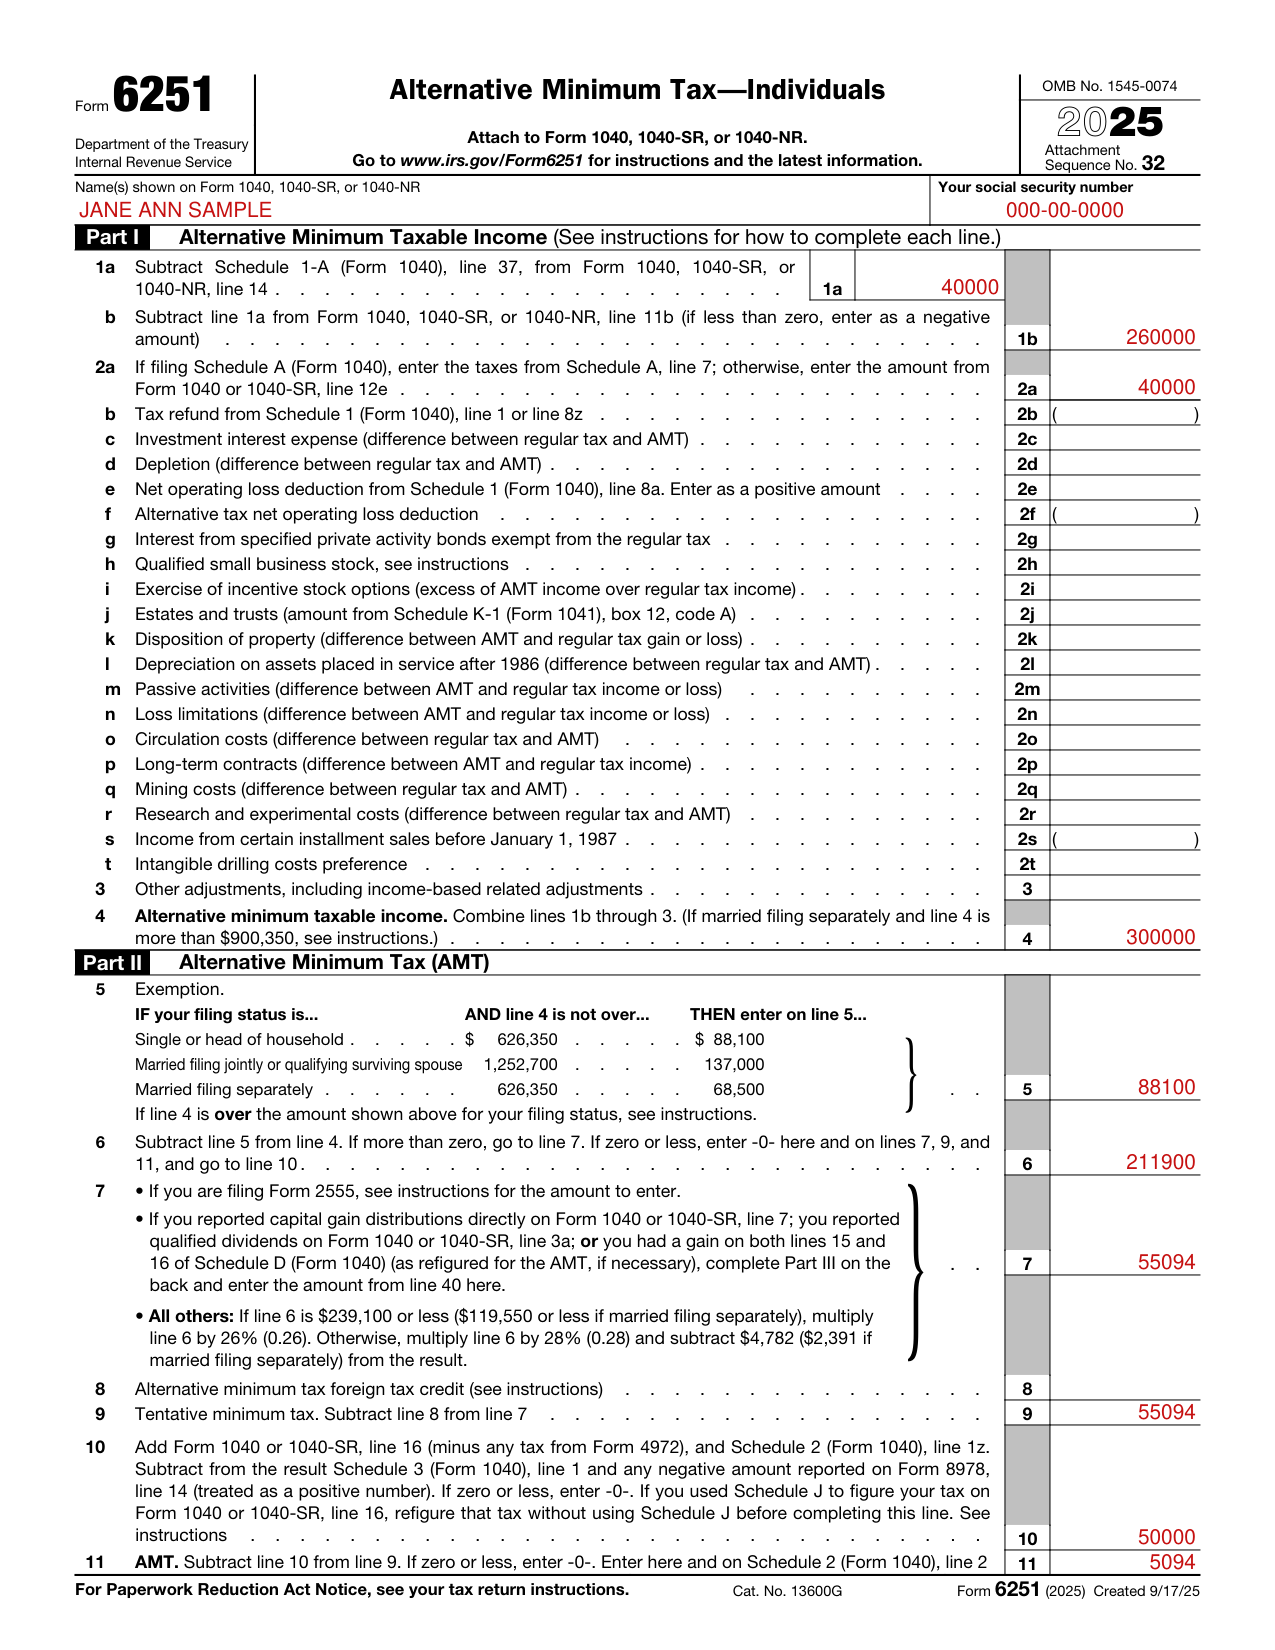
Enter on Form 6251, line 1a, the difference between line 14 of your Form 1040, 1040-SR, or 1040-NR, and line 37 of your Schedule 1-A (Form 1040).
Enter on Form 6251, line 1b, the difference between line 1a of Form 6251 and line 11b of your Form 1040, 1040-SR, or 1040-NR. If less than zero, enter as a negative amount.[2]
Line 2a, Taxes: enter the amount of all taxes from Schedule A (Form 1040), line 7, except any generation-skipping transfer taxes on income distributions.
If you aren't filing Schedule A (Form 1040), then enter the standard deduction amount that you reported on Form 1040 or 1040-SR, line 12e.
Enter the Tax refund from Schedule 1 (Form 1040), line 1 or line 8z, on line 2b.
Line 2c is Investment interest expense (difference between regular tax and AMT), and line 2d is Depletion (difference between regular tax and AMT).[2]
Line 3 is Other adjustments, including income-based related adjustments.
On line 4, Alternative minimum taxable income, combine lines 1b through 3. If married filing separately and line 4 is more than $900,350, see instructions. (checked November 16, 2026)
On line 5, Exemption: if your filing status is single or head of household and line 4 is not over 626,350, enter 88,100 on line 5.
Married filing jointly or qualifying surviving spouse: if line 4 is not over 1,252,700, enter 137,000 on line 5.
Married filing separately: if line 4 is not over 626,350, enter 68,500 on line 5.
If line 4 is over the amount shown above for your filing status, see instructions.
On line 6, subtract line 5 from line 4. If more than zero, go to line 7. If zero or less, enter -0- here and on lines 7, 9, and 11, and go to line 10.
On line 7, for all others: if line 6 is $239,100 or less ($119,550 or less if married filing separately), multiply line 6 by 26% (0.26). (checked November 16, 2026)
Otherwise, multiply line 6 by 28% (0.28) and subtract $4,782 ($2,391 if married filing separately) from the result. (checked November 16, 2026)
If you are filing Form 2555, see instructions for the amount to enter on line 7.
If you reported capital gain distributions directly on Form 1040 or 1040-SR, line 7; you reported qualified dividends on Form 1040 or 1040-SR, line 3a; or you had a gain on both lines 15 and 16 of Schedule D (Form 1040) (as refigured for the AMT, if necessary), complete Part III on the back and enter the amount from line 40 on line 7.
Line 8 is the Alternative minimum tax foreign tax credit (see instructions).
On line 9, Tentative minimum tax, subtract line 8 from line 7.
On line 10, add Form 1040 or 1040-SR, line 16 (minus any tax from Form 4972), and Schedule 2 (Form 1040), line 1z. Subtract from the result Schedule 3 (Form 1040), line 1 and any negative amount reported on Form 8978, line 14 (treated as a positive number). If zero or less, enter -0-. If you used Schedule J to figure your tax on Form 1040 or 1040-SR, line 16, refigure that tax without using Schedule J before completing this line. See instructions. On line 11, AMT, subtract line 10 from line 9. If zero or less, enter -0-. Enter it here and on Schedule 2 (Form 1040), line 2.
On page 2 of the 2025 Form 6251, Part III Tax Computation Using Maximum Capital Gains Rates. Complete Part III only if you are required to do so by line 7 or by the Foreign Earned Income Tax Worksheet in the instructions.
Enter the smaller of line 38 or line 39 here and on line 7. If you are filing Form 2555, do not enter this amount on line 7. Instead, enter it on line 4 of the worksheet in the instructions for line 7.
You must keep records to support items reported on Form 6251 in case the IRS has questions about them.[2]
[1] Form 6251 (2025), Alternative Minimum Tax-Individuals, Internal Revenue Service (the Official source link on this page).
[2] 2025 Instructions for Form 6251, Alternative Minimum Tax-Individuals, Internal Revenue Service.