
Updated:
Get Form Now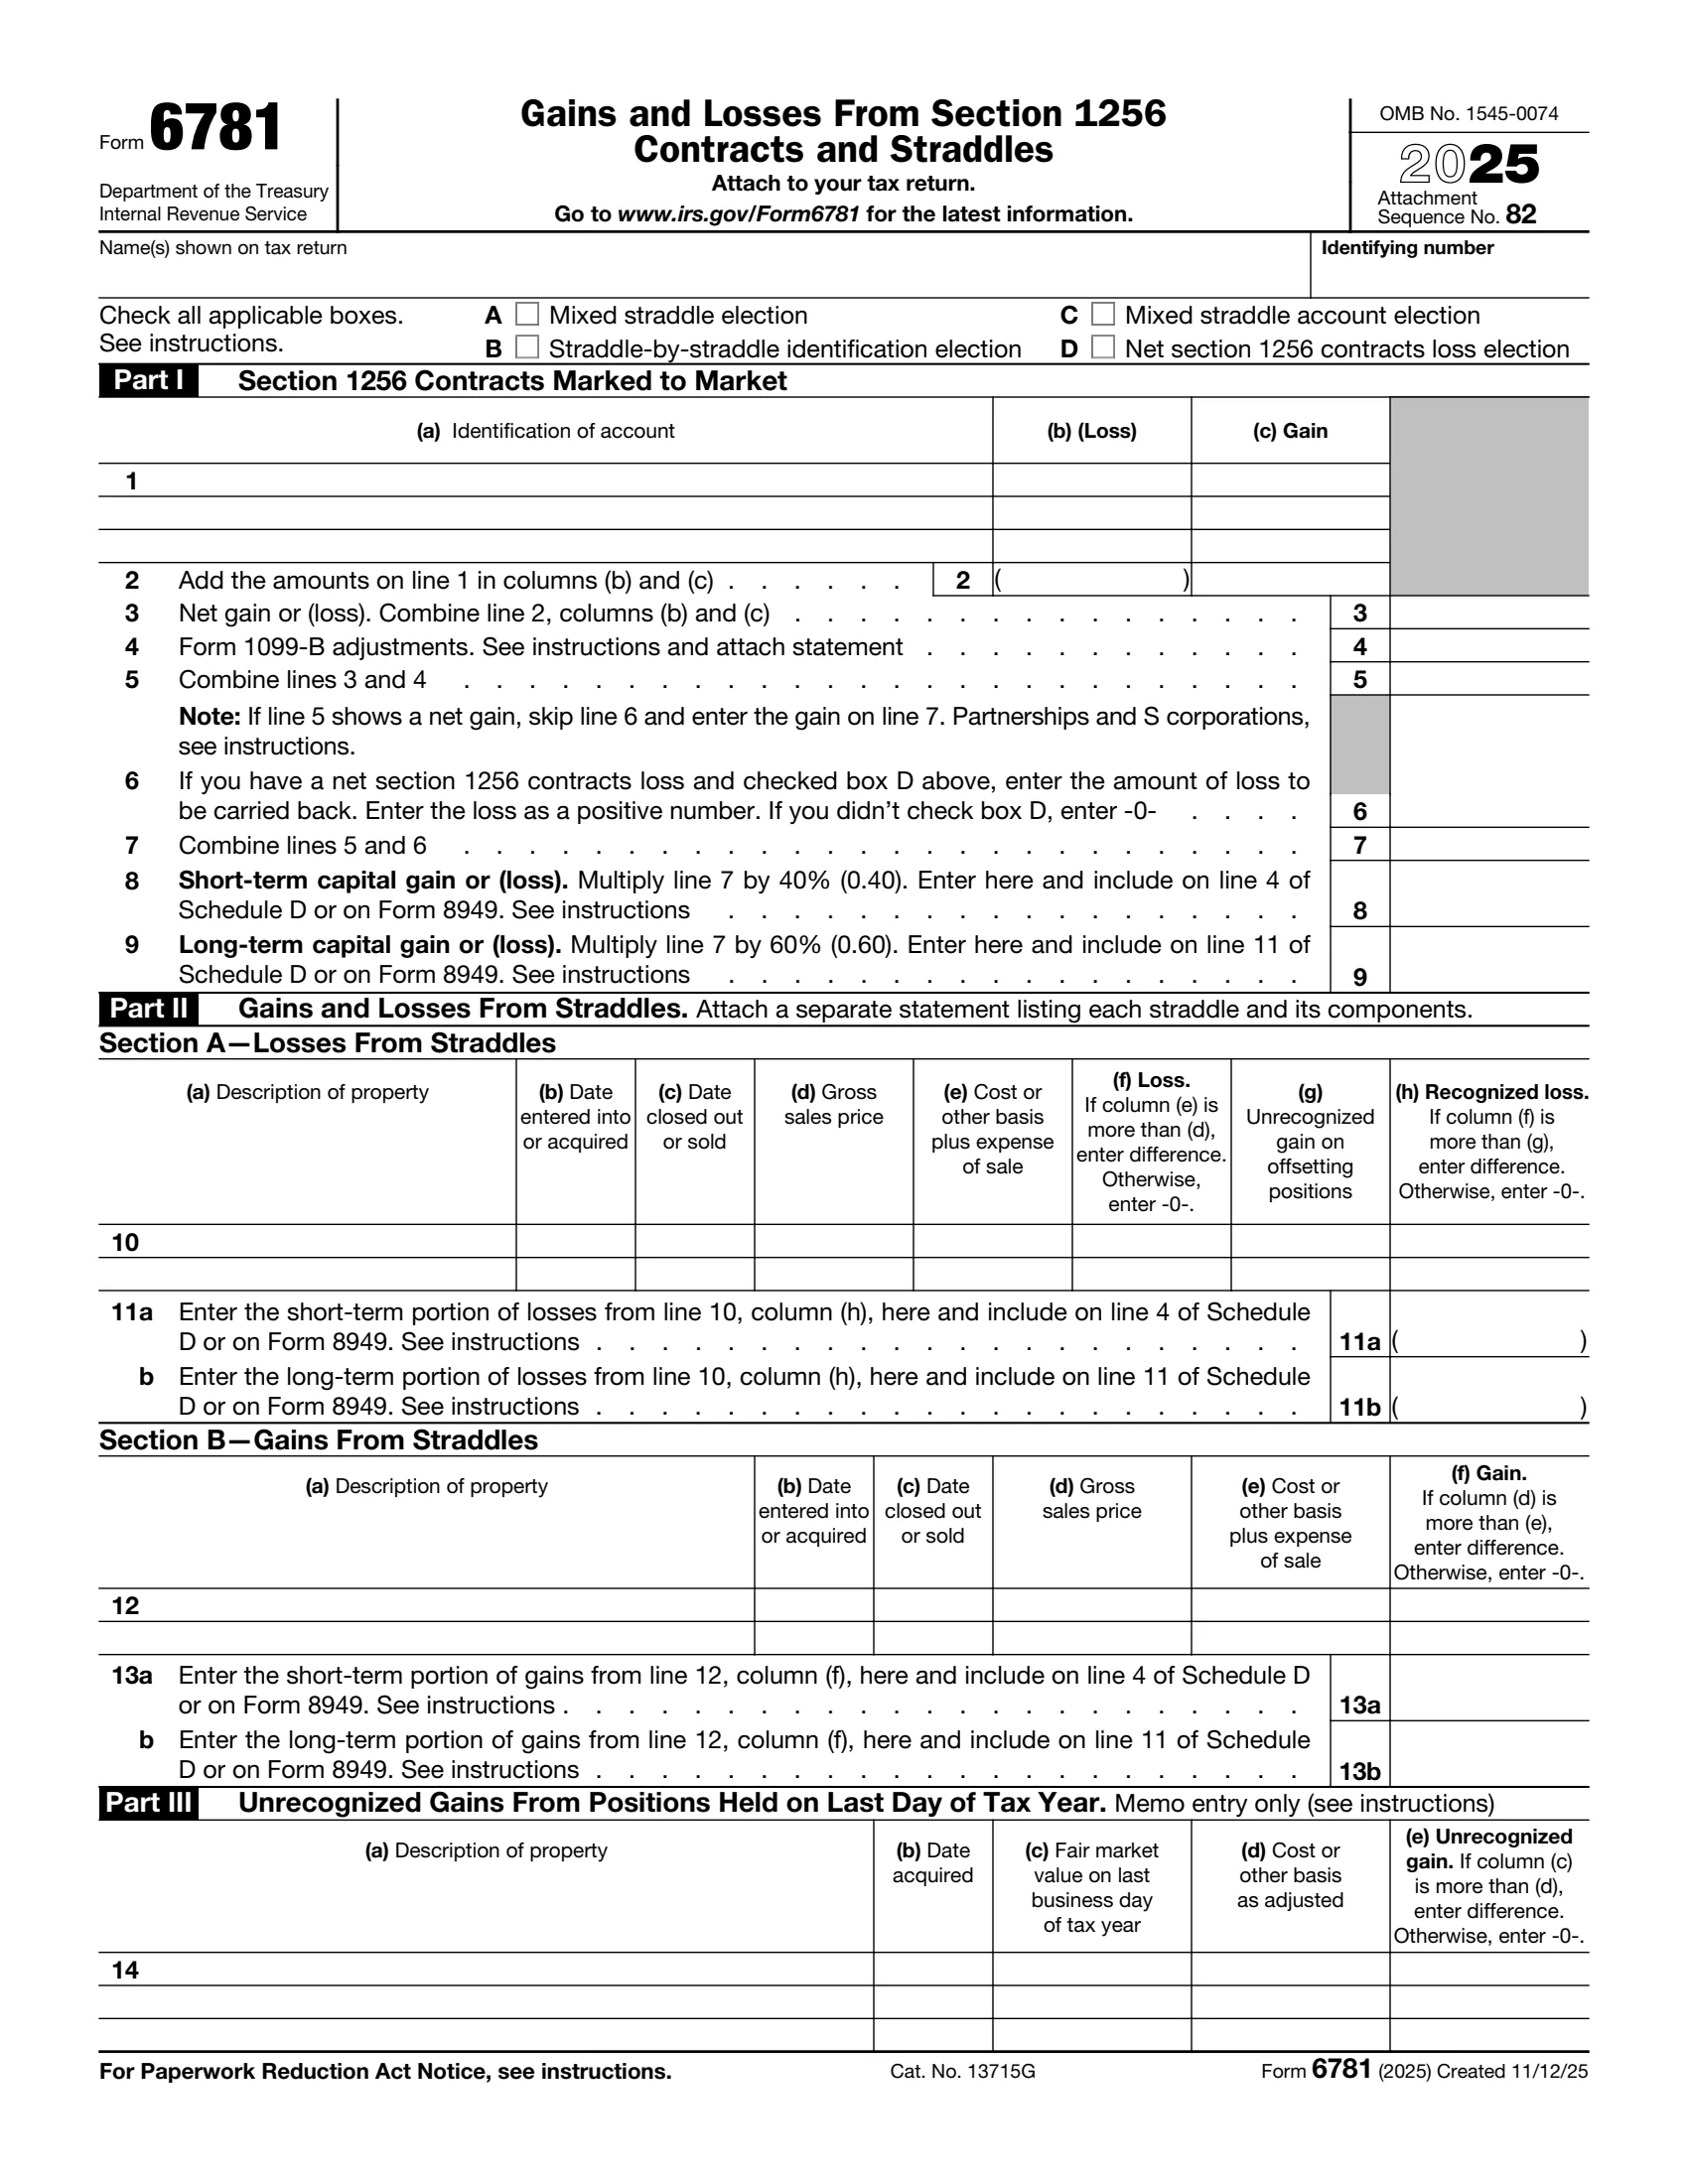
IRS Form 6781, titled “Gains and Losses From Section 1256 Contracts and Straddles,” is used by traders and investors to report gains and losses from section 1256 contracts. Section 1256 contracts include regulated futures contracts, foreign currency contracts, non-equity options, dealer equity options, and dealer securities futures contracts. These contracts are marked to market at the end of each tax year, meaning they are treated as sold for their fair market value on the last day of the year, and any gains or losses are reported at that time.
The form helps calculate the taxable gain or loss that should be included in the taxpayer’s income. One significant feature of Form 6781 is the tax treatment of gains and losses from these contracts, as they are split into short-term and long-term capital gains regardless of the contract’s actual holding period. Specifically, 60% of the gain or loss is treated as long-term and 40% as short-term, regardless of how long the contract has been held. This mixed-straddle accounting method affects the tax rate applied to gains and can be beneficial in managing a taxpayer’s liability.
Other IRS Forms for Individuals
There might be some other financial information you might want to report to the Internal Revenue Service. Check other IRS forms we collected for you.
What it is: Form 6781 (2025) is Gains and Losses From Section 1256 Contracts and Straddles.
Where and when to file: Attach Form 6781 to your tax return.
Use Form 6781 to report any capital gain or loss on section 1256 contracts under the mark-to-market rules, and gains and losses under section 1092 from straddle positions.
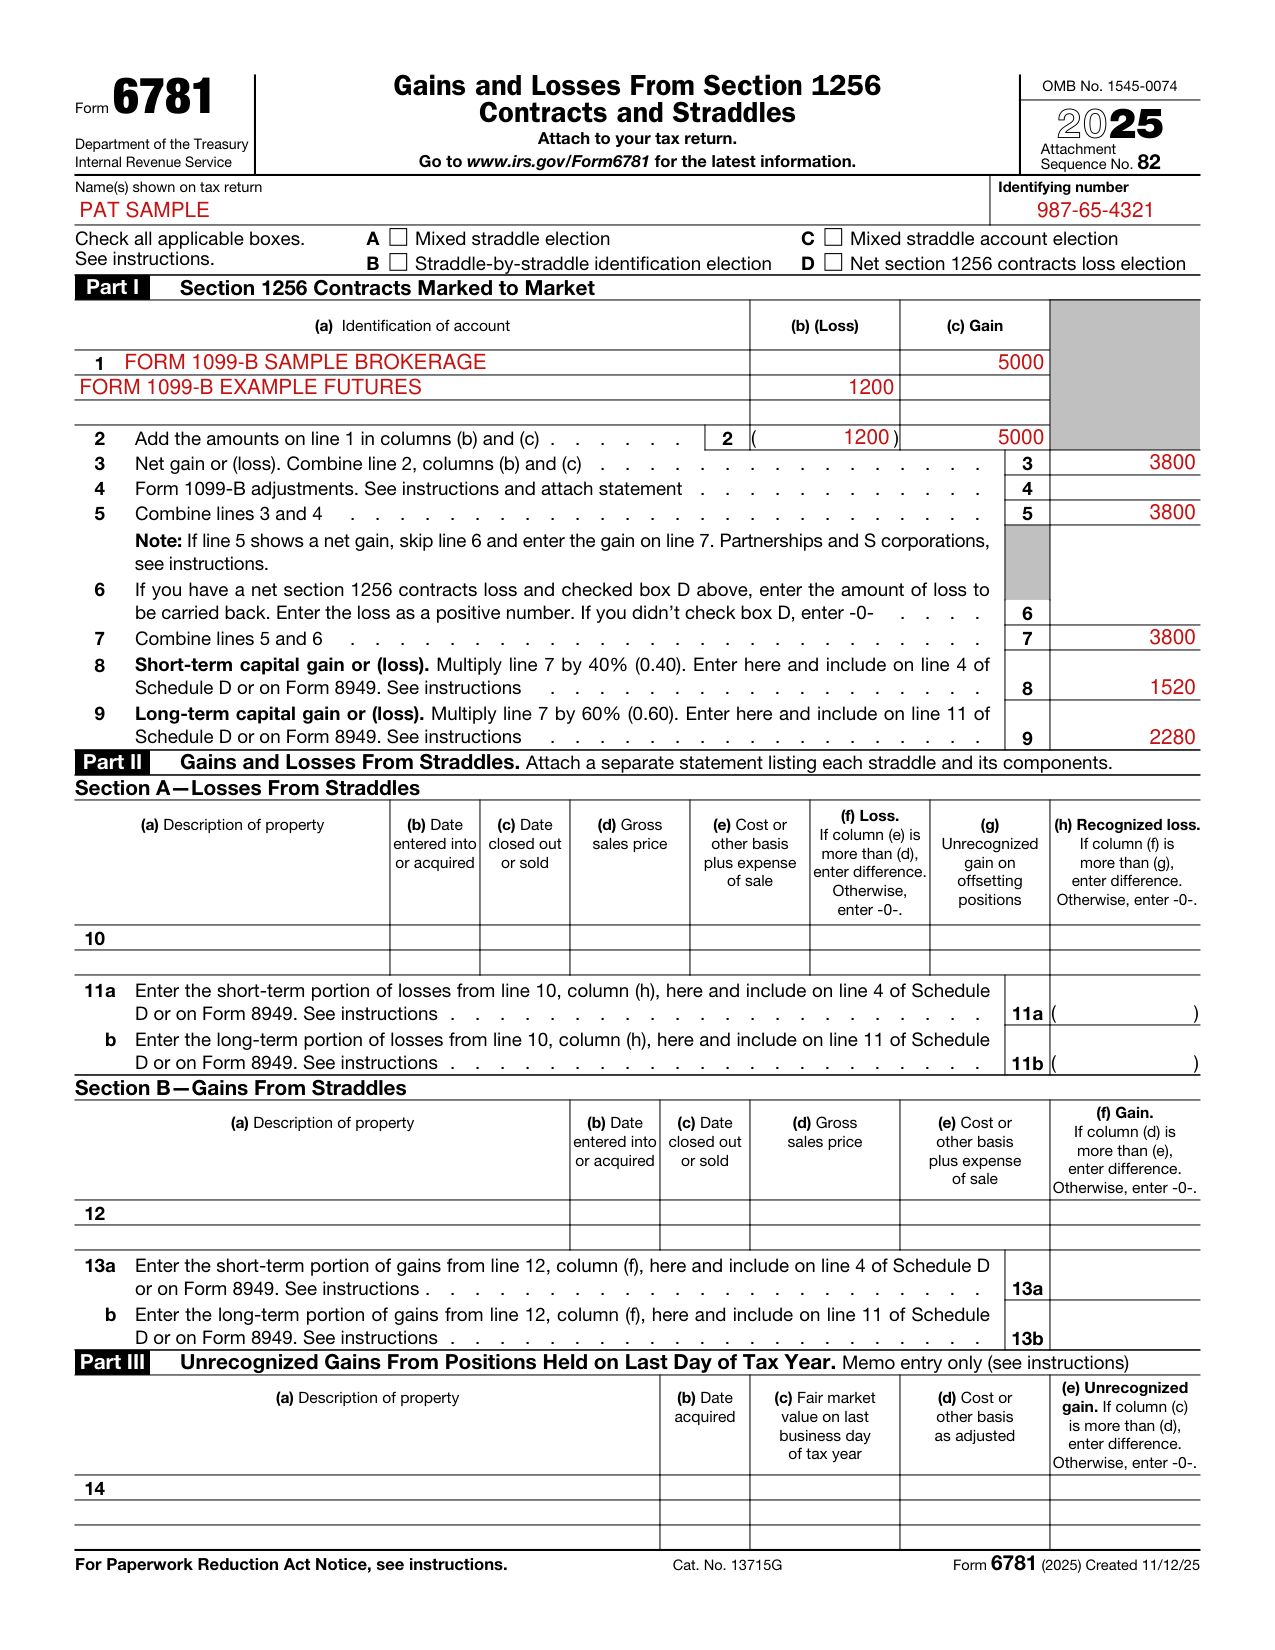

Check all applicable boxes.
Box A, the mixed straddle election: under section 1256(d), you can elect to have the mark-to-market rules not apply to section 1256 contracts that are part of a mixed straddle. If you are making or have previously made this election, check box A and report the section 1256 contract component in Part II instead of in Part I.
Box B, the straddle-by-straddle identification election for mixed straddles under Temporary Regulations section 1.1092(b)-3T(d): if you are making or have previously made this election, check box B.
Box C, the mixed straddle account election: make this election according to Temporary Regulations section 1.1092(b)-4T(f) to establish one or more mixed straddle accounts for 2026 by the due date (without extensions) of your 2025 tax return. To make this election, check box C and attach to your return (or your request for an extension of time to file) the statement required by the regulations.
If you have a net section 1256 contracts loss for 2025, you can elect to carry it back 3 years. Make the election by checking box D and entering the amount to be carried back on line 6.
Corporations, estates, and trusts are not eligible to make the election to carry a net section 1256 contracts loss for 2025 back 3 years.
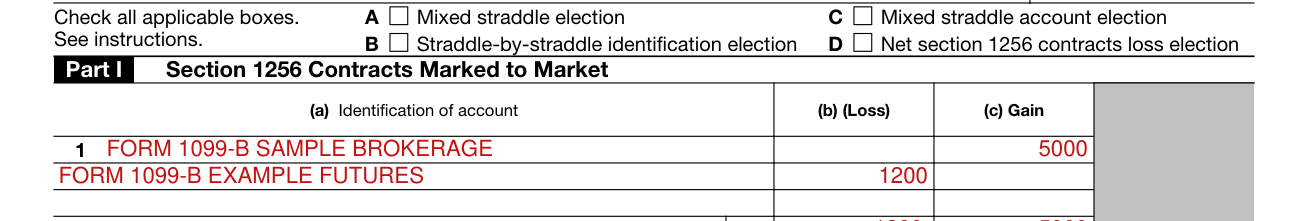
Include on line 1 all capital gains and losses from section 1256 contracts open at the end of your tax year or closed out during the year.
If you received a Form 1099-B, Proceeds From Broker and Barter Exchange Transactions, or substitute statement, include on line 1 the amount from box 11 of each form. In column (a), enter "Form 1099-B" and the broker's name.
List separately each transaction for which you didn't receive a Form 1099-B or substitute statement, or received a Form 1099-B that isn't for your tax year.
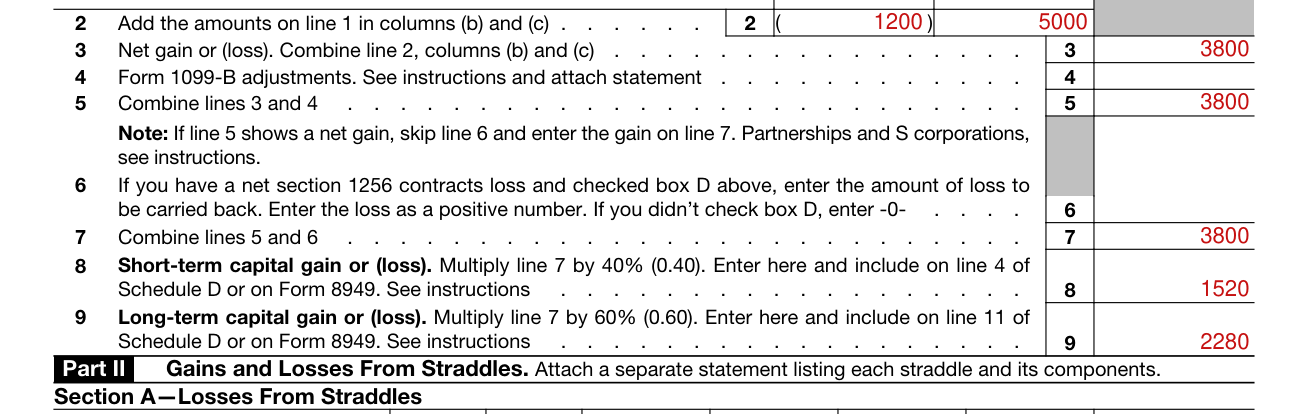
On line 2, add the amounts on line 1 in columns (b) and (c).
On line 3, enter the net gain or (loss): combine line 2, columns (b) and (c).
On line 4, enter the Form 1099-B adjustments: see the instructions and attach a statement.
Don't use line 4 to show the adjustment for a QOF-related deferral.
On line 5, combine lines 3 and 4. If line 5 shows a net gain, skip line 6 and enter the gain on line 7.
If you have a net section 1256 contracts loss and checked box D, enter the amount of loss to be carried back on line 6. Enter the loss as a positive number. If you didn't check box D, enter -0-.
On line 7, combine lines 5 and 6.
On line 8, enter the short-term capital gain or (loss): multiply line 7 by 40% (0.40). Enter it here and include it on line 4 of Schedule D or on Form 8949. See the instructions.
On line 9, enter the long-term capital gain or (loss): multiply line 7 by 60% (0.60). Enter it here and include it on line 11 of Schedule D or on Form 8949. See the instructions.
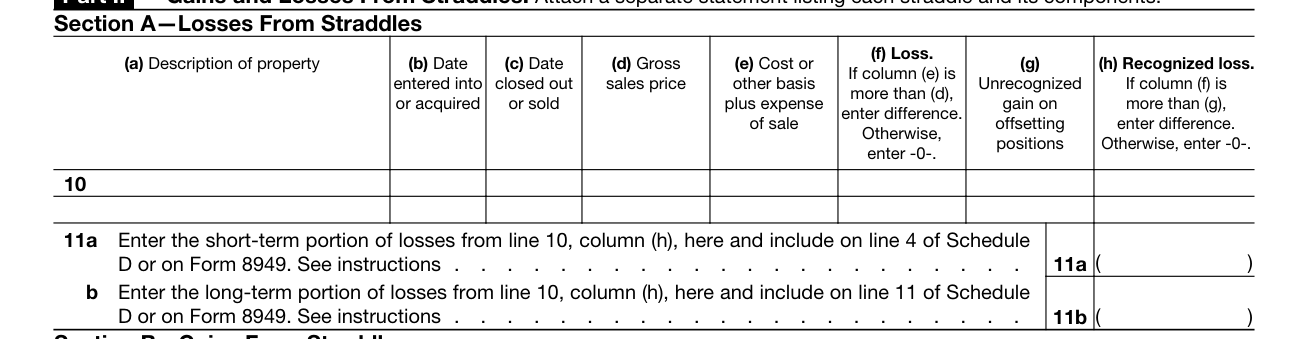
Attach a separate statement listing each straddle and its components.
Use Section A for losses from positions that are part of a straddle.
Generally, a loss is allowed to the extent it exceeds the unrecognized gain on offsetting positions. The part of the loss not allowed is treated as if incurred in the following year and is allowed to the same extent.
If you don't make any of the elections described in box A, B, or C, and you have a loss on the section 1256 contract component, use Part II to reduce the loss by any unrecognized gain on the non-section 1256 contract component before making an entry in Part I.
On page 4 of Form 6781 (2025), don't include in Part II a disposition of a position that is part of a hedging transaction.
On page 4 of Form 6781 (2025), don't include in Part II a disposition of a loss position included in an identified straddle established before October 22, 2004, unless you disposed of all of the positions making up the straddle, or of a loss position included in an identified straddle established after October 21, 2004.
On page 4 of Form 6781 (2025), don't include in Part II a disposition of a position that is part of a straddle if all of the positions of the straddle are section 1256 contracts.
On line 10, column (a), enter the property and delivery date and indicate whether the property is a long or short position.
On line 10, column (d), for positions closed out or sold, enter the closing price or sales price.
On lines 11 and 13, separate recognized gains and losses into short term and long term. Attach a separate statement for each.
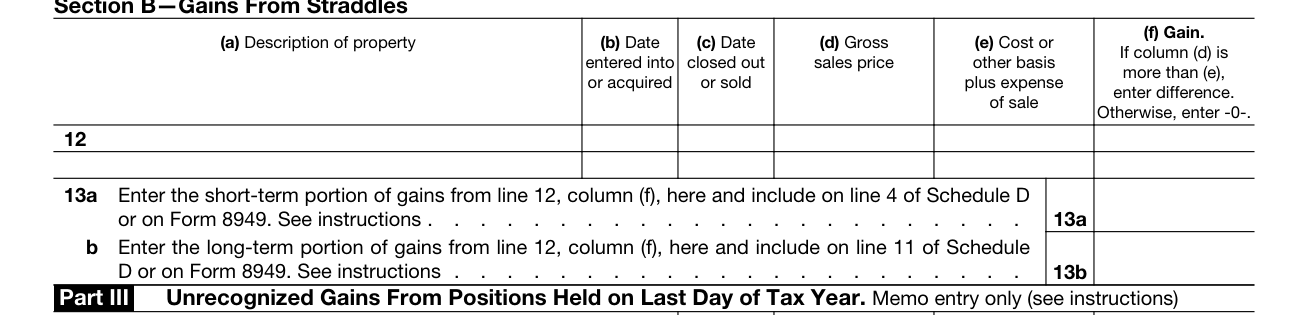
Use Section B for gains from positions that are part of a straddle.
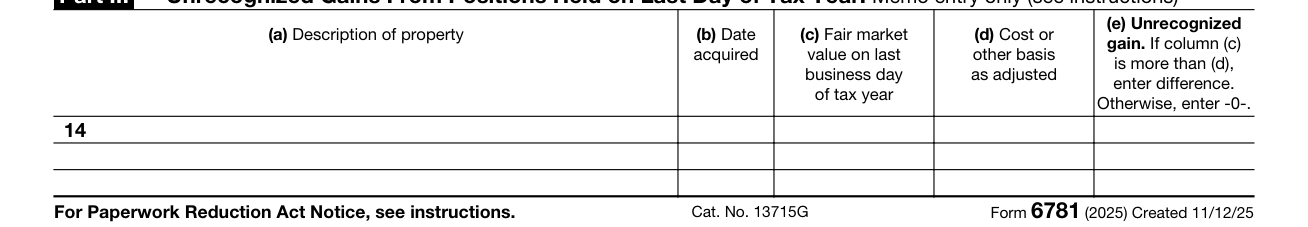
Complete Part III by listing each position (whether or not part of a straddle) that you held at the end of the tax year (including any position you are treated as holding because it is held by a related party) if the FMV of the position at such time exceeds your cost or other basis as adjusted.
Don't include positions that are part of an identified straddle or hedging transaction, property that is stock in trade or inventory, or property subject to depreciation used in a trade or business.
Don't complete Part III if you don't have a recognized loss on any position (including section 1256 contracts).
A section 1256 contract doesn't include any securities future contract, option on a securities future contract, interest rate swap, currency swap, basis swap, commodity swap, equity swap, equity index swap, credit default swap, interest rate cap, interest rate floor, or similar agreement.
Under the mark-to-market rules, each section 1256 contract held at year end is treated as if it were sold at fair market value (FMV) on the last business day of the tax year. The wash sale rules don't apply.
Partnerships enter the amount from line 5 on Form 1065, Schedule K, line 11.
S corporations enter the amount from line 5 on Form 1120-S, Schedule K, line 10.
Lines 6 through 9 on Form 6781, Part I, don't apply to partnerships or S corporations and are left blank.
If you held a qualified investment in a qualified opportunity fund (QOF) at any time during the year, you must file your return with Form 8997.
To carry your loss back, file Form 1045, Application for Tentative Refund, or an amended return.
Attach an amended Form 6781 and an amended Schedule D (Form 1040) for the applicable years.
A section 1256 contract is any regulated futures contract, foreign currency contract, nonequity option, dealer equity option, or dealer securities futures contract.
If your section 1256 contracts produce capital gain or loss, gains or losses on section 1256 contracts open at the end of the year, or terminated during the year, are treated as 60% long term and 40% short term, regardless of how long the contracts were held.
[1] Form 6781 (2025), Gains and Losses From Section 1256 Contracts and Straddles, Internal Revenue Service (the Official source link on this page).