
Updated:
Get Form Now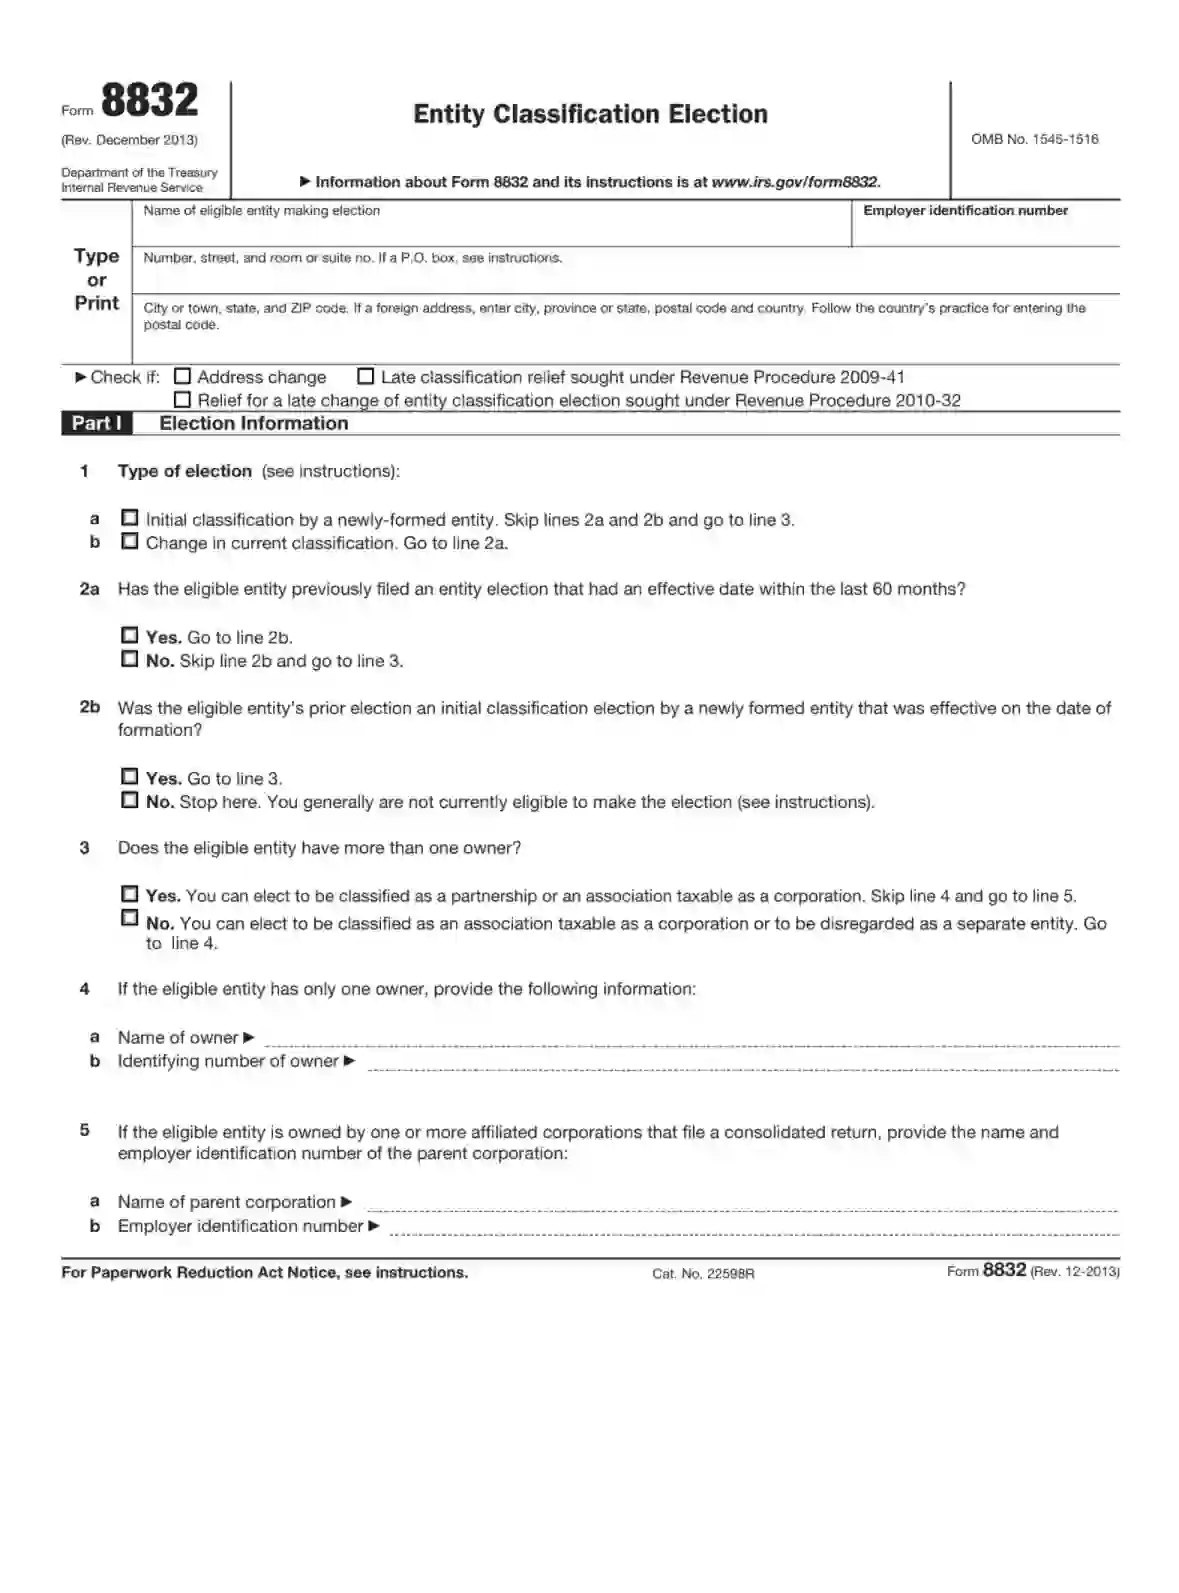
IRS Form 8832 is a document eligible entities use to elect how they want to be classified for federal tax purposes. An eligible entity, typically a business entity such as a corporation or partnership, can use this form to change its classification to either a corporation, a partnership, or a disregarded entity if it is a single-member limited liability company (LLC). This choice directly affects how the entity is taxed, including the tax rates applicable and the tax reporting requirements.
Form 8832 allows business entities flexibility in choosing a tax classification that best suits their operational and financial goals. Depending on the entity’s specific circumstances, making an election can lead to significant tax advantages. For example, a business might change its classification to be treated as a corporation to benefit from corporate tax rates or be disregarded as separate from its owner for a simpler tax reporting process.
Other IRS Forms for Business
The US Internal Revenue Service devised forms to report various types of information about businesses. Check whether your business has considered preparing some other necessary IRS forms.
What it is: An eligible entity uses Form 8832, Entity Classification Election, to elect how it will be classified for federal tax purposes, as a corporation, a partnership, or an entity disregarded as separate from its owner.
Who signs: Form 8832 must be signed by: 1. Each member of the electing entity who is an owner at the time the election is filed; or 2. Any officer, manager, or member of the electing entity who is authorized (under local law or the organizational documents) to make the election.
Where and when to file: File Form 8832 with the Internal Revenue Service Center for your state. Generally, an election specifying an eligible entity's classification cannot take effect more than 75 days prior to the date the election is filed, nor can it take effect later than 12 months after the date the election is filed.
File this form for a domestic entity electing to be classified as an association taxable as a corporation.
File this form for a domestic entity or a foreign entity electing to change its current classification (even if it is currently classified under the default rule).
File this form for a foreign entity that has more than one owner, all owners having limited liability, electing to be classified as a partnership.
File this form for a foreign entity that has at least one owner that does not have limited liability, electing to be classified as an association taxable as a corporation.
File this form for a foreign entity with a single owner having limited liability, electing to be an entity disregarded as an entity separate from its owner.
Enter the name of the eligible entity electing to be classified.
Show the EIN of the eligible entity electing to be classified. Do not put “Applied For” on this line.
Enter the address of the entity electing a classification. All correspondence regarding the acceptance or nonacceptance of the election will be sent to the address entered.
If the eligible entity has changed its address since filing Form SS-4 or the entity's most recently-filed return (including a change to an “in care of” address), check the box for an address change.
Check box 1a if the entity is choosing a classification for the first time (i.e., the entity does not want to be classified under the applicable default classification).
Do not file this form if the entity wants to be classified under the default rules.
Check box 1b if the entity is changing its current classification.
1 Type of election: a Initial classification by a newly-formed entity. Skip lines 2a and 2b and go to line 3. b Change in current classification. Go to line 2a.
2 a Has the eligible entity previously filed an entity election that had an effective date within the last 60 months? Yes. Go to line 2b. No. Skip line 2b and go to line 3.
2 b Was the eligible entity's prior election an initial classification election by a newly formed entity that was effective on the date of formation? Yes. Go to line 3. No. Stop here. You generally are not currently eligible to make the election.
Once an eligible entity makes an election to change its classification, the entity generally cannot change its classification by election again during the 60 months after the effective date of the election. The 60-month limitation does not apply if the previous election was made by a newly formed eligible entity and was effective on the date of formation.
3 Does the eligible entity have more than one owner? Yes. You can elect to be classified as a partnership or an association taxable as a corporation. Skip line 4 and go to line 5. No. You can elect to be classified as an association taxable as a corporation or to be disregarded as a separate entity. Go to line 4.
If an eligible entity has only one owner, provide the name of its owner on line 4a and the owner's identifying number (social security number, or individual taxpayer identification number, or EIN) on line 4b.
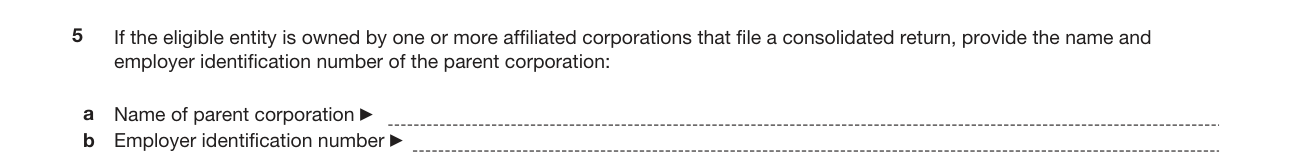
If the eligible entity is owned by one or more members of an affiliated group of corporations that file a consolidated return, provide the name and EIN of the parent corporation.
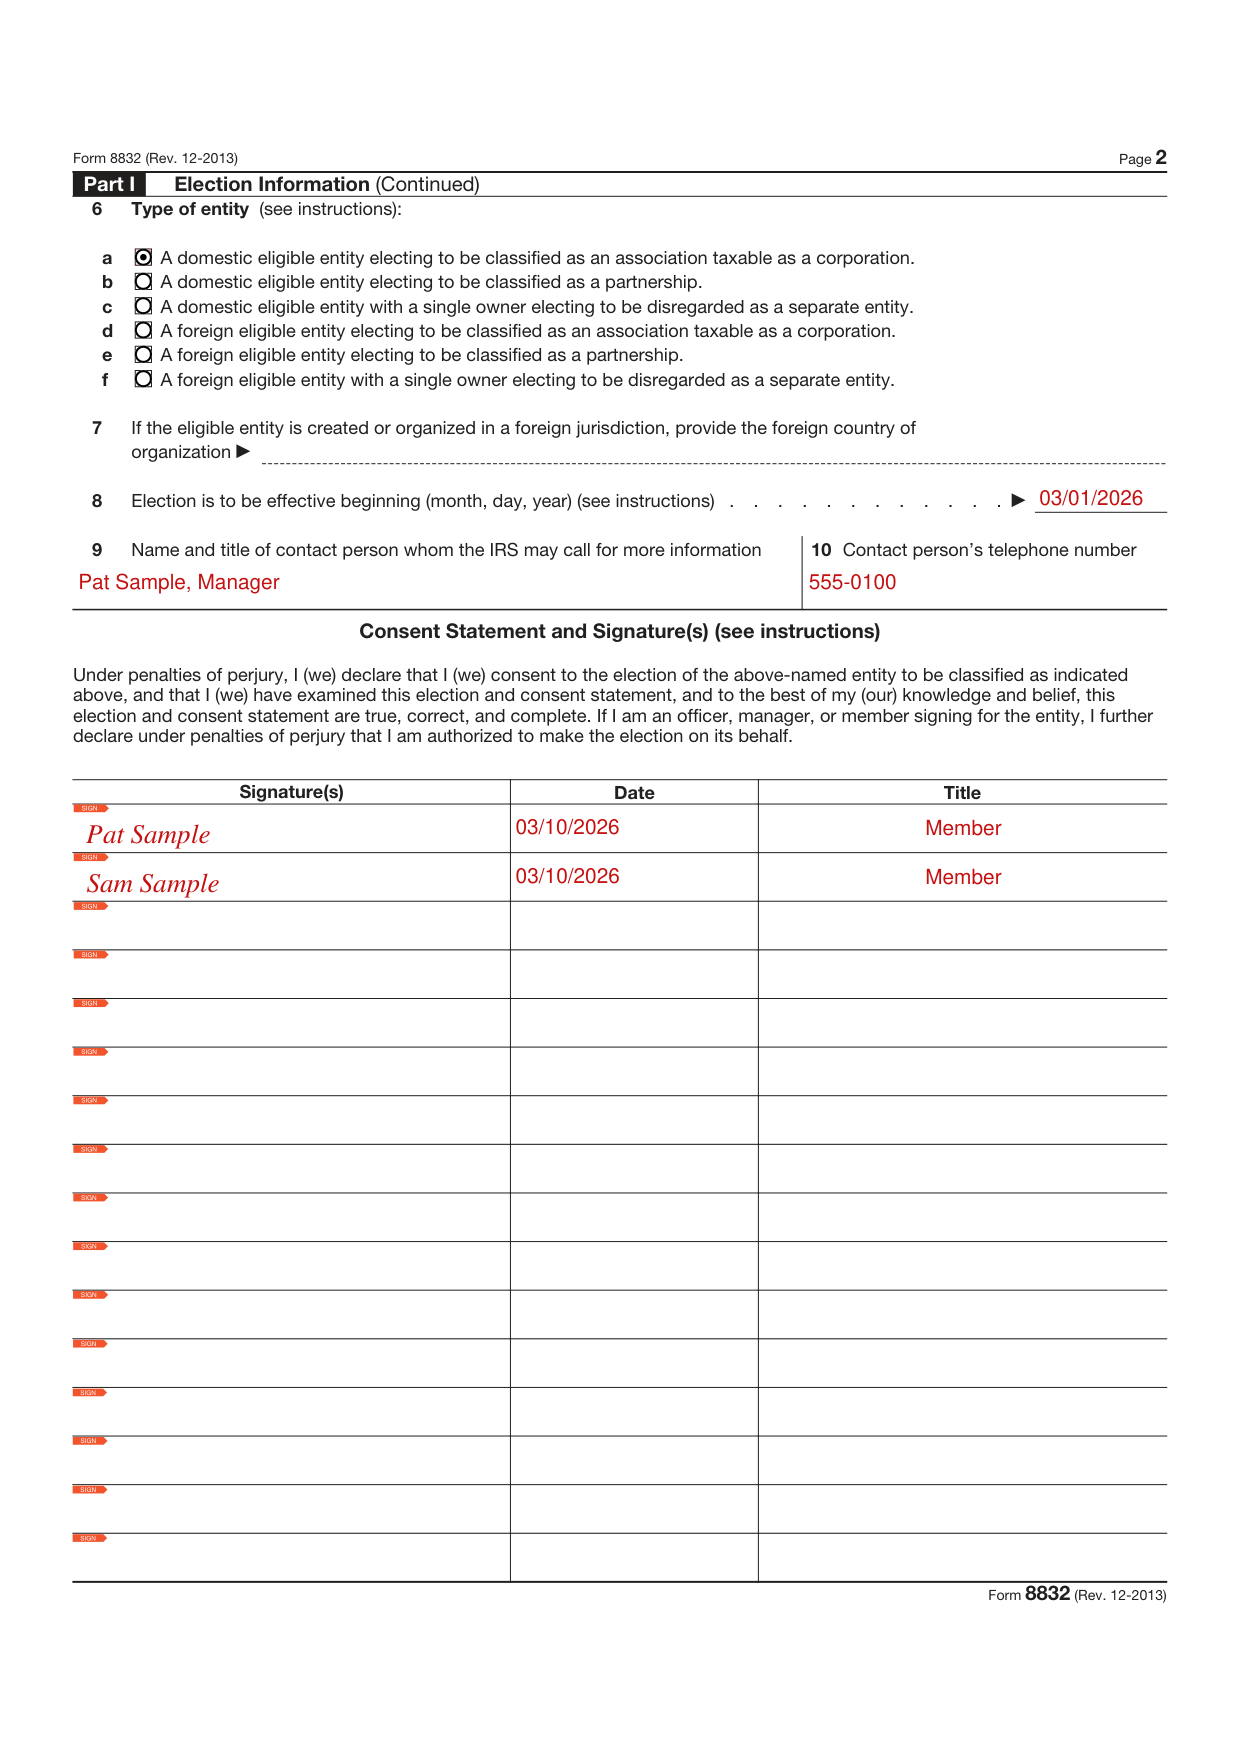
Type of entity: a A domestic eligible entity electing to be classified as an association taxable as a corporation. b A domestic eligible entity electing to be classified as a partnership. c A domestic eligible entity with a single owner electing to be disregarded as a separate entity. d A foreign eligible entity electing to be classified as an association taxable as a corporation. e A foreign eligible entity electing to be classified as a partnership. f A foreign eligible entity with a single owner electing to be disregarded as a separate entity.

If the entity making the election is created or organized in a foreign jurisdiction, enter the name of the foreign country in which it is organized.

Election is to be effective beginning (month, day, year). Generally, the election will take effect on the date you enter on line 8 of this form, or on the date filed if no date is entered on line 8.

Name and title of contact person whom the IRS may call for more information. Contact person's telephone number.
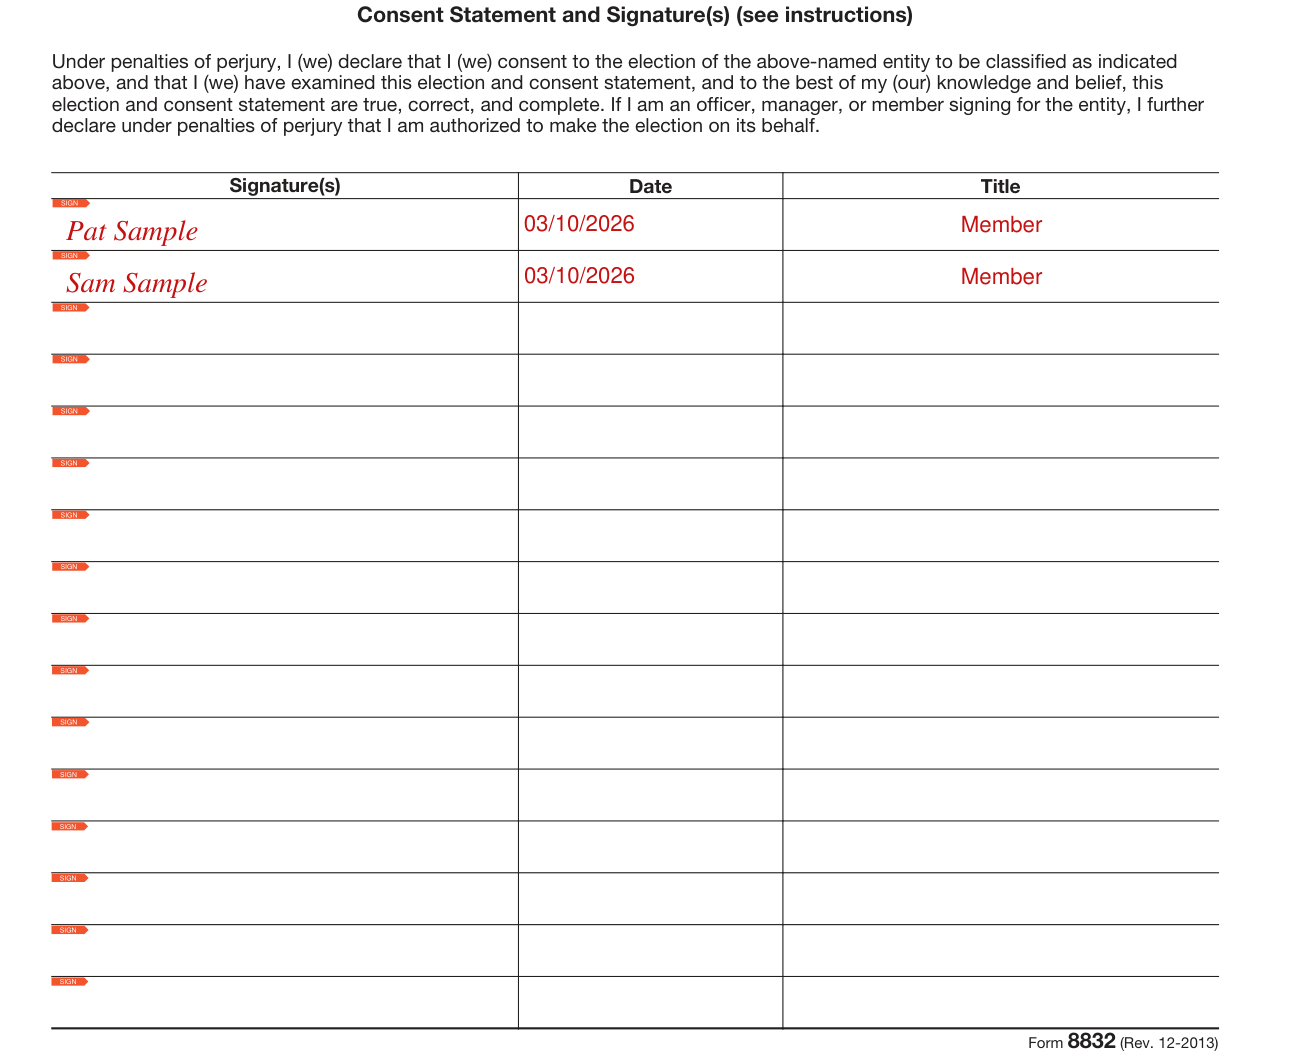
Consent Statement and Signature(s): If I am an officer, manager, or member signing for the entity, I further declare under penalties of perjury that I am authorized to make the election on its behalf.
Do not sign the copy that is attached to your tax return.
Complete Part II only if the entity is requesting late election relief under Rev. Proc. 2009-41.
To obtain relief, file Form 8832 with the applicable IRS service center within 3 years and 75 days from the requested effective date of the eligible entity's classification election.
11 Provide the explanation as to why the entity classification election was not filed on time.
Part II of Form 8832 must be signed by an authorized representative of the eligible entity and each affected person.
Attach a copy of Form 8832 to the entity's federal tax or information return for the tax year of the election.
If the entity is not required to file a return for that year, a copy of its Form 8832 must be attached to the federal tax returns of all direct or indirect owners of the entity for the tax year of the owner that includes the date on which the election took effect.
The entity should generally receive a determination on its election within 60 days after it has filed Form 8832.
Taxpayers in Connecticut, Delaware, District of Columbia, Georgia, Illinois, Indiana, Kentucky, Maine, Maryland, Massachusetts, Michigan, New Hampshire, New Jersey, New York, North Carolina, Ohio, Pennsylvania, Rhode Island, South Carolina, Vermont, Virginia, West Virginia, Wisconsin mail the form to Department of the Treasury Internal Revenue Service Center Kansas City, MO 64999. Taxpayers in Alabama, Alaska, Arizona, Arkansas, California, Colorado, Florida, Hawaii, Idaho, Iowa, Kansas, Louisiana, Minnesota, Mississippi, Missouri, Montana, Nebraska, Nevada, New Mexico, North Dakota, Oklahoma, Oregon, South Dakota, Tennessee, Texas, Utah, Washington, Wyoming mail the form to Department of the Treasury Internal Revenue Service Center Ogden, UT 84201.
Failure to attach a copy of Form 8832 will not invalidate an otherwise valid election, but penalties may be assessed against persons who are required to, but do not, attach Form 8832. Penalties apply to returns filed inconsistent with the entity's election.
Do not file this form for an eligible entity that is: Tax-exempt under section 501(a); A real estate investment trust (REIT), as defined in section 856; or Electing to be classified as an S corporation. An entity must file Form 2553 if making an election under section 1362(a) to be an S corporation. A new eligible entity should not file Form 8832 if it will be using its default classification (see Default Rules).
[1] Form 8832 (Rev. December 2013), Entity Classification Election, Department of the Treasury, Internal Revenue Service (the Official source link on this page).